Smaller revenue, wider margins
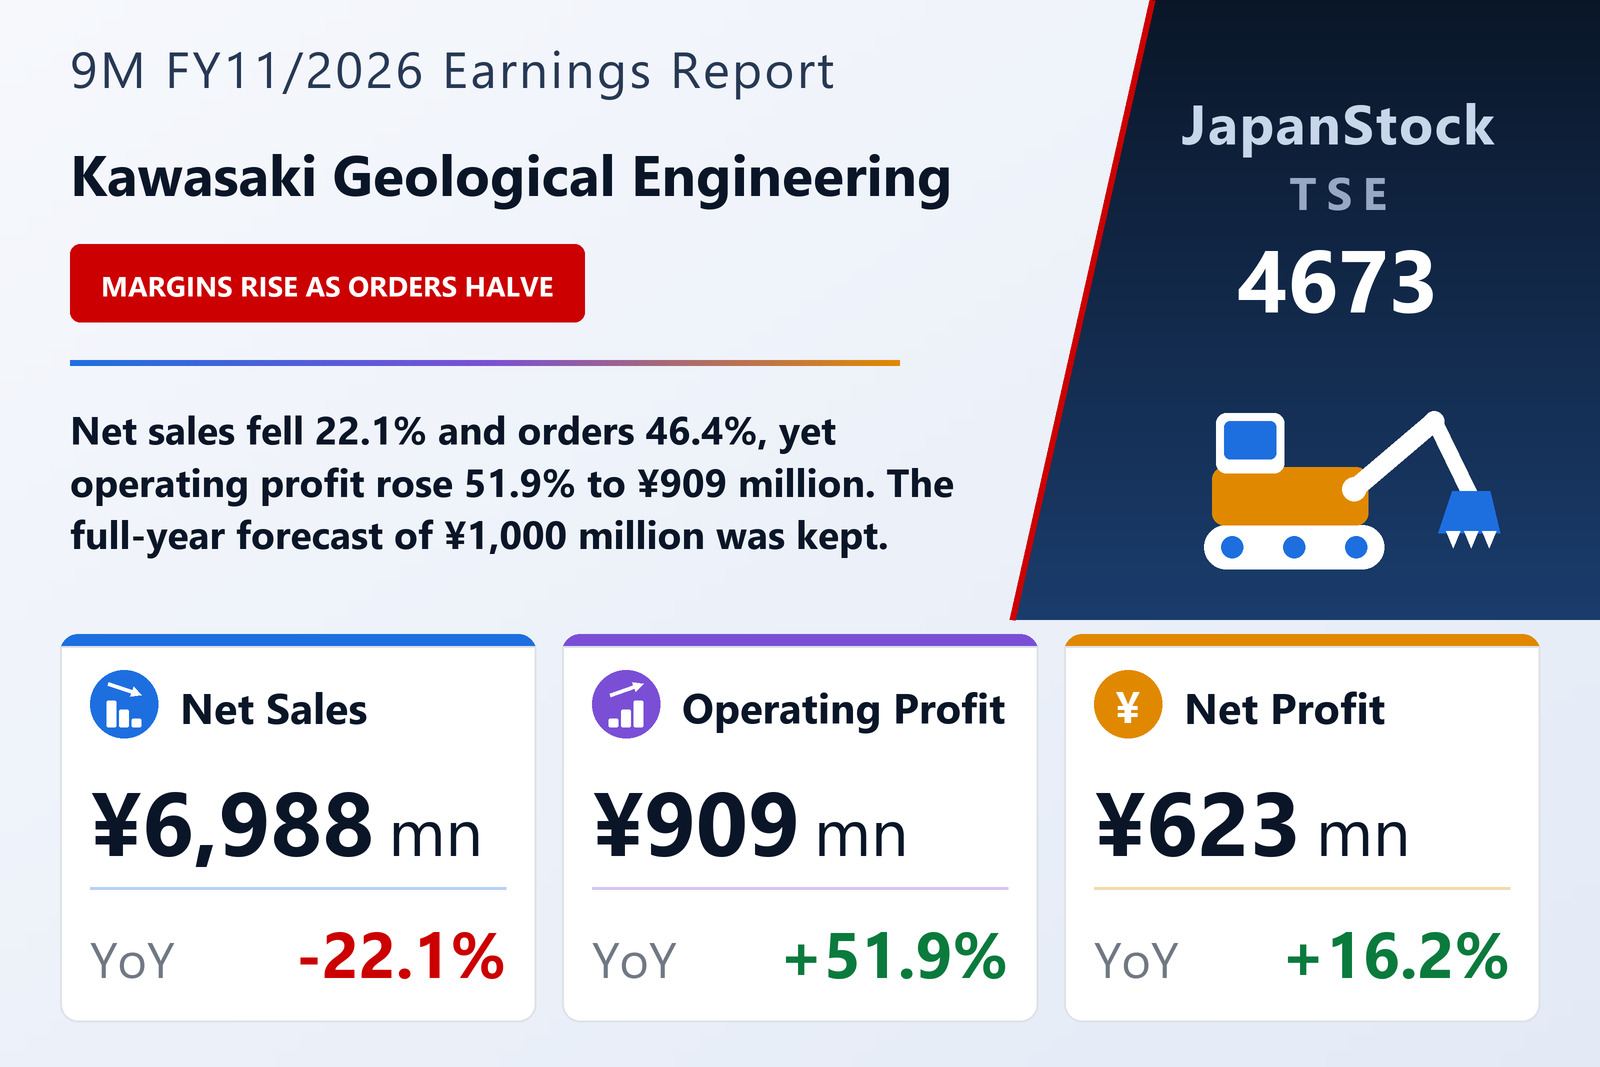
Kawasaki Geological Engineering Co., Ltd. (TSE: 4673) reported consolidated results for the first nine months of FY11/2026, from December 1, 2025 to August 31, 2026, on October 14, 2026 under Japanese GAAP. Net sales fell 22.1% to ¥6,988 million, a pull-back from the prior year's 37.0% jump, while operating profit rose 51.9% to ¥909 million and ordinary profit 42.4% to ¥955 million. Net profit attributable to owners of the parent increased 16.2% to ¥623 million, or ¥713.38 per share against ¥615.36.
The company concentrates on survey, inspection, diagnosis, analysis and design work for maintaining infrastructure, alongside disaster-prevention, renewable-energy, marine-resource and defence-related geological surveys. It points to Japan's first mid-term plan for national resilience, approved in June 2025, which earmarks a little over ¥20 trillion of projects for fiscal 2026 to 2030, as support for public-works demand.
Orders nearly halve
Orders received fell 46.4% to ¥6,188 million. The company attributes the drop to projects it did not win as market conditions and competition shifted, and says it will strengthen sales activity in response. Because most of its customers are government bodies and public enterprises, sales and profit tend to cluster in the second and fourth quarters. One subsidiary was added to the scope of consolidation during the period.
Balance sheet
Total assets fell 28.6% to ¥8,542 million from November 30, 2025, mainly because completed-survey receivables and contract assets dropped by ¥4,585 million to ¥1,933 million. Cash rose ¥695 million to ¥1,793 million, while short-term borrowings were cut by ¥2,600 million to ¥520 million. Net assets increased 9.5% to ¥5,749 million, lifting the equity ratio to 67.3% from 43.9%.
Outlook and dividend
The FY11/2026 forecast published on April 10 is unchanged: net sales of ¥10,500 million (−17.4%), operating profit of ¥1,000 million (+50.2%), ordinary profit of ¥1,060 million (+43.8%) and net profit of ¥740 million (+19.3%). The company plans an annual dividend of ¥145, a ¥25 interim payment plus ¥120 at year-end, the same as last year.
| Metric | 9M FY11/2026 | 9M FY11/2025 | Change |
|---|---|---|---|
| Net sales (¥ million) | 6,988 | 8,972 | −22.1% |
| Operating profit (¥ million) | 909 | 598 | +51.9% |
| Ordinary profit (¥ million) | 955 | 671 | +42.4% |
| Net profit attrib. to owners of parent (¥ million) | 623 | 536 | +16.2% |
| EPS (¥) | 713.38 | 615.36 | +15.9% |
| Comprehensive income (¥ million) | 624 | 506 | +23.2% |
| Orders received (¥ million) | 6,188 | — | −46.4% |
| Total assets (¥ million) | 8,542 | 11,956 | −28.6% |
| Net assets (¥ million) | 5,749 | 5,248 | +9.5% |
| Equity ratio | 67.3% | 43.9% | +23.4 pt |
| FY11/2026 guidance — revenue (¥ million) | 10,500 | — | −17.4% |
| FY11/2026 guidance — operating profit (¥ million) | 1,000 | — | +50.2% |
| FY11/2026 guidance — ordinary profit (¥ million) | 1,060 | — | +43.8% |
| FY11/2026 guidance — net profit (¥ million) | 740 | — | +19.3% |
| Annual dividend per share (¥) | 145.00 | 145.00 | unchanged |
JapanStockPulse provides informational content only and does not constitute investment advice. Figures are taken from the company's published earnings short report and may be subject to subsequent revision.