Steady growth across the group
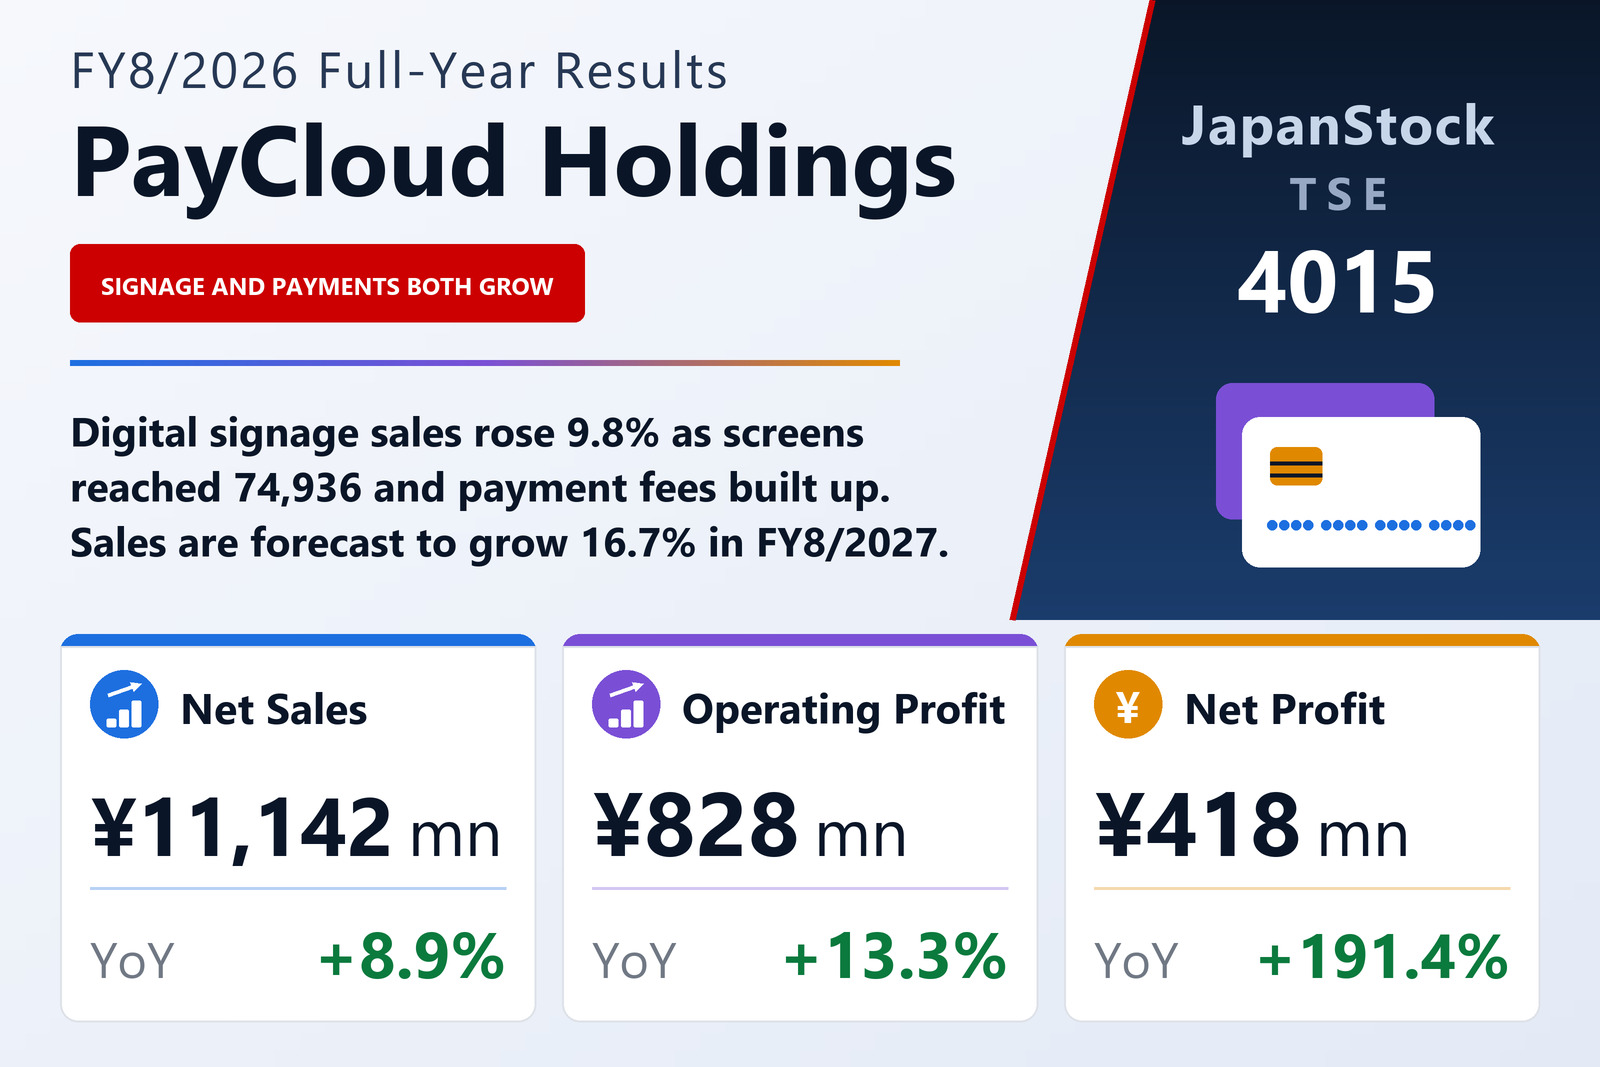
PayCloud Holdings Inc. (TSE: 4015) reported consolidated results for FY8/2026, the twelve months from September 1, 2025 to August 31, 2026, on October 15, 2026 under Japanese GAAP. Net sales rose 8.9% to ¥11,142 million, operating profit 13.3% to ¥828 million and ordinary profit 13.7% to ¥812 million. Adjusted EBITDA, which adds depreciation and share-based compensation to operating profit and which the group treats as its key indicator, rose 5.3% to ¥1,357 million. Net profit attributable to owners of the parent rose 191.4% to ¥418 million, or ¥26.48 per share.
Payments and screens
The cashless services business grew sales 2.5% to ¥3,862 million and segment profit 2.5% to ¥822 million, with fee income building and margins running ahead of plan. It ended the year with 1,164 client companies and a cumulative 244.33 million end users, and the year's transaction value through its branded payment services came to roughly ¥1.58 trillion; in April it also launched Omairi Pay, a cashless service for temples and shrines developed with the Kyoto Buddhist Association. Digital signage grew sales 9.8% to ¥6,249 million and profit 6.8% to ¥860 million as multi-store chains, shopping centres and offices installed screens, taking the cumulative total to 74,936 screens at 32,782 locations. The solutions business, built on subsidiary Arara's messaging service, grew sales 2.9% but saw profit fall 7.3% to ¥276 million, while a new contactless-payment business delivered its first products and lifted other sales to ¥247 million.
Balance sheet and outlook
Total assets edged down 0.9% to ¥9,326 million as cash and deposits fell by ¥539 million, while net assets rose 4.5% to ¥4,736 million, lifting the equity ratio to 48.8% from 46.5%. Operating cash flow fell to ¥227 million from ¥1,408 million, and cash ended the year at ¥3,834 million. For FY8/2027 the company forecasts net sales of ¥13,000 million (+16.7%), adjusted EBITDA of ¥1,400 million (+3.1%), operating profit of ¥840 million (+1.4%) and net profit of ¥580 million (+38.5%). It paid no dividend and plans none for FY8/2027.
| Metric | FY8/2026 | FY8/2025 | Change |
|---|---|---|---|
| Net sales (¥ million) | 11,142 | 10,234 | +8.9% |
| Adjusted EBITDA (¥ million) | 1,357 | 1,289 | +5.3% |
| Operating profit (¥ million) | 828 | 731 | +13.3% |
| Ordinary profit (¥ million) | 812 | 714 | +13.7% |
| Net profit attrib. to owners of parent (¥ million) | 418 | 143 | +191.4% |
| EPS (¥) | 26.48 | 9.06 | +192.3% |
| Cashless services — revenue (¥ million) | 3,862 | 3,768 | +2.5% |
| Cashless services — segment profit (¥ million) | 822 | 802 | +2.5% |
| Digital signage — revenue (¥ million) | 6,249 | 5,690 | +9.8% |
| Digital signage — segment profit (¥ million) | 860 | 805 | +6.8% |
| Total assets (¥ million) | 9,326 | 9,409 | −0.9% |
| Net assets (¥ million) | 4,736 | 4,530 | +4.5% |
| Equity ratio | 48.8% | 46.5% | +2.3 pt |
| FY8/2027 guidance — revenue (¥ million) | 13,000 | — | +16.7% |
| FY8/2027 guidance — adjusted EBITDA (¥ million) | 1,400 | — | +3.1% |
| FY8/2027 guidance — operating profit (¥ million) | 840 | — | +1.4% |
| FY8/2027 guidance — ordinary profit (¥ million) | 820 | — | +1.0% |
| FY8/2027 guidance — net profit (¥ million) | 580 | — | +38.5% |
| Annual dividend per share (¥) | 0.00 | 0.00 | unchanged |
JapanStockPulse provides informational content only and does not constitute investment advice. Figures are taken from the company's published earnings short report and may be subject to subsequent revision.