Investment gains drive profit
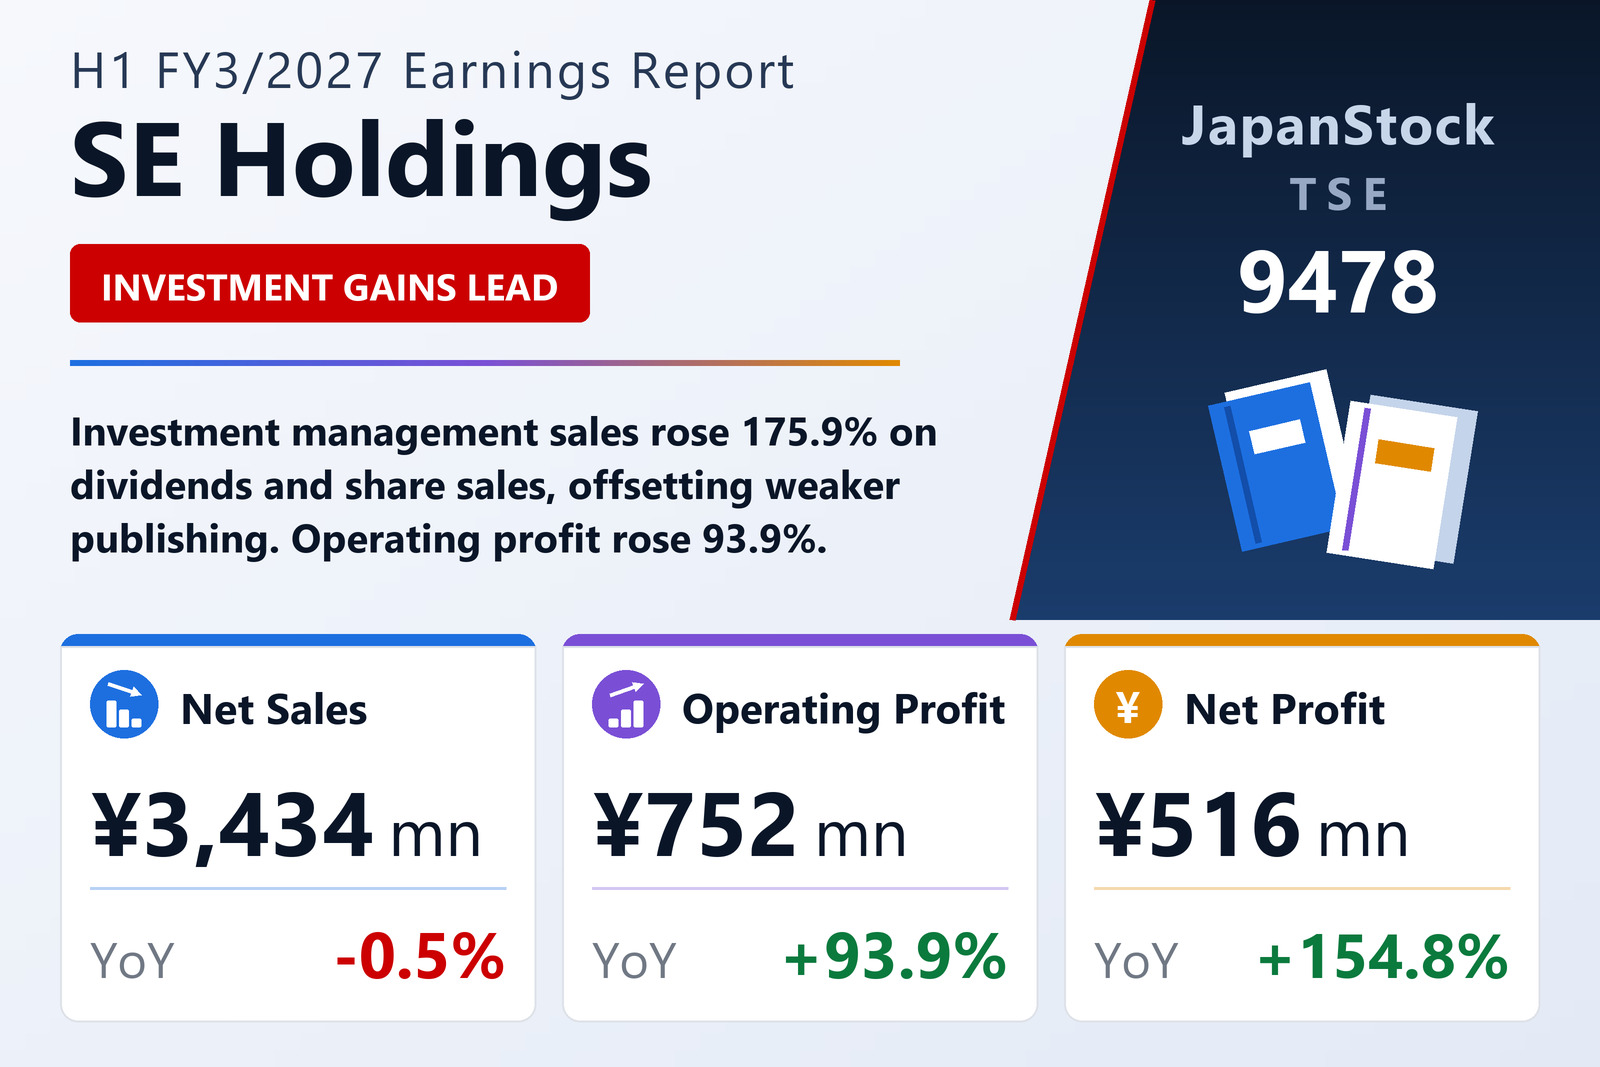
SE Holdings and Incubations Co., Ltd. (TSE: 9478) reported consolidated results for the first half of FY3/2027, from April 1 to September 30, 2026, on October 22, 2026 under Japanese GAAP. Net sales slipped 0.5% to ¥3,434 million, but operating profit rose 93.9% to ¥752 million and ordinary profit 148.8% to ¥762 million. Net profit attributable to owners of the parent increased 154.8% to ¥516 million, or ¥34.15 per share against ¥12.57.
In investment management, a steadily growing portfolio raised dividend income and the company sold part of the holdings it judged overvalued, lifting segment sales 175.9% to ¥662 million and segment profit 219.0% to ¥595 million. Publishing sales fell 11.0% to ¥1,739 million, although print book sales recovered slightly, events performed well and restructuring held segment profit nearly flat at ¥219 million (−2.1%).
Corporate services sales fell 13.9% to ¥261 million after the company became more selective about orders, but cost cuts produced a segment profit of ¥4 million against a loss of ¥22 million. Software and network sales fell 31.4% to ¥294 million as the solutions business stayed weak amid changes in the development market, and the segment slipped to a loss of ¥2 million from a profit of ¥35 million. Education and HR sales fell 9.3% to ¥476 million: medical-staffing placement grew, but IT training stayed soft and staff costs rose, cutting segment profit 44.0% to ¥64 million.
Balance sheet
Total assets rose by ¥1,394 million from March 31 to ¥20,085 million, mainly as operational investment securities increased by ¥1,492 million. Liabilities rose by ¥197 million to ¥7,654 million, including ¥445 million more in deferred tax liabilities. Net assets increased by ¥1,197 million to ¥12,430 million on higher valuation gains on securities and retained earnings, partly offset by share buybacks, and the equity ratio rose to 61.9% from 60.1%. The company spent ¥203 million acquiring its own shares.
Outlook and dividend
The full-year forecast published on October 19 was left unchanged: net sales of ¥6,700 million (−4.7%), operating profit of ¥1,100 million (+15.2%), ordinary profit of ¥1,000 million (+24.4%) and net profit of ¥700 million (+10.5%), or ¥47.26 per share. The company plans a year-end dividend of ¥4, unchanged from the previous year.
| Metric | H1 FY3/2027 | H1 FY3/2026 | Change |
|---|---|---|---|
| Net sales (¥ million) | 3,434 | 3,452 | −0.5% |
| Operating profit (¥ million) | 752 | 388 | +93.9% |
| Ordinary profit (¥ million) | 762 | 306 | +148.8% |
| Net profit attrib. to owners of parent (¥ million) | 516 | 202 | +154.8% |
| EPS (¥) | 34.15 | 12.57 | +171.7% |
| Comprehensive income (¥ million) | 1,446 | 1,237 | +16.9% |
| Publishing — revenue (¥ million) | 1,739 | 1,953 | −11.0% |
| Publishing — segment profit (¥ million) | 219 | 223 | −2.1% |
| Corporate services — revenue (¥ million) | 261 | 304 | −13.9% |
| Corporate services — segment profit (¥ million) | 4 | −22 | loss to profit |
| Software & network — revenue (¥ million) | 294 | 429 | −31.4% |
| Software & network — segment profit (¥ million) | −2 | 35 | profit to loss |
| Education & HR — revenue (¥ million) | 476 | 524 | −9.3% |
| Education & HR — segment profit (¥ million) | 64 | 115 | −44.0% |
| Investment management — revenue (¥ million) | 662 | 240 | +175.9% |
| Investment management — segment profit (¥ million) | 595 | 186 | +219.0% |
| Total assets (¥ million) | 20,085 | 18,690 | +7.5% |
| Net assets (¥ million) | 12,430 | 11,233 | +10.7% |
| Equity ratio | 61.9% | 60.1% | +1.8 pt |
| FY3/2027 guidance — revenue (¥ million) | 6,700 | — | −4.7% |
| FY3/2027 guidance — operating profit (¥ million) | 1,100 | — | +15.2% |
| FY3/2027 guidance — ordinary profit (¥ million) | 1,000 | — | +24.4% |
| FY3/2027 guidance — net profit (¥ million) | 700 | — | +10.5% |
| Annual dividend per share (¥) | 4.00 | 4.00 | unchanged |
JapanStockPulse provides informational content only and does not constitute investment advice. Figures are taken from the company's published earnings short report and may be subject to subsequent revision.