Bigger clients and bigger projects
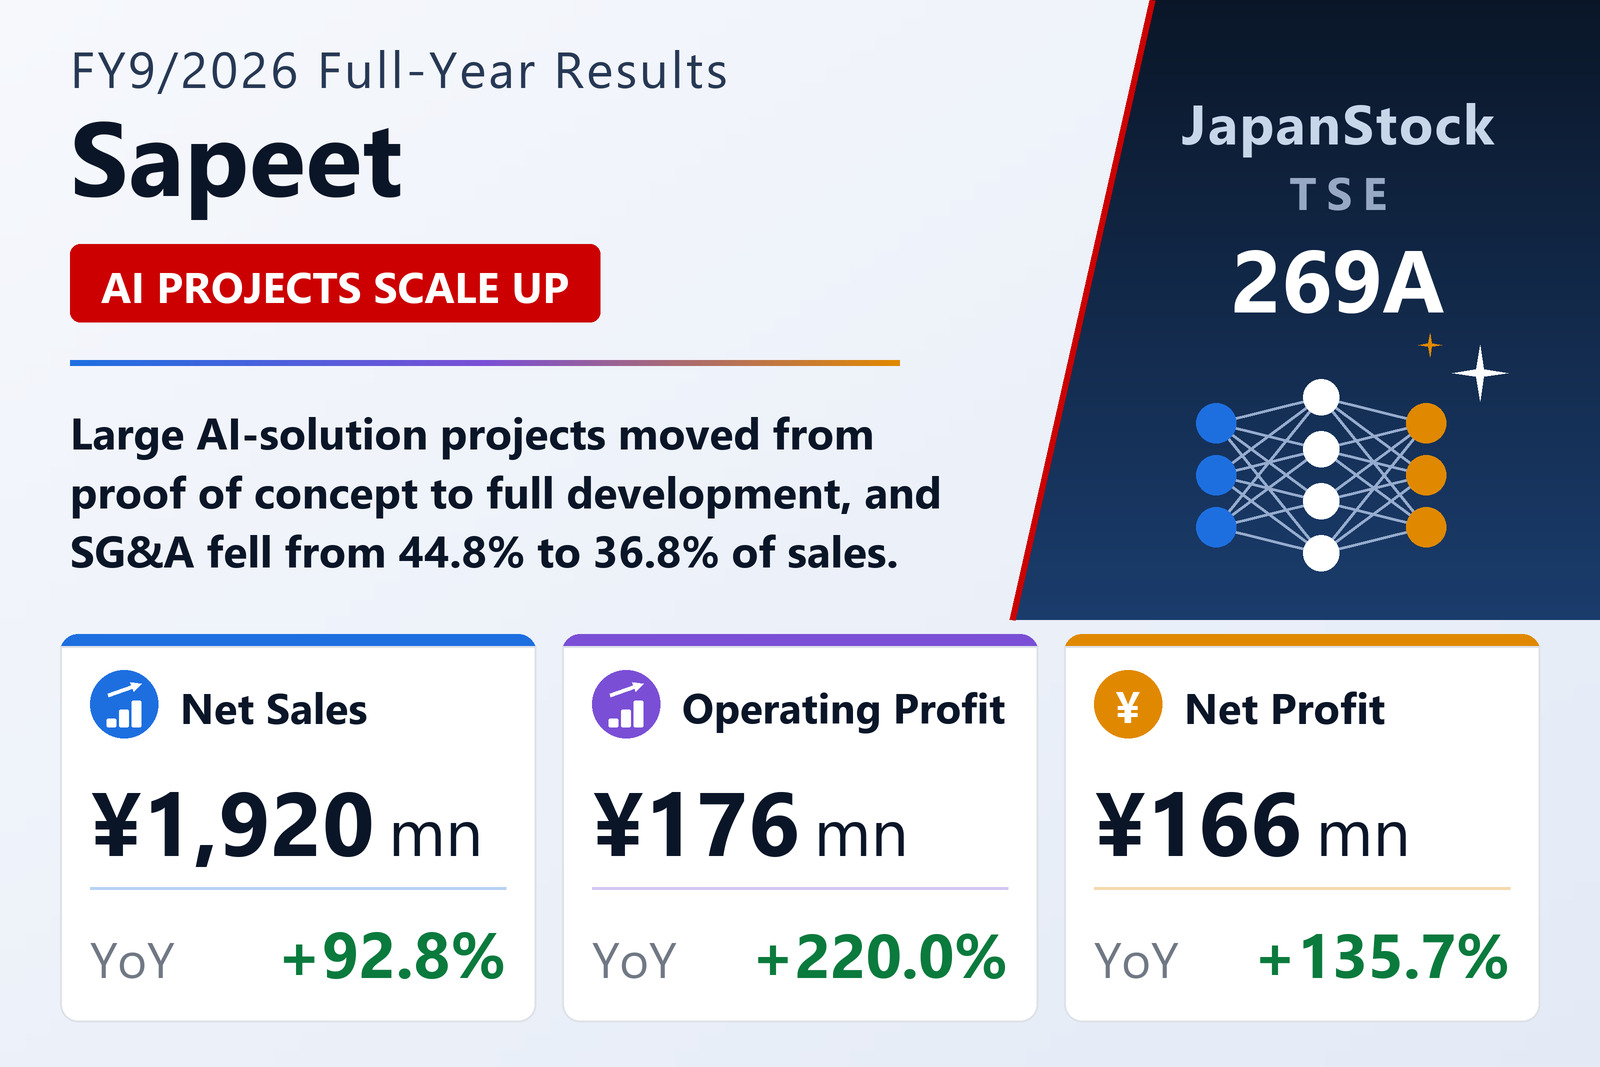
Sapeet Co., Ltd. (TSE: 269A), a Tokyo-based developer of AI solutions and AI products that it groups under a single Expert AI segment, reported non-consolidated results for FY9/2026, October 1, 2025 to September 30, 2026, on November 12, 2026 under Japanese GAAP. Net sales rose 92.8% to ¥1,920 million, operating profit rose 220.0% to ¥176 million, ordinary profit rose 292.9% to ¥177 million and net profit rose 135.7% to ¥166 million, or ¥103.17 per share. The company said its AI-solution business grew fastest, helped by its focus on winning large clients and large projects and by more existing projects advancing from proof of concept to full development, while its AI products — ShiseiKarte, MultiKarte and the SaaS role-play trainer SAPI Roleplay — added accounts.
Cost of sales rose 109.4% to ¥1,037 million on higher labour and outsourcing costs, which Sapeet partly attributed to strategic proposals on projects it expects to grow and on AI agents, so gross profit rose a slower 76.3% to ¥883 million. Selling, general and administrative expenses rose 58.5% to ¥706 million as it hired, increased research and development and enlarged its office, but they fell from 44.8% to 36.8% of sales, lifting the operating margin to 9.2% from 5.5%. A ¥7 million write-off of software with low expected use was booked as an extraordinary loss. Total assets rose to ¥823 million, while ¥119 million spent on buying back shares helped pull the equity ratio down to 70.4% from 83.4%.
Faster investment planned for FY9/2027
For FY9/2027 Sapeet forecasts net sales of ¥2,700 million (+40.6%), operating profit of ¥217 million (+22.9%) and ordinary profit of ¥218 million (+22.6%). It expects demand for AI solutions to stay strong and SAPI Roleplay to grow into a product alongside ShiseiKarte and MultiKarte, and said it will accelerate investment to build a base for medium- to long-term growth after beating its own expectations in FY9/2026. Net profit is forecast to fall 9.8% to ¥150 million because its tax burden rises once tax-loss carryforwards are used up. It plans no dividend.
| Metric | FY9/2026 | FY9/2025 | Change |
|---|---|---|---|
| Net sales (¥ million) | 1,920 | 996 | +92.8% |
| Operating profit (¥ million) | 176 | 55 | +220.0% |
| Ordinary profit (¥ million) | 177 | 45 | +292.9% |
| Net profit (¥ million) | 166 | 70 | +135.7% |
| EPS (¥) | 103.17 | 45.25 | +128.0% |
| Operating margin | 9.2% | 5.5% | +3.7 pt |
| Total assets (¥ million) | 823 | 597 | +37.7% |
| Net assets (¥ million) | 579 | 498 | +16.2% |
| Equity ratio | 70.4% | 83.4% | −13.0 pt |
| FY9/2027 guidance — revenue (¥ million) | 2,700 | — | +40.6% |
| FY9/2027 guidance — operating profit (¥ million) | 217 | — | +22.9% |
| FY9/2027 guidance — ordinary profit (¥ million) | 218 | — | +22.6% |
| FY9/2027 guidance — net profit (¥ million) | 150 | — | −9.8% |
| Annual dividend per share (¥) | 0.00 | 0.00 | unchanged |
JapanStockPulse provides informational content only and does not constitute investment advice. Figures are taken from the company's published earnings short report and may be subject to subsequent revision.