Domestic mushrooms carry the half
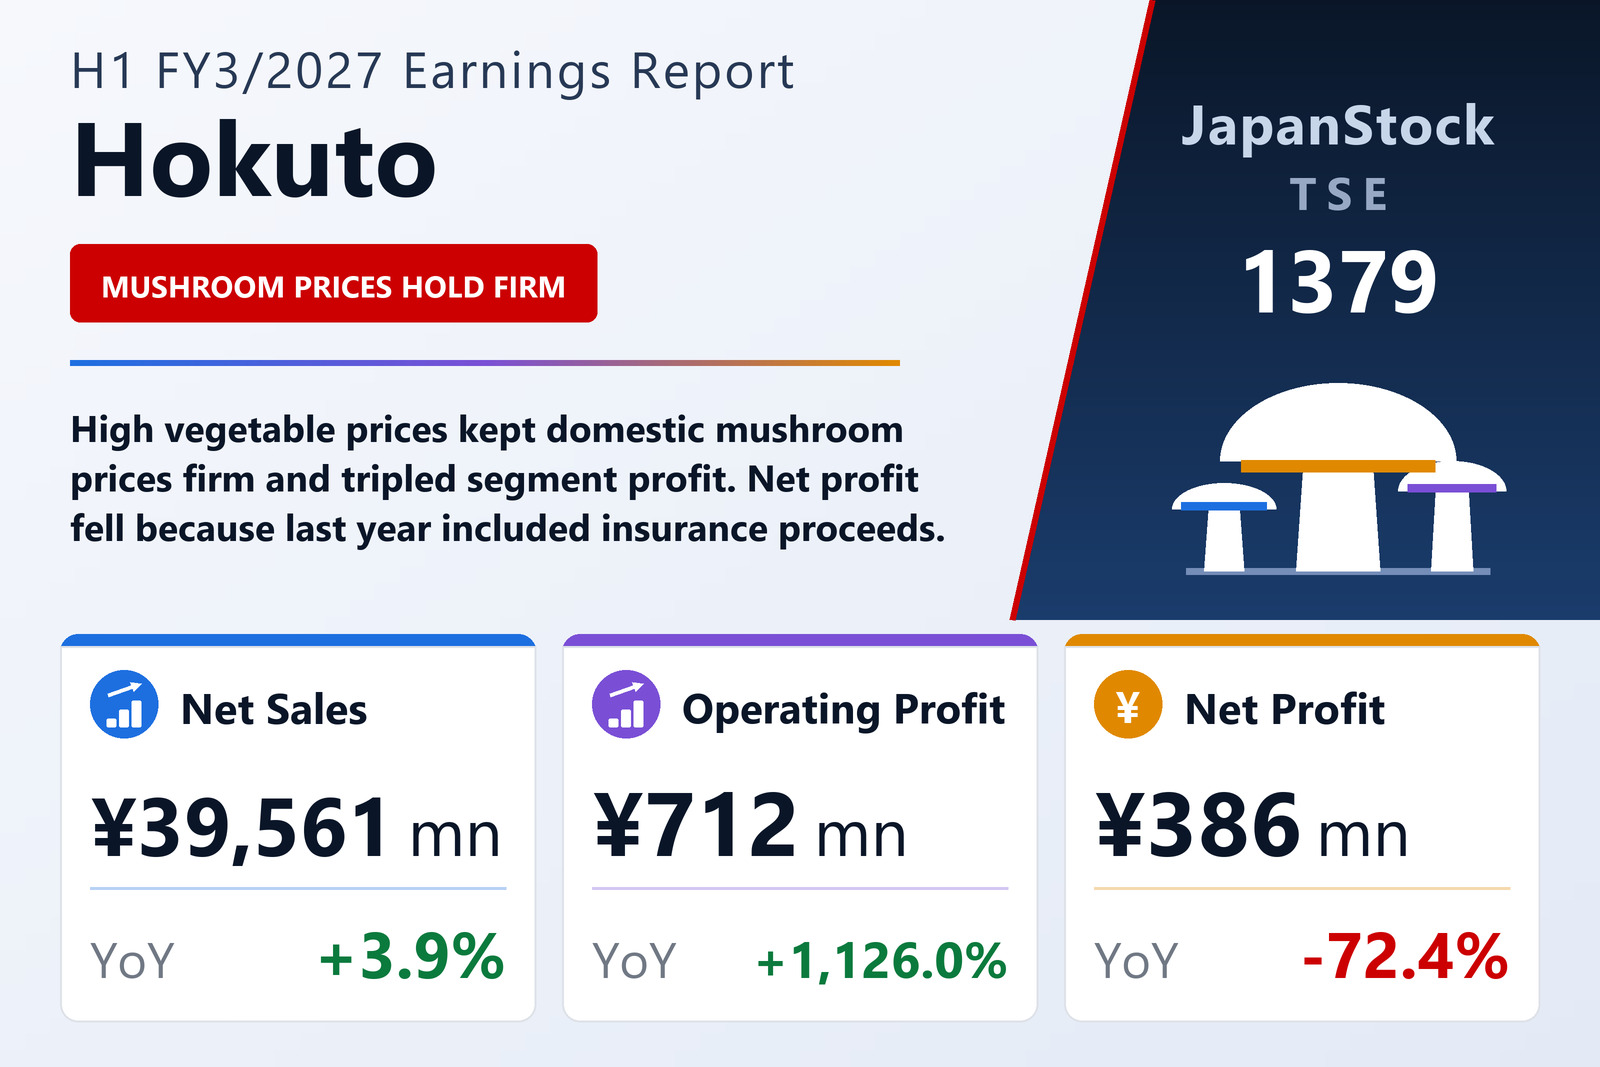
Hokuto Corporation (TSE: 1379), which grows bunashimeji, eryngii and maitake mushrooms in Japan, the United States, Taiwan and Malaysia, reported consolidated results for the first half of FY3/2027, April 1 to September 30, 2026, on November 13, 2026 under Japanese GAAP. Net sales rose 3.9% to ¥39,561 million, operating profit rose to ¥712 million from ¥58 million and ordinary profit rose 168.6% to ¥827 million. Output of the main mushrooms dipped: bunashimeji, including Bunapi, 21,472 tonnes (−0.7%), eryngii 7,779 tonnes (−4.9%) and maitake 7,053 tonnes (−2.6%).
The domestic mushroom business grew sales 4.9% to ¥24,405 million and more than tripled segment profit to ¥1,090 million: with vegetable prices high after unseasonable weather, new accounts, regional sales strategies, social-media marketing and in-store promotions kept mushroom prices firm, while the company tightened energy management as power costs rose. Overseas sales fell 3.4% to ¥3,695 million and segment profit fell 80.0% to ¥89 million, as higher petrol prices dampened U.S. consumption, although sales to the Kroger group, which began in the first quarter, grew. Processed foods rose 3.6% to ¥3,975 million with profit up 19.9% to ¥210 million, and chemical products, which raised prices on higher naphtha costs, rose 4.8% to ¥7,484 million with profit up 67.4% to ¥441 million.
Net profit falls; dividend to rise
Net profit attributable to owners fell 72.4% to ¥386 million, or ¥12.34 per share, because the year-earlier half included ¥1,896 million of insurance proceeds. Total assets rose to ¥117,026 million, with investment securities and long-term borrowings both higher, and the equity ratio was 55.5%. Hokuto kept its FY3/2027 forecast of net sales of ¥88,100 million (+2.5%), operating profit of ¥7,260 million (+3.3%), ordinary profit of ¥7,650 million (−6.6%) and net profit of ¥5,250 million (−25.1%), and plans an annual dividend of ¥62.00, up from ¥55.00, including an interim ¥10.00.
| Metric | H1 FY3/2027 | H1 FY3/2026 | Change |
|---|---|---|---|
| Net sales (¥ million) | 39,561 | 38,080 | +3.9% |
| Operating profit (¥ million) | 712 | 58 | +1,126.0% |
| Ordinary profit (¥ million) | 827 | 307 | +168.6% |
| Net profit attrib. to owners of parent (¥ million) | 386 | 1,401 | −72.4% |
| EPS (¥) | 12.34 | 44.79 | −72.4% |
| Domestic Mushrooms — revenue (¥ million) | 24,405 | — | +4.9% |
| Domestic Mushrooms — segment profit (¥ million) | 1,090 | — | +240.2% |
| Overseas Mushrooms — revenue (¥ million) | 3,695 | — | −3.4% |
| Overseas Mushrooms — segment profit (¥ million) | 89 | — | −80.0% |
| Processed Foods — revenue (¥ million) | 3,975 | — | +3.6% |
| Processed Foods — segment profit (¥ million) | 210 | — | +19.9% |
| Chemical Products — revenue (¥ million) | 7,484 | — | +4.8% |
| Chemical Products — segment profit (¥ million) | 441 | — | +67.4% |
| Total assets (¥ million) | 117,026 | 113,726 | +2.9% |
| Net assets (¥ million) | 64,953 | 64,924 | 0.0% |
| Equity ratio | 55.5% | 57.1% | −1.6 pt |
| FY3/2027 guidance — revenue (¥ million) | 88,100 | — | +2.5% |
| FY3/2027 guidance — operating profit (¥ million) | 7,260 | — | +3.3% |
| FY3/2027 guidance — ordinary profit (¥ million) | 7,650 | — | −6.6% |
| FY3/2027 guidance — net profit (¥ million) | 5,250 | — | −25.1% |
| Annual dividend per share (¥) | 62.00 | 55.00 | +12.7% |
JapanStockPulse provides informational content only and does not constitute investment advice. Figures are taken from the company's published earnings short report and may be subject to subsequent revision.