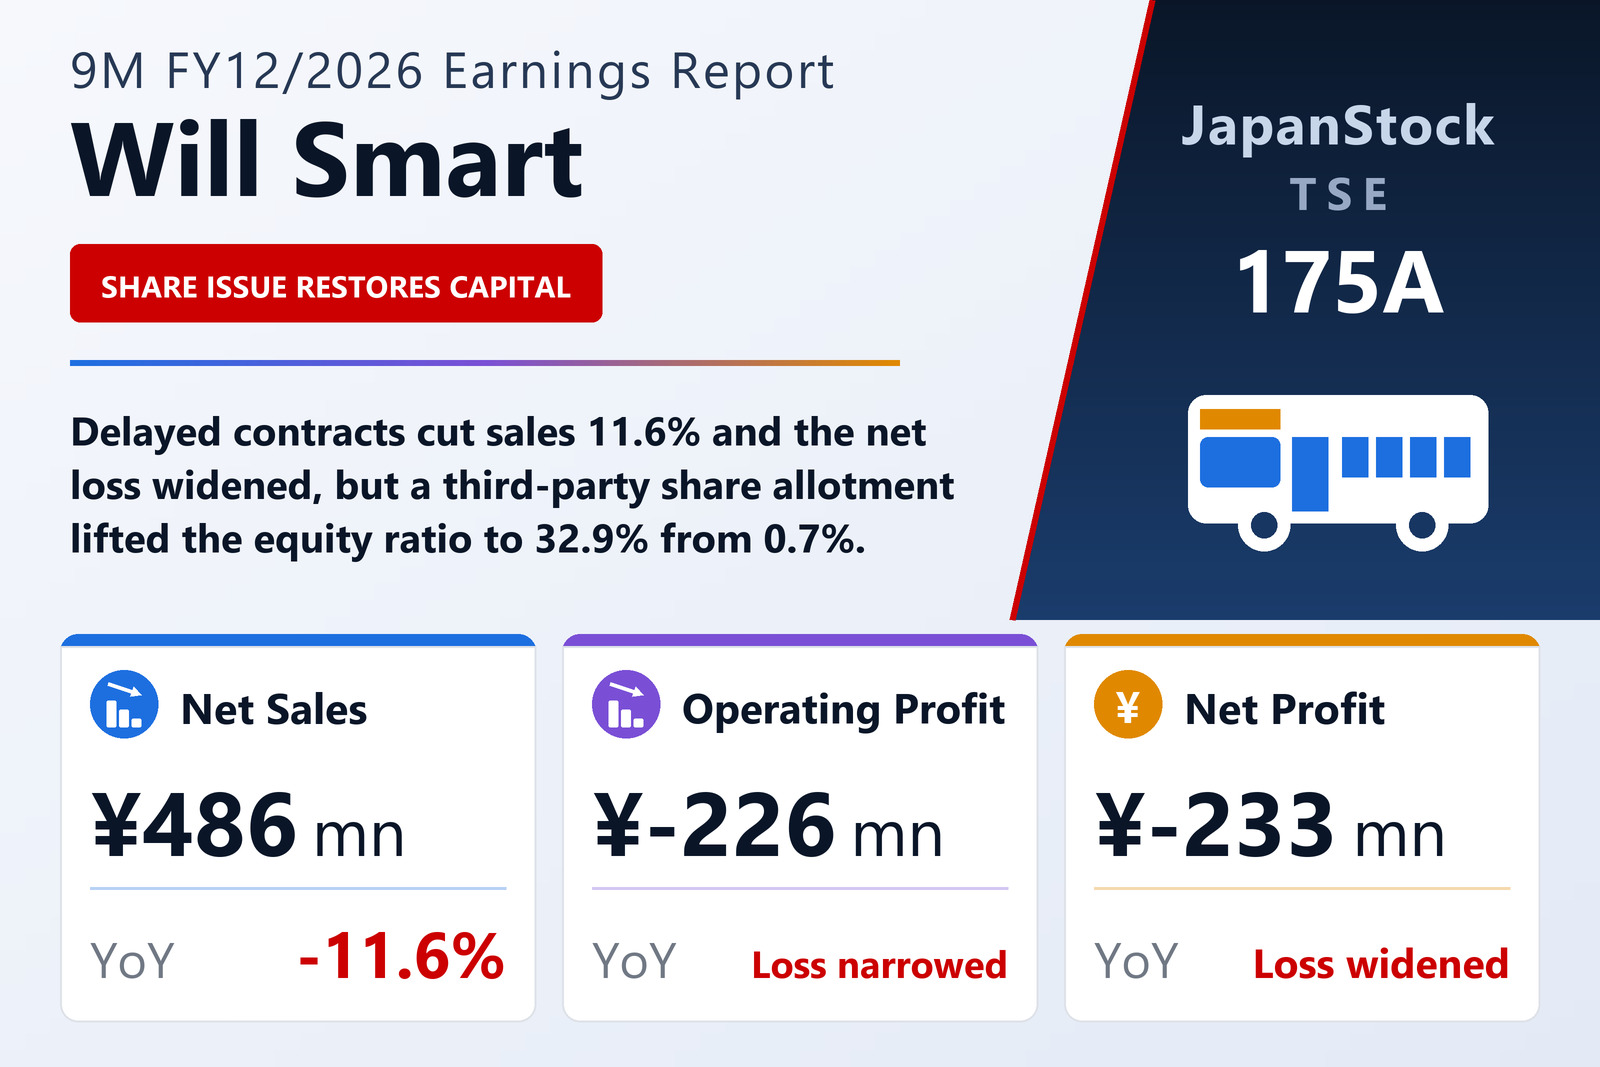
Project timing hits sales
Will Smart Co., Ltd. (TSE: 175A), which builds digital systems for regional public transport and logistics operators, reported non-consolidated results for the first nine months of FY12/2026, January 1 to September 30, 2026, on November 13, 2026 under Japanese GAAP. Two projects led by the company were selected under a Ministry of Land, Infrastructure, Transport and Tourism programme for regional transport DX: a web-based cloud system for bus planning and results aggregation built to the industry's standard specification, and, with WILLER EXPRESS, technology verification of on-board devices and AI for bus operations and safety management. In logistics it continued to sell Will-Fleet, an OBD-II digital tachograph.
Net sales fell 11.6% to ¥486 million as contracts and acceptance on commissioned work were pushed back. Gross profit fell with sales, but lower selling, general and administrative expenses narrowed the operating loss by ¥14 million to ¥226 million. Lower subsidy income and higher interest expense widened the ordinary loss to ¥229 million from ¥219 million, and the net loss widened to ¥233 million from ¥220 million, or ¥130.96 per share. The company reports a single mobility segment.
Capital restored; going-concern note remains
A third-party share allotment of about ¥450 million paid in on June 1, 2026, together with restricted-stock issuance, raised capital and capital reserve by ¥230 million each, ending the negative net worth: net assets were ¥230 million and the equity ratio rose to 32.9% from 0.7%. Cash and deposits rose to ¥358 million. Because operating losses continue, the company still discloses events or conditions that raise substantial doubt about its ability to continue as a going concern, but with that funding it judges that no material uncertainty exists. It kept its FY12/2026 forecast of net sales of ¥1,150 million (+42.8%), operating and ordinary profit of ¥50 million each and net profit of ¥40 million, which assumes fourth-quarter sales of roughly ¥200–280 million from platform services and ¥350–400 million from commissioned development.
| Metric | 9M FY12/2026 | 9M FY12/2025 | Change |
|---|---|---|---|
| Net sales (¥ million) | 486 | 550 | −11.6% |
| Operating profit (¥ million) | −226 | −241 | loss narrowed |
| Ordinary profit (¥ million) | −229 | −219 | loss widened |
| Net profit (¥ million) | −233 | −220 | loss widened |
| EPS (¥) | −130.96 | −150.16 | loss narrowed |
| Total assets (¥ million) | 699 | 436 | +60.3% |
| Net assets (¥ million) | 230 | 3 | n.m. |
| Equity ratio | 32.9% | 0.7% | +32.2 pt |
| FY12/2026 guidance — revenue (¥ million) | 1,150 | — | +42.8% |
| FY12/2026 guidance — operating profit (¥ million) | 50 | — | loss to profit |
| FY12/2026 guidance — ordinary profit (¥ million) | 50 | — | loss to profit |
| FY12/2026 guidance — net profit (¥ million) | 40 | — | loss to profit |
JapanStockPulse provides informational content only and does not constitute investment advice. Figures are taken from the company's published earnings short report and may be subject to subsequent revision.