Pressure-reducing valves at home, a weak yen abroad
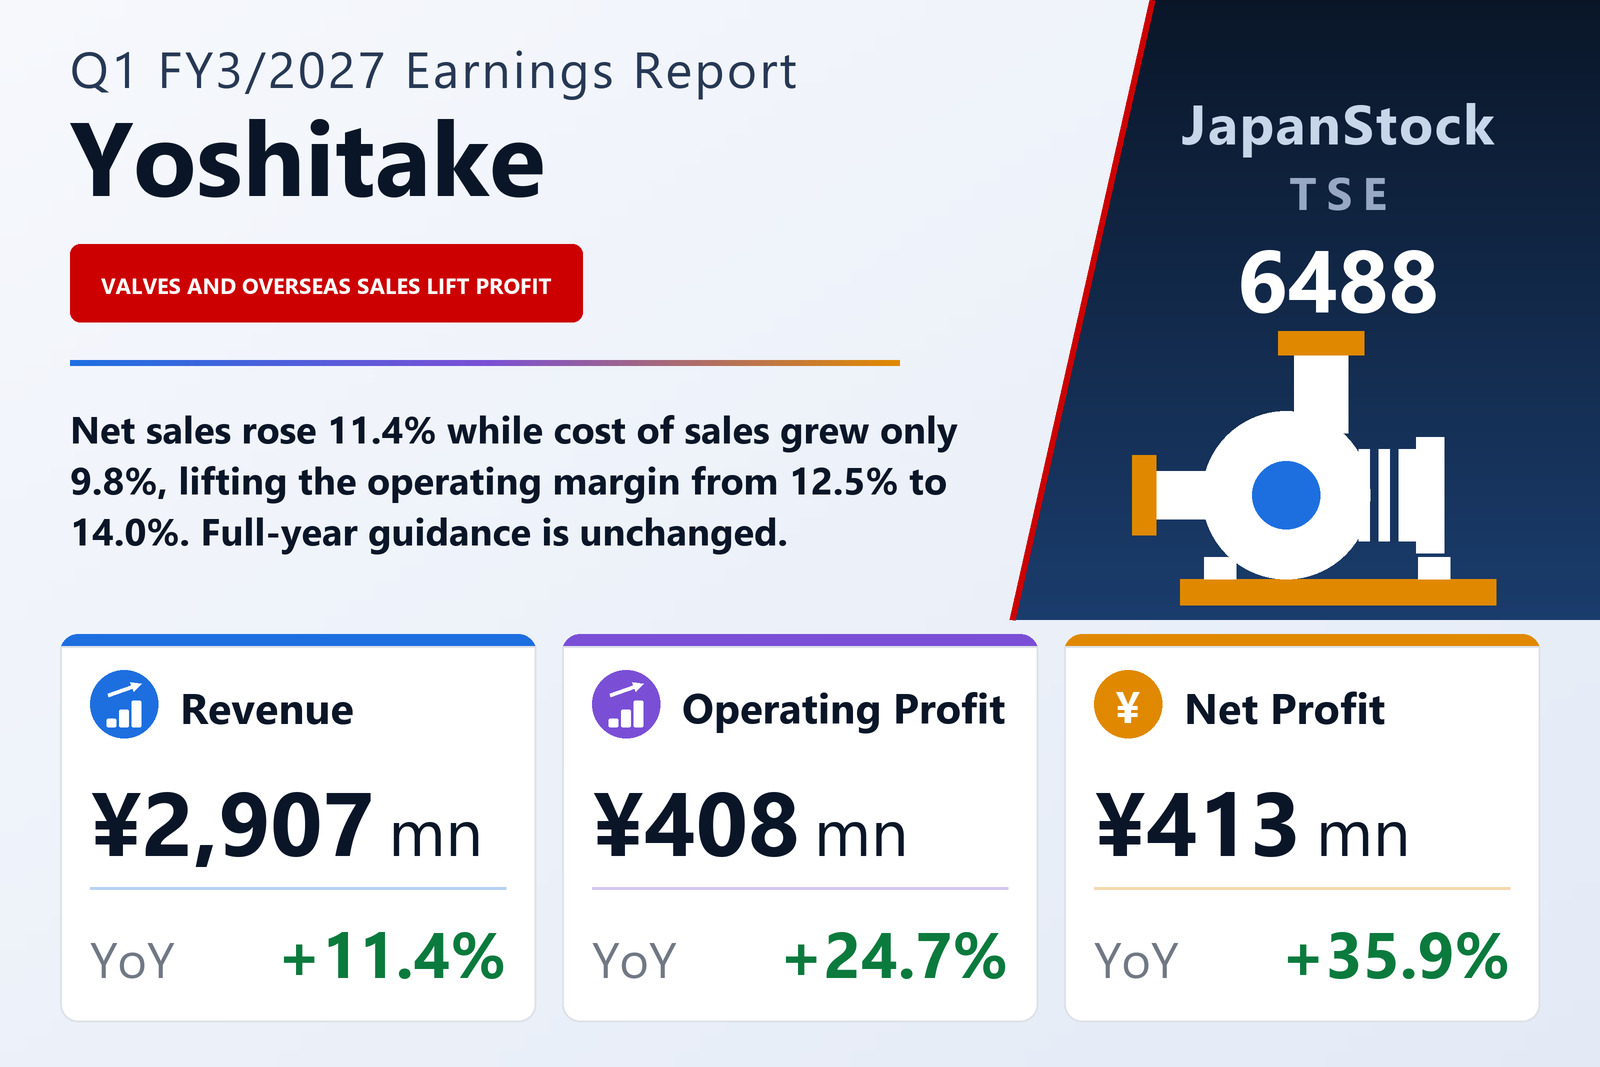
Yoshitake Inc. (TSE: 6488), a maker of fluid-control valves whose main product is the pressure-reducing valve, published consolidated results for the first quarter of FY3/2027, the three months from April 1 to June 30, 2026, on July 31, 2026 under Japanese GAAP. Net sales rose 11.4% to ¥2,907 million, operating profit 24.7% to ¥408 million, ordinary profit 32.5% to ¥569 million and profit attributable to owners of the parent 35.9% to ¥413 million, for earnings of ¥32.48 per share against ¥23.89. The filing lists the shares on the Tokyo Stock Exchange without naming a market segment, and states that the quarterly statements were not reviewed by an auditor.
The company attributes the sales growth to both halves of its customer base. At home, sales of its pressure-reducing valves held firm, and in the factory-equipment market two products did well: a jacket product that the company credits with energy-saving and CO2-reduction effects, and magnet mixers sold to hospitals and to pharmaceutical, food and chemical plants. Domestic sales therefore exceeded the prior year. Overseas sales also rose, helped, the filing says, by the weak yen. It does not split the total between domestic and overseas customers.
Cost of sales grew slower than sales, and SG&A slower still
The margin arithmetic explains why profit outran sales. Cost of sales rose 9.8% to ¥1,749 million against sales growth of 11.4%, so gross profit rose 14.0% to ¥1,158 million and the gross margin widened from 38.9% to 39.8%. Selling, general and administrative expenses rose 8.9% to ¥749 million, slower than both sales and gross profit, which pushed the operating margin from 12.5% to 14.0%. The filing credits the profit improvement to more efficient production, fewer man-hours and thorough cost reduction. Depreciation was ¥137 million against ¥127 million, and goodwill amortisation was an unchanged ¥32 million.
Below the operating line: a currency swing, partly offset
Ordinary profit grew faster again, by 32.5%, and the income statement shows why. A foreign-exchange gain of ¥31 million replaced a foreign-exchange loss of ¥80 million a year earlier, a swing of about ¥112 million. Against that, income from investment distributions fell to ¥1 million from ¥68 million, and equity-method investment income eased to ¥94 million from ¥97 million. Net non-operating income came to ¥160 million against ¥102 million. The management commentary itself does not discuss the non-operating lines.
There were no extraordinary items, so pre-tax profit equalled ordinary profit at ¥569 million. Income taxes rose to ¥156 million from ¥123 million, an effective rate of about 27.6% against 28.8%. Quarterly profit was ¥412 million, and because non-controlling interests bore a small loss, profit attributable to owners of the parent was slightly higher, at ¥413 million. Comprehensive income jumped 689.4% to ¥533 million from ¥67 million, mainly because a year earlier the group's share of equity-method affiliates' other comprehensive income was a loss of ¥228 million, against a gain of ¥59 million this quarter.
Both geographic segments grew, Asia faster on profit
Yoshitake reports two geographic segments. Japan posted sales to external customers of ¥2,107 million, up 12.1%, and segment profit of ¥284 million, up 18.3%. Asia posted external sales of ¥799 million, up 9.6%, and segment profit of ¥119 million, up 24.4%. The filing states no segment percentages; these are computed from its figures. Asia also sold ¥655 million to other group segments, against ¥508 million a year earlier, so its sales including intersegment transfers rose 17.6% to ¥1,455 million. Segment profit totalled ¥404 million, reconciled to the ¥408 million operating profit through intersegment eliminations and an inventory adjustment.
Cash moved into investment securities
Total assets fell by ¥256 million to ¥21,049 million from March 31, 2026. Investment securities rose by ¥927 million, while cash fell by ¥648 million and current securities by ¥586 million. Liabilities fell by ¥340 million to ¥2,484 million, mainly because income taxes payable dropped by ¥487 million, partly offset by a ¥189 million rise in notes and accounts payable and a ¥98 million rise in short-term borrowings. Net assets rose by ¥83 million to ¥18,564 million: dividends of ¥445 million cut retained earnings by ¥32 million, while the foreign-currency translation adjustment rose by ¥111 million. The equity ratio improved from 86.0% to 87.5%, and net assets per share were ¥1,448.38. No quarterly cash-flow statement was prepared.
From this quarter, a consolidated subsidiary moved its fiscal year-end from January 31 to March 31 to match the group, so its results for this quarter cover five months. The filing describes the effect as minor.
Guidance and dividend left unchanged
Full-year FY3/2027 guidance is unchanged from the forecast published on May 15, 2026: net sales of ¥11,080 million (+7.1%), operating profit of ¥1,520 million (+15.1%), ordinary profit of ¥1,930 million (−16.0%) and profit attributable to owners of ¥1,390 million (−6.0%), for earnings of ¥109.30 per share. The first half is guided at net sales of ¥5,424 million and operating profit of ¥786 million. The first quarter delivered 26.2% of guided full-year sales, 26.9% of operating profit, 29.5% of ordinary profit and 29.7% of net profit, and its operating profit is already 51.9% of the first-half target. Guidance has ordinary and net profit falling for the year even as operating profit rises; this filing gives no reason for that.
The dividend forecast was also not revised. Yoshitake pays no interim dividend and forecasts a year-end dividend of ¥36.00 per share against ¥35.00 for FY3/2026.
| Metric | Q1 FY3/2027 | Q1 FY3/2026 | Change |
|---|---|---|---|
| Net sales (¥ million) | 2,907 | 2,610 | +11.4% |
| Gross profit (¥ million) | 1,158 | 1,016 | +14.0% |
| Gross margin | 39.8% | 38.9% | +0.9 pt |
| SG&A expenses (¥ million) | 749 | 688 | +8.9% |
| Operating profit (¥ million) | 408 | 327 | +24.7% |
| Operating margin | 14.0% | 12.5% | +1.5 pt |
| Ordinary profit (¥ million) | 569 | 429 | +32.5% |
| Net profit attrib. to owners of parent (¥ million) | 413 | 303 | +35.9% |
| Comprehensive income (¥ million) | 533 | 67 | +689.4% |
| EPS (¥) | 32.48 | 23.89 | +36.0% |
| Japan — revenue (¥ million) | 2,107 | 1,880 | +12.1% |
| Japan — segment profit (¥ million) | 284 | 240 | +18.3% |
| Asia — revenue (¥ million) | 799 | 729 | +9.6% |
| Asia — segment profit (¥ million) | 119 | 96 | +24.4% |
| Total assets (¥ million) | 21,049 | 21,306 | −1.2% |
| Net assets (¥ million) | 18,564 | 18,481 | +0.5% |
| Equity ratio | 87.5% | 86.0% | +1.5 pt |
| FY3/2027 guidance — revenue (¥ million) | 11,080 | — | +7.1% |
| FY3/2027 guidance — operating profit (¥ million) | 1,520 | — | +15.1% |
| FY3/2027 guidance — ordinary profit (¥ million) | 1,930 | — | −16.0% |
| FY3/2027 guidance — net profit (¥ million) | 1,390 | — | −6.0% |
| Annual dividend per share (¥) | 36.00 | 35.00 | +2.9% |
JapanStockPulse provides informational content only and does not constitute investment advice. Figures are taken from the company's published earnings short report and may be subject to subsequent revision.