Sales slip as suction products soften
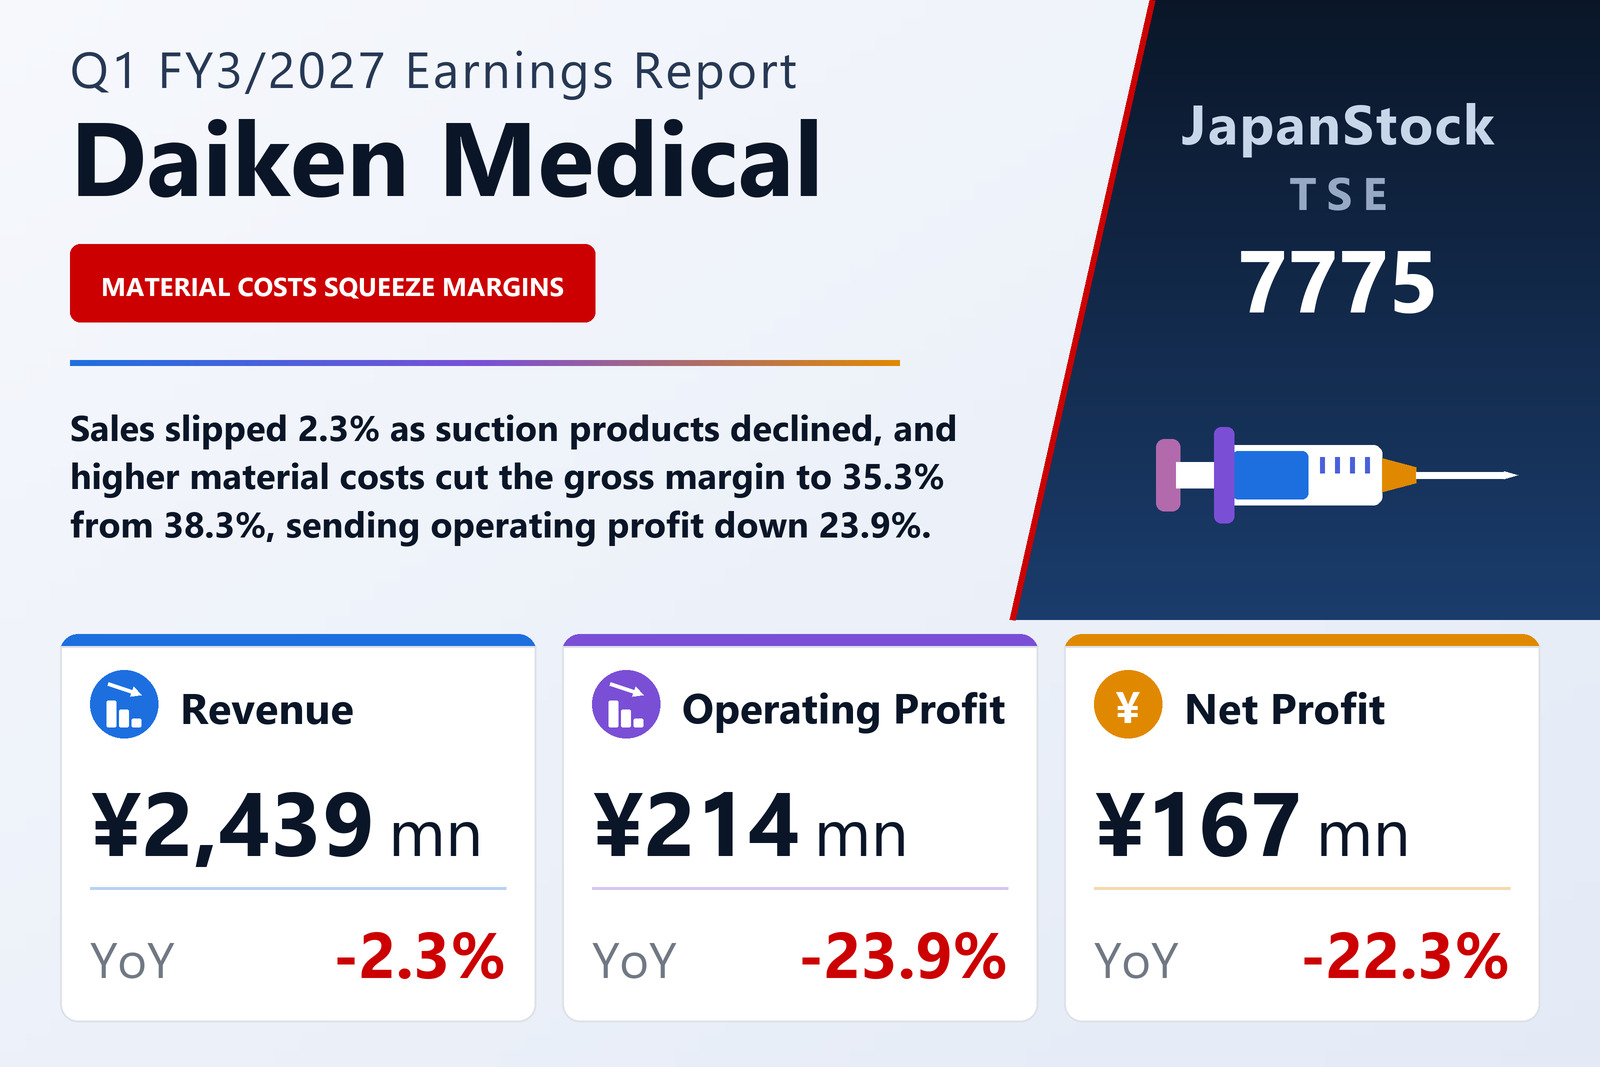
Daiken Medical Co., Ltd. (TSE: 7775), a maker of medical devices, published non-consolidated results for the three months from April 1 to June 30, 2026 (Q1 FY3/2027) on July 31, 2026 under Japanese GAAP. Net sales fell 2.3% to ¥2,439 million from ¥2,497 million. The company attributes the decline mainly to lower sales of suction-related products, which outweighed strong sales of its Coodec Amy PCA infusion product. Daiken Medical reports a single segment, the manufacture and sale of medical devices and related activities, so the filing carries no segment breakdown.
It does, however, break sales down by product group. Suction-related products, which account for nearly two-thirds of the total, fell 2.2% to ¥1,578 million, while infusion-related products rose 1.4% to ¥545 million. Electric-pump sales dropped 37.4% to ¥35 million and hand-washing equipment fell 9.0% to ¥127 million; other products rose 2.5% to ¥152 million. The filing gives these figures with year-on-year percentages only, not the prior-year amounts.
Higher material costs compress the gross margin
Cost of sales rose 2.4% to ¥1,578 million even as sales fell, so gross profit dropped 9.8% to ¥861 million and the gross margin narrowed to 35.3% from 38.3%. The company attributes the lower gross profit mainly to rising material costs. Selling, general and administrative expenses fell 3.9% to ¥647 million, which cushioned but did not offset the gross-profit decline. Operating profit fell 23.9% to ¥214 million, and the operating margin narrowed to 8.8% from 11.3%.
Non-operating income rose to ¥4.5 million from ¥3.0 million, helped by a ¥2.1 million compensation receipt, but interest expense roughly doubled to ¥5.7 million from ¥2.8 million, and ordinary profit fell 24.4% to ¥213 million. The filing does not explain the higher interest charge. Extraordinary items were negligible. Income taxes fell to ¥45.9 million from ¥66.6 million, leaving net profit down 22.3% at ¥167 million, or ¥5.83 per share against ¥7.50.
Production rises and inventory builds
Production, measured at manufacturing cost, rose 4.5% to ¥1,690 million, led by infusion-related output, up 16.2% to ¥463 million, while suction-related output rose 1.9% to ¥1,066 million. With production up and sales down, finished-product inventory increased by ¥172 million over the quarter to ¥1,235 million. The company produces to forecast rather than to order, so it reports no order figures.
Balance sheet
Total assets fell 2.6% from the March year-end to ¥11,076 million. Cash and deposits declined by ¥342 million to ¥2,435 million and trade notes and accounts receivable by ¥132 million. Current liabilities fell ¥57 million to ¥2,664 million, as lower accounts payable-other (down ¥121 million) and income taxes payable (down ¥114 million) outweighed higher accrued expenses (up ¥89 million). Non-current liabilities fell ¥83 million to ¥783 million, mainly because long-term borrowings were reduced by ¥82 million.
Net assets fell ¥148 million to ¥7,628 million, as ¥316 million of dividends paid exceeded the quarter's ¥167 million profit, but the equity ratio edged up to 68.6% from 68.2% because total assets shrank faster. The company did not prepare a quarterly cash-flow statement; depreciation for the quarter was ¥69 million against ¥62 million a year earlier.
Guidance and dividend unchanged
Daiken Medical said first-quarter results were broadly in line with its plan and left unchanged the forecasts published on May 15, 2026. For the year to March 2027 it expects net sales of ¥10,500 million (+2.0%), operating profit of ¥840 million (−34.3%), ordinary profit of ¥825 million (−35.3%) and net profit of ¥590 million (−36.1%), or ¥20.54 per share. For the first half it guides to net sales of ¥5,150 million (+1.8%) and operating profit of ¥400 million (−40.8%). The first quarter delivered 23.2% of the full-year sales forecast and 25.5% of the operating-profit forecast.
The annual dividend forecast stays at ¥20.00 per share, made up of ¥9.00 at the interim and ¥11.00 at the year end, the same as in FY3/2026.
| Metric | Q1 FY3/2027 | Q1 FY3/2026 | Change |
|---|---|---|---|
| Net sales (¥ million) | 2,439 | 2,497 | −2.3% |
| Cost of sales (¥ million) | 1,578 | 1,541 | +2.4% |
| Gross profit (¥ million) | 861 | 955 | −9.8% |
| Gross margin | 35.3% | 38.3% | −2.9 pt |
| SG&A expenses (¥ million) | 647 | 673 | −3.9% |
| Operating profit (¥ million) | 214 | 281 | −23.9% |
| Operating margin | 8.8% | 11.3% | −2.5 pt |
| Ordinary profit (¥ million) | 213 | 282 | −24.4% |
| Pre-tax profit (¥ million) | 213 | 282 | −24.4% |
| Net profit (¥ million) | 167 | 215 | −22.3% |
| EPS (¥) | 5.83 | 7.50 | −22.3% |
| Sales: suction-related products (¥ million) | 1,578 | — | −2.2% |
| Sales: infusion-related products (¥ million) | 545 | — | +1.4% |
| Sales: electric pumps (¥ million) | 35 | — | −37.4% |
| Sales: hand-washing equipment (¥ million) | 127 | — | −9.0% |
| Sales: other products (¥ million) | 152 | — | +2.5% |
| Total assets (¥ million) | 11,076 | 11,366 | −2.6% |
| Cash and deposits (¥ million) | 2,435 | 2,778 | −12.3% |
| Finished products inventory (¥ million) | 1,235 | 1,062 | +16.2% |
| Net assets (¥ million) | 7,628 | 7,777 | −1.9% |
| Equity ratio | 68.6% | 68.2% | +0.4 pt |
| FY3/2027 guidance — revenue (¥ million) | 10,500 | — | +2.0% |
| FY3/2027 guidance — operating profit (¥ million) | 840 | — | −34.3% |
| FY3/2027 guidance — ordinary profit (¥ million) | 825 | — | −35.3% |
| FY3/2027 guidance — net profit (¥ million) | 590 | — | −36.1% |
| FY3/2027 guidance — EPS (¥) | 20.54 | — | — |
| Annual dividend per share (¥) | 20.00 | 20.00 | unchanged |
JapanStockPulse provides informational content only and does not constitute investment advice. Figures are taken from the company's published earnings short report and may be subject to subsequent revision.