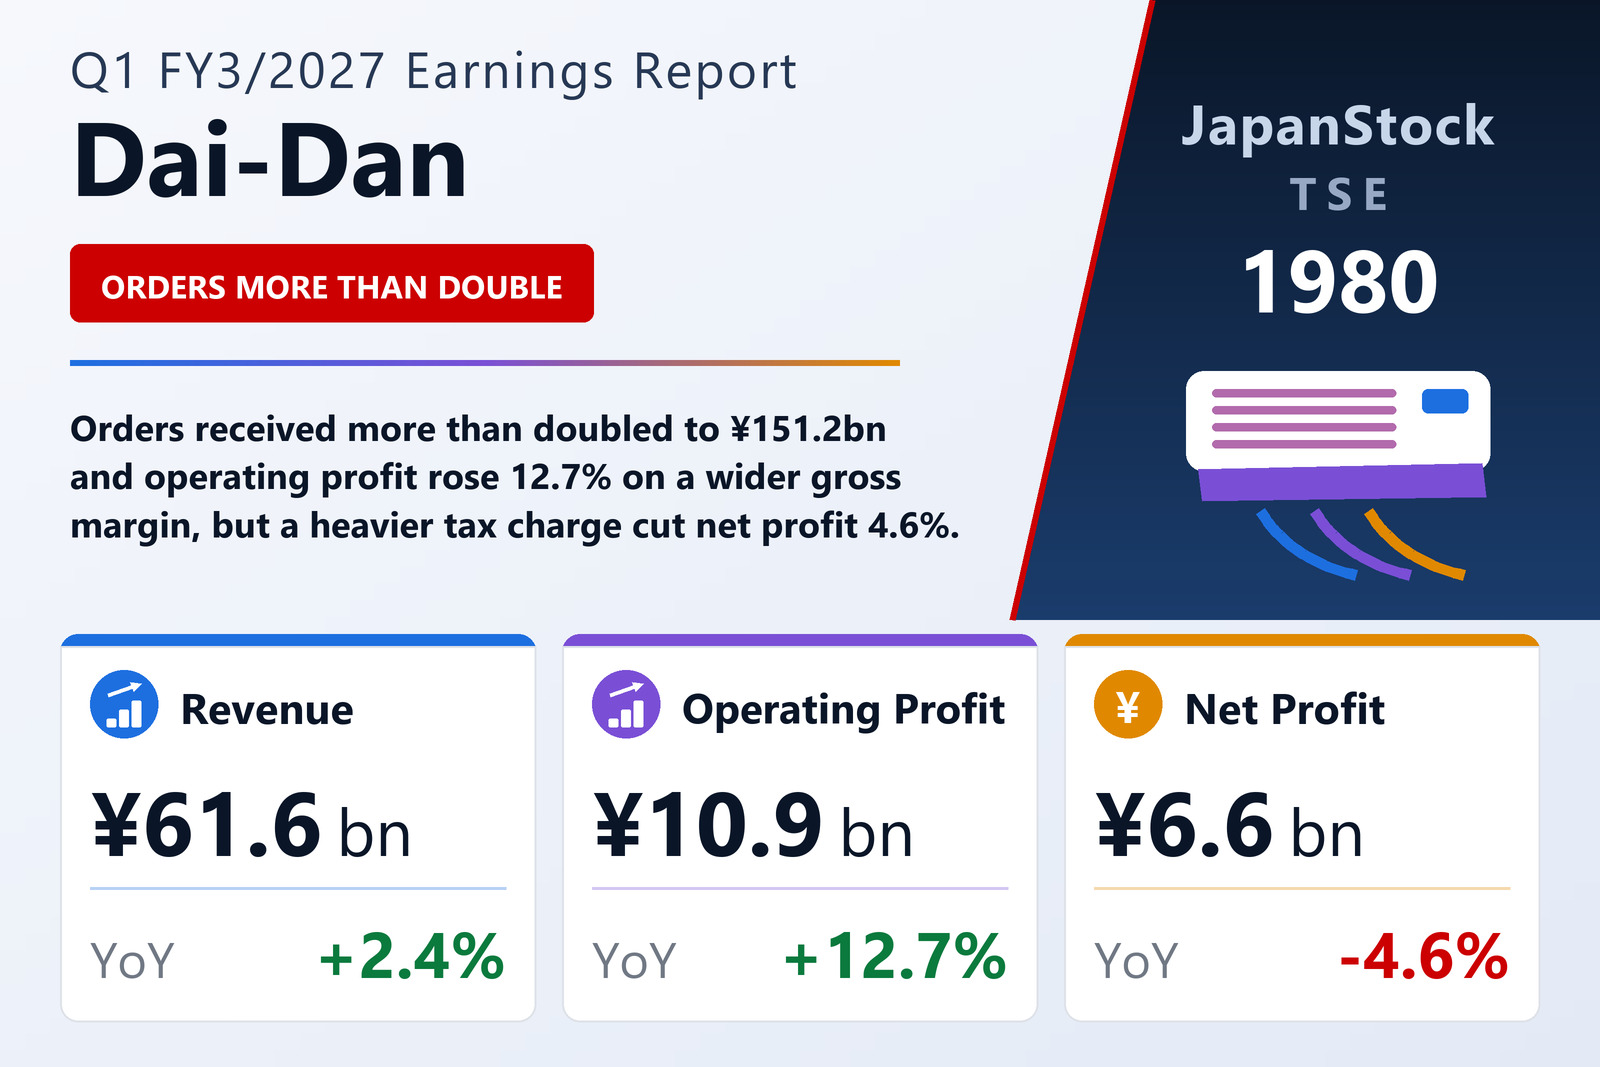
Orders more than doubled while revenue barely moved
Dai-Dan Co., Ltd. (TSE: 1980), the Osaka-based building-services contractor whose single reported business is equipment installation works — air-conditioning and plumbing, and electrical — published consolidated first-quarter results for the three months from April 1 to June 30, 2026 on August 5, 2026 under Japanese GAAP. Revenue, which for Dai-Dan is net sales of completed construction contracts, rose 2.4% to ¥61,601 million, operating profit 12.7% to ¥10,932 million and ordinary profit 12.2% to ¥11,292 million, while profit attributable to owners of the parent fell 4.6% to ¥6,571 million, or ¥50.79 per share against ¥53.51. The quarterly statements were reviewed by the company's auditor on a voluntary basis.
The quarter's defining number sits in the order book rather than the income statement. Orders received rose by ¥84,684 million, or 127.4%, to ¥151,176 million — already 42.0% of the ¥360,000 million the company expects to book in the whole of FY3/2027. Both departments contributed: air-conditioning and plumbing orders rose 111.7% to ¥119,444 million and electrical orders 215.0% to ¥31,731 million, lifting electrical work's share of the total from 15.1% to 21.0%. By type of work, industrial-facility orders rose 126.8% to ¥64,340 million, overseas orders 222.9% to ¥27,651 million and renewal orders 32.2% to ¥40,923 million; the filing notes that these three categories overlap, so they do not add up to the total. It gives no reason for the jump in orders.
The backlog now exceeds a year and a half of guided revenue
With orders running at nearly two and a half times revenue, work carried forward piled up. The order backlog stood at ¥444,848 million at June 30, 2026, up 68.0% from ¥264,744 million a year earlier. Air-conditioning and plumbing backlog rose 51.8% to ¥351,024 million and electrical backlog 179.8% to ¥93,824 million. Overseas backlog more than doubled, up 129.4% to ¥86,954 million, while industrial facilities rose 23.6% to ¥171,497 million and renewals 33.4% to ¥103,542 million. The total is about 1.7 times the ¥265,000 million of revenue guided for the full year.
Revenue rose 2.4%, cost of sales fell 0.9% — the margin did the work
On the income statement the story is margin, not volume. Revenue rose ¥1,454 million, yet the cost of completed construction fell 0.9%, from ¥45,537 million to ¥45,147 million, so gross profit rose 12.6% to ¥16,454 million and the gross margin widened from 24.3% to 26.7%. The filing attributes the gross-profit gain to higher revenue; the arithmetic shows that most of it came from the lower cost ratio, which the filing does not explain. Selling, general and administrative expenses rose 12.6% to ¥5,522 million, as fast as gross profit, so operating profit grew 12.7% and the operating margin moved from 16.1% to 17.7%.
Within completed works the two departments moved in opposite directions: air-conditioning and plumbing revenue rose 4.1% to ¥50,661 million, while electrical revenue fell 4.8% to ¥10,940 million. By type of work, renewal revenue rose 51.7% to ¥25,365 million, lifting its share of completed works from 27.8% to 41.2%; overseas revenue rose 27.9% to ¥6,837 million and industrial-facility revenue fell 4.3% to ¥32,757 million. The filing does not connect that shift in mix to the margin.
Below operating profit, taxes took the gain back
Non-operating items barely moved: income of ¥427 million against ¥424 million, including dividends of ¥147 million, insurance receipts of ¥150 million and a foreign-exchange gain of ¥82 million, and expenses of ¥66 million against ¥61 million. Ordinary profit therefore rose 12.2%, in step with operating profit, and with negligible extraordinary items pre-tax profit was ¥11,296 million, also up 12.2%. Income taxes, however, rose 49.3% to ¥4,686 million — current taxes of ¥2,178 million against ¥1,415 million and deferred-tax adjustments of ¥2,507 million against ¥1,722 million — lifting the tax charge from 31.2% to 41.5% of pre-tax profit. Profit for the period fell 4.6% to ¥6,610 million and, after ¥38 million attributable to non-controlling interests, profit attributable to owners was ¥6,571 million. The filing presents the decline only as the result of those tax lines and gives no reason for the heavier charge.
Earnings per share fell 5.1%, slightly more than net profit, because average shares outstanding rose to 129,390,433 from 128,670,427. The prior-year figure is restated for the three-for-one share split of January 1, 2026. Comprehensive income rose 14.3% to ¥7,136 million, as other comprehensive income swung to +¥526 million from −¥684 million, led by a ¥556 million gain on the valuation of securities.
Receivables collected, advances received, a smaller balance sheet
Total assets fell 6.2% to ¥217,728 million from ¥232,074 million at March 31, 2026, chiefly because notes and accounts receivable on completed contracts fell ¥16,834 million, or 21.5%. Liabilities fell faster, by 14.4% to ¥84,940 million: accounts payable for construction dropped 25.3%, income taxes payable fell from ¥8,196 million to ¥2,419 million and other current liabilities from ¥25,368 million to ¥4,584 million, while advances received on uncompleted contracts rose from ¥10,646 million to ¥18,790 million. Net assets were flat at ¥132,787 million, down 0.1%, as retained earnings slipped ¥719 million despite the quarter's profit; the filing does not itemise the deductions. With assets shrinking and equity unchanged, the equity ratio rose from 56.2% to 59.9%. Cash and deposits were ¥82,576 million against total borrowings of ¥3,343 million. No cash-flow statement was prepared for the quarter; depreciation was ¥442 million against ¥328 million.
Guidance unchanged, and the dividend is set to rise to ¥85
Dai-Dan left unchanged the FY3/2027 guidance it published on May 13, 2026: revenue of ¥265,000 million (+3.4%), operating profit of ¥36,000 million (+4.4%), ordinary profit of ¥36,500 million (+2.0%) and profit attributable to owners of ¥27,300 million (+2.0%), or ¥211.42 per share, on orders of ¥360,000 million. The first quarter delivered 23.2% of guided revenue, 30.4% of guided operating profit and 24.1% of guided net profit. The non-consolidated forecast, also unchanged, calls for revenue of ¥240,000 million (+4.6%) and net profit of ¥27,000 million (+2.7%) on orders of ¥325,000 million.
The dividend forecast is unchanged at ¥42.00 at the interim and ¥43.00 at the year-end, ¥85.00 for the year. Because of the share split, the filing prints FY3/2026's dividend as ¥82.00 before the split at the interim and ¥56.00 after it at the year-end; on a split-adjusted basis it gives ¥27.33 and ¥56.00, a total of ¥83.33, so the forecast is 2.0% higher. At the guided ¥211.42 of earnings per share, ¥85.00 is a payout of about 40%.
| Metric | Q1 FY3/2027 | Q1 FY3/2026 | Change |
|---|---|---|---|
| Orders received (¥ million) | 151,176 | 66,492 | +127.4% |
| Revenue (¥ million) | 61,601 | 60,147 | +2.4% |
| Gross profit (¥ million) | 16,454 | 14,610 | +12.6% |
| Gross margin | 26.7% | 24.3% | +2.4 pt |
| SG&A expenses (¥ million) | 5,522 | 4,906 | +12.6% |
| Operating profit (¥ million) | 10,932 | 9,703 | +12.7% |
| Operating margin | 17.7% | 16.1% | +1.6 pt |
| Ordinary profit (¥ million) | 11,292 | 10,066 | +12.2% |
| Pre-tax profit (¥ million) | 11,296 | 10,069 | +12.2% |
| Income taxes (¥ million) | 4,686 | 3,138 | +49.3% |
| Net profit attrib. to owners of parent (¥ million) | 6,571 | 6,885 | −4.6% |
| Comprehensive income (¥ million) | 7,136 | 6,246 | +14.3% |
| EPS (¥) | 50.79 | 53.51 | −5.1% |
| Air-conditioning & plumbing works — orders received (¥ million) | 119,444 | 56,419 | +111.7% |
| Air-conditioning & plumbing works — revenue (¥ million) | 50,661 | 48,649 | +4.1% |
| Air-conditioning & plumbing works — order backlog (¥ million) | 351,024 | 231,206 | +51.8% |
| Electrical works — orders received (¥ million) | 31,731 | 10,072 | +215.0% |
| Electrical works — revenue (¥ million) | 10,940 | 11,497 | −4.8% |
| Electrical works — order backlog (¥ million) | 93,824 | 33,538 | +179.8% |
| Order backlog (¥ million) | 444,848 | 264,744 | +68.0% |
| Total assets (¥ million) | 217,728 | 232,074 | −6.2% |
| Net assets (¥ million) | 132,787 | 132,879 | −0.1% |
| Equity ratio | 59.9% | 56.2% | +3.7 pt |
| FY3/2027 guidance — orders received (¥ million) | 360,000 | — | — |
| FY3/2027 guidance — revenue (¥ million) | 265,000 | — | +3.4% |
| FY3/2027 guidance — operating profit (¥ million) | 36,000 | — | +4.4% |
| FY3/2027 guidance — ordinary profit (¥ million) | 36,500 | — | +2.0% |
| FY3/2027 guidance — net profit (¥ million) | 27,300 | — | +2.0% |
| FY3/2027 guidance — EPS (¥) | 211.42 | — | — |
| Annual dividend per share (¥) | 85.00 | 83.33 | +2.0% |
JapanStockPulse provides informational content only and does not constitute investment advice. Figures are taken from the company's published earnings short report and may be subject to subsequent revision.