Slipped projects land in the first quarter
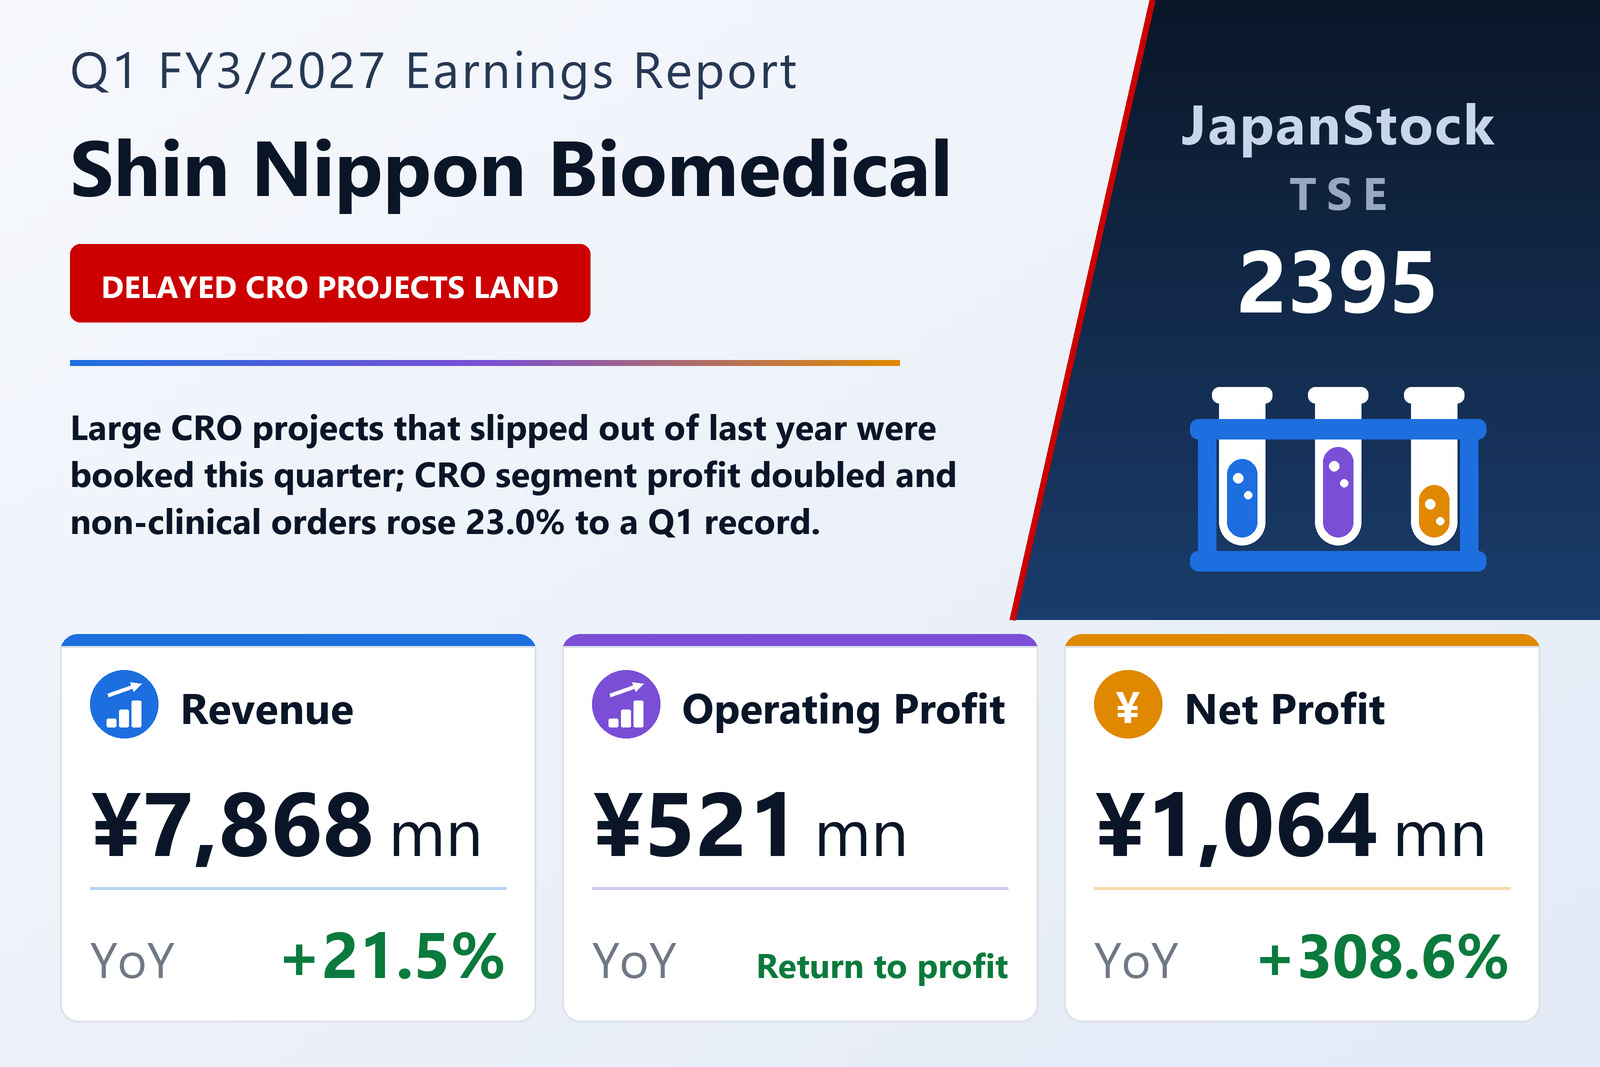
Shin Nippon Biomedical Laboratories, Ltd. (TSE: 2395), a Kagoshima-based contract research organisation whose non-clinical business runs safety and other studies of drug candidates for pharmaceutical clients, published consolidated results for the first quarter of FY3/2027 — the three months from April 1 to June 30, 2026 — under Japanese GAAP on August 5, 2026. Revenue rose 21.5% to ¥7,868 million, which the company describes as a record for a first quarter. Operating profit was ¥521 million, against an operating loss of ¥340 million a year earlier, an improvement of ¥862 million. Ordinary profit rose 177.9% to ¥1,433 million, and profit attributable to owners of the parent 308.6% to ¥1,064 million, or ¥25.55 per share against ¥6.25.
The filing gives one main reason for the turnaround. Several large projects in the CRO business that the company had expected to record as sales during FY3/2026 were completed only in FY3/2027, and most of that slippage was booked in this quarter. The year-on-year comparison therefore includes revenue that the company had originally expected to fall into the previous fiscal year.
Gross margin widened by four points
Cost of sales rose 12.1% to ¥3,821 million, far more slowly than revenue, so gross profit climbed 31.9% to ¥4,047 million and the gross margin widened to 51.44% from 47.38%. Selling, general and administrative expenses rose only 3.4% to ¥3,526 million. Of the ¥862 million improvement in operating profit, higher gross profit added about ¥978 million and higher SG&A absorbed about ¥116 million. The operating margin was 6.63%, against −5.26% a year earlier.
CRO profit doubled and the development unit lost less
The CRO segment, which combines the non-clinical business with the clinical business, lifted revenue 22.0% to ¥7,537 million from ¥6,182 million, also a first-quarter record, and segment profit doubled to ¥1,538 million from ¥769 million. Its operating margin rose to 20.4% from 12.4%. Orders received in the non-clinical business reached a first-quarter record of ¥9,961 million, up 23.0%. The filing attributes the increase mainly to clients in Europe and the United States, whose orders rose 39.8% to ¥4,280 million; overseas orders as a whole rose 68.8% to ¥5,301 million and made up 53.2% of the total against 38.8% a year earlier, while domestic orders fell to ¥4,660 million from ¥4,955 million. The non-clinical order backlog at the end of June was ¥44,060 million, 22.0% higher than a year earlier.
The company credits several long-running initiatives: a supply of non-human primates from its own breeding facilities close to its test sites, which it says has grown in importance as research into new drug modalities intensifies and as the animals have become hard to obtain overseas; the expansion of its bioanalysis capacity; preferred-provider agreements with four Japanese drug makers and preferred-vendor status with one global pharmaceutical group; and a team dedicated to overseas clients. The clinical business is run through a joint venture with PPD, Inc., a U.S.-based clinical CRO in the Thermo Fisher Scientific group, and is accounted for by the equity method; the joint venture contributed equity-method profit of ¥718 million, against ¥700 million.
The Translational Research segment, which develops the company's own drug candidates and technologies, had revenue of ¥59 million against ¥47 million, and its operating loss narrowed to ¥966 million from ¥1,101 million. The filing links part of the improvement to a smaller loss at Satsuma Pharmaceuticals, Inc., the U.S. subsidiary commercialising the nasal migraine treatment Atzumi, whose operating loss was ¥593 million against ¥746 million. Atzumi received marketing approval from the U.S. Food and Drug Administration on April 30, 2025 (U.S. time), and Satsuma is building its sales organisation with a view to a U.S. launch in the second half of 2027.
Medipolis, which runs geothermal and hot-spring power generation and hotels on the company's land in Ibusuki, Kagoshima Prefecture, raised revenue 12.8% to ¥237 million from ¥210 million, but its segment profit fell to ¥16 million from ¥33 million, which the filing attributes chiefly to higher depreciation in the power business. The U.S. Real Estate segment, which leases a multipurpose industrial building on land held by the company's U.S. subsidiary, took in ¥49 million of revenue against ¥43 million, while its loss widened to ¥28 million from ¥23 million. The other businesses, which include construction, earned ¥23 million against ¥3 million, and the reconciling adjustment, mostly corporate costs not allocated to segments, widened to −¥61 million from −¥22 million.
Equity-method income and currency gains lift ordinary profit
Non-operating income rose to ¥1,072 million from ¥915 million. Equity-method investment income was ¥830 million, up 14.5%, most of it from the clinical joint venture, and the foreign-exchange gain grew 42.6% to ¥172 million from ¥120 million. Non-operating expenses rose to ¥161 million from ¥58 million, including interest expense of ¥106 million against ¥57 million. Ordinary profit therefore reached ¥1,433 million, ¥917 million more than a year earlier.
Extraordinary losses shrank to ¥26 million, all of it loss on retirement of non-current assets, from ¥185 million a year earlier, when that item alone came to ¥178 million. Profit before income taxes rose 322.3% to ¥1,408 million. Income taxes were ¥345 million against ¥77 million, or 24.5% of pre-tax profit against 23.1%. Comprehensive income was negative at ¥115 million, compared with negative ¥3,309 million a year earlier, as a ¥1,896 million fall in the valuation difference on available-for-sale securities outweighed a ¥665 million foreign-currency translation gain.
Less cash and debt, more inventories and advances
Total assets fell ¥4,846 million from the March year-end to ¥100,208 million. Cash and deposits dropped ¥4,202 million to ¥14,334 million and investment securities fell ¥2,289 million, while inventories rose ¥2,093 million to ¥17,207 million. On the other side of the balance sheet, advances received rose ¥2,019 million to ¥16,725 million, income taxes payable fell ¥883 million and long-term borrowings fell ¥3,834 million to ¥17,286 million. Short- and long-term borrowings together came to ¥36,856 million, against ¥40,791 million at the year-end, and total liabilities fell ¥3,623 million to ¥57,942 million.
Net assets fell ¥1,223 million to ¥42,265 million: quarterly profit of ¥1,064 million was more than offset by ¥1,248 million of dividend payments and the ¥1,896 million fall in the valuation difference on securities. Because the balance sheet shrank faster, the equity ratio still rose to 41.6% from 41.0%. No quarterly cash-flow statement was prepared; depreciation was ¥760 million against ¥715 million, and capital expenditure in the quarter came to ¥1,127 million.
First-half forecast revised; full-year plan and dividend
Saying results for the quarter had progressed smoothly, the company revised the first-half forecast it published on May 11, 2026, and refers readers to a separate notice issued the same day for details. The first-half figures in the filing call for revenue of ¥17,154 million, up 16.1%, operating profit of ¥1,240 million (no year-on-year change is given), ordinary profit of ¥2,988 million, up 83.6%, and net profit attributable to owners of the parent of ¥1,917 million, up 80.6%, or ¥48.56 per share. The first quarter delivered 45.9% of that revenue and 42.1% of that operating profit.
For the full year FY3/2027 the filing shows revenue of ¥38,000 million, up 16.8%, operating profit of ¥3,000 million, up 13.0%, ordinary profit of ¥6,000 million, up 2.9%, and profit attributable to owners of the parent of ¥3,500 million, down 23.4%, or ¥84.07 per share; this document does not explain the expected fall in net profit. Against those targets the first quarter represents 20.7% of revenue and 17.4% of operating profit. The plan assumes an exchange rate of ¥150 to the U.S. dollar and non-clinical orders of ¥37,800 million for the year. The company expects U.S. reciprocal tariffs to have only a minor effect, since its businesses provide services and export almost no goods to the United States, and it reports no impact so far from the earthquake centred on Kumamoto Prefecture on July 28, 2026.
The dividend forecast is unchanged at ¥50.00 per share for the year — ¥20.00 at the interim and ¥30.00 at the year-end — the same as for FY3/2026.
| Metric | Q1 FY3/2027 | Q1 FY3/2026 | Change |
|---|---|---|---|
| Revenue (¥ million) | 7,868 | 6,477 | +21.5% |
| Gross profit (¥ million) | 4,047 | 3,069 | +31.9% |
| Gross margin | 51.44% | 47.38% | +4.06 pt |
| SG&A expenses (¥ million) | 3,526 | 3,410 | +3.4% |
| Operating profit (¥ million) | 521 | −340 | loss to profit |
| Operating margin | 6.63% | −5.26% | +11.89 pt |
| Equity-method investment income (¥ million) | 830 | 725 | +14.5% |
| Foreign-exchange gain, non-operating (¥ million) | 172 | 120 | +42.6% |
| Ordinary profit (¥ million) | 1,433 | 515 | +177.9% |
| Pre-tax profit (¥ million) | 1,408 | 333 | +322.3% |
| Net profit attrib. to owners of parent (¥ million) | 1,064 | 260 | +308.6% |
| EPS (¥) | 25.55 | 6.25 | +308.8% |
| Comprehensive income (¥ million) | −115 | −3,309 | loss narrowed |
| CRO — revenue (¥ million) | 7,537 | 6,182 | +22.0% |
| CRO — segment profit (¥ million) | 1,538 | 769 | +100.0% |
| Translational Research — revenue (¥ million) | 59 | 47 | +26.9% |
| Translational Research — segment profit (¥ million) | −966 | −1,101 | loss narrowed |
| Medipolis — revenue (¥ million) | 237 | 210 | +12.8% |
| Medipolis — segment profit (¥ million) | 16 | 33 | −51.6% |
| U.S. Real Estate — revenue (¥ million) | 49 | 43 | +13.7% |
| U.S. Real Estate — segment profit (¥ million) | −28 | −23 | loss widened |
| Other — revenue (¥ million) | 114 | 154 | −26.0% |
| Other — segment profit (¥ million) | 23 | 3 | +517.9% |
| Non-clinical orders received (¥ million) | 9,961 | 8,095 | +23.0% |
| Non-clinical orders from overseas clients (¥ million) | 5,301 | 3,140 | +68.8% |
| Non-clinical order backlog, June 30 (vs. June 30, 2025) (¥ million) | 44,060 | 36,120 | +22.0% |
| Cash and deposits (¥ million) | 14,334 | 18,536 | −22.7% |
| Inventories (¥ million) | 17,207 | 15,114 | +13.8% |
| Advances received (¥ million) | 16,725 | 14,705 | +13.7% |
| Long-term borrowings (¥ million) | 17,286 | 21,121 | −18.2% |
| Total assets (¥ million) | 100,208 | 105,055 | −4.6% |
| Net assets (¥ million) | 42,265 | 43,489 | −2.8% |
| Equity ratio | 41.6% | 41.0% | +0.6 pt |
| FY3/2027 guidance — revenue (¥ million) | 38,000 | — | +16.8% |
| FY3/2027 guidance — operating profit (¥ million) | 3,000 | — | +13.0% |
| FY3/2027 guidance — ordinary profit (¥ million) | 6,000 | — | +2.9% |
| FY3/2027 guidance — net profit (¥ million) | 3,500 | — | −23.4% |
| FY3/2027 guidance — EPS (¥) | 84.07 | — | — |
| Annual dividend per share (¥) | 50.00 | 50.00 | unchanged |
JapanStockPulse provides informational content only and does not constitute investment advice. Figures are taken from the company's published earnings short report and may be subject to subsequent revision.