Revenue grew 3.4%, and costs grew a little faster
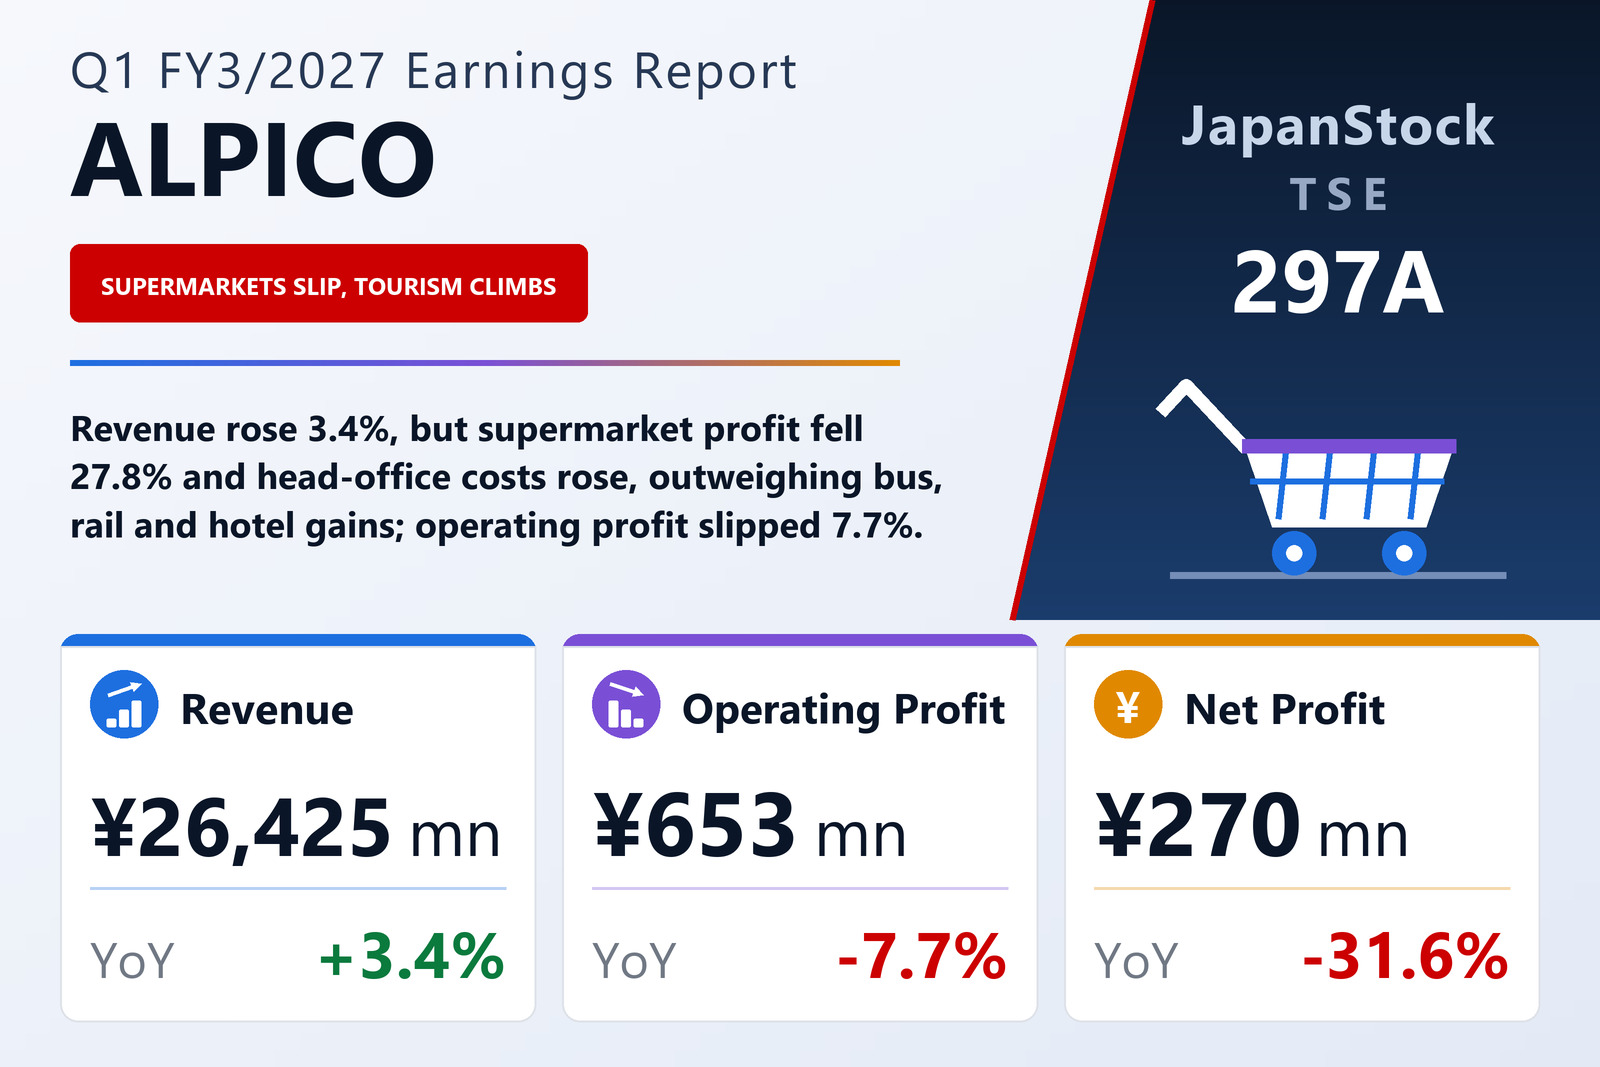
ALPICO HOLDINGS CO., LTD. (TSE: 297A), the Nagano Prefecture group that runs supermarkets, bus, taxi and rail services, and hotels, published consolidated results for the first quarter of the fiscal year ending March 2027 — the three months from April 1 to June 30, 2026 — on August 5, 2026 under Japanese GAAP. Operating revenue rose 3.4% to ¥26,425 million, operating profit fell 7.7% to ¥653 million, ordinary profit fell 14.7% to ¥551 million and profit attributable to owners of the parent fell 31.6% to ¥270 million. Earnings per share were ¥3.92 against ¥5.57, a slightly smaller decline of 29.6%, because the average number of shares outstanding fell from 71,113,251 to 69,019,144. The company's shares are listed on the Tokyo Stock Exchange.
The operating line moved on a narrow spread. Revenue rose by about ¥857 million, while transport operating expenses and cost of sales rose 3.7% to ¥18,503 million and selling, general and administrative expenses also rose 3.7%, to ¥7,268 million. Total operating expenses therefore increased by about ¥912 million — roughly ¥55 million more than the revenue gain — and the operating margin slipped from 2.8% to 2.5%. Depreciation and amortisation, which the filing discloses in place of a quarterly cash-flow statement, rose 14.8% to ¥838 million from ¥730 million.
Segment profit was flat; head-office costs made the difference
The segment note shows that the fall in operating profit did not come from the operating businesses taken together. Combined profit across the five reporting segments was ¥865 million in both periods. What changed was the reconciliation to consolidated operating profit: corporate expenses not attributed to any segment, which the filing describes as mainly general administrative costs, rose from ¥288 million to ¥348 million. That increase of about ¥59 million is larger than the ¥55 million fall in operating profit. The filing does not explain the rise. Inter-segment eliminations added about ¥139 million in both years.
Supermarkets: higher prices, a new store and a thinner margin
Distribution — the Delicia supermarket chain and a smaller business-food format — is by far the largest segment, with operating revenue of ¥19,525 million, up 2.5%, nearly three quarters of group revenue. Its segment profit fell 27.8% to ¥371 million from ¥515 million, and its margin narrowed from about 2.7% to 1.9%. The filing attributes the revenue gain to higher unit prices from price revisions and to the Delicia Meals Kawanakajima store in Nagano City, opened in October 2025. It attributes the profit fall to intense competition, which made it impossible to pass the full rise in purchasing costs on to shelf prices, compounded by higher personnel and other costs.
The segment operates 61 stores: 52 Delicia supermarkets, including four in the prepared-food-focused Delicia Meals format, and nine Gyomu Super and U-Pallet stores that sell mainly bulk goods for businesses. Around them it runs 40 Tokushimaru mobile-supermarket vehicles, 19 online-supermarket bases and one unstaffed self-checkout store.
Buses, rail and hotels carried the gains
Transportation, which the filing notes relies heavily on tourists and is therefore sensitive to inbound travel and the weather, lifted operating revenue 7.6% to ¥3,303 million and segment profit 39.0% to ¥258 million on stronger inbound demand. Bus revenue rose on tourist routes to Kamikochi, Hakuba, Togakushi and other destinations in Nagano Prefecture and on expressway routes within and beyond the prefecture. Taxis gained from tourist demand at Kamikochi, steady city business and a Karuizawa office opened in October 2025, and the railway carried more domestic and overseas tourists.
Tourism lifted operating revenue 5.5% to ¥3,165 million and segment profit 62.3% to ¥188 million, led by the hotel and ryokan business — six properties, five in Matsumoto and one in Suwa — which captured domestic and overseas demand, chiefly for accommodation. The segment's other two businesses shrank: service-area revenue fell because poor weather coincided with busy days, and the travel business declined because its core package tours did not grow despite firm corporate and school-trip demand. Together, transportation and tourism added about ¥145 million of segment profit, almost exactly the ¥143 million that distribution lost.
The two small segments moved in opposite directions. Real estate revenue fell 6.2% to ¥340 million and segment profit 5.1% to ¥35 million, as property sales in the villa-land management business fell short of the prior year. Other services, centred on non-life insurance, grew revenue 5.8% to ¥165 million and profit 9.0% to ¥11 million, absorbing higher personnel and other costs. Segment revenues include ¥74 million of inter-segment sales, which is why they add up to ¥26,500 million.
Below the operating line: more interest and a heavier tax charge
Non-operating items widened the fall. Interest expense rose 31.5% to ¥125 million from ¥95 million, while non-operating income fell from ¥50 million to ¥37 million, so the net non-operating charge grew from about ¥61 million to ¥101 million and ordinary profit fell faster than operating profit, by 14.7%. Extraordinary items were small: ¥14 million of subsidy income was largely matched by a ¥13 million loss on reduction of fixed assets, and demolition and removal costs were ¥28 million against ¥29 million. Pre-tax profit fell 15.3% to ¥522 million.
The steepest drop came at the tax line. Total income taxes rose 13.8% to ¥252 million despite the lower pre-tax profit, with current taxes at ¥230 million against ¥102 million, lifting the tax burden from about 35.9% to 48.2% of pre-tax profit. The filing gives no explanation for the higher charge. Net profit, all of it attributable to owners of the parent, fell 31.6% to ¥270 million, and comprehensive income fell 26.5% to ¥288 million.
A smaller balance sheet, lower borrowings and three new subsidiaries
Total assets fell 3.4% to ¥58,127 million from ¥60,182 million at March 31, 2026. Cash and deposits fell by ¥1,470 million to ¥3,847 million and tangible fixed assets by ¥508 million, while shares of affiliated companies rose by ¥248 million to ¥638 million. On the other side, long-term borrowings fell by ¥1,426 million to ¥16,834 million and the current portion of long-term borrowings by ¥177 million to ¥5,705 million; income taxes payable fell by ¥556 million and the bonus provision rose by ¥333 million. Net assets slipped 0.7% to ¥15,513 million, as ¥270 million of net profit was outweighed by ¥402 million of dividends, but because total assets fell faster, the equity ratio rose from 26.0% to 26.7%.
The quarter also changed the group's structure. The company made MAG·MAG Co., Ltd. of Matsumoto, Nagano, a wholly owned subsidiary in April 2026 and Harvest Co., Ltd. of Kitaazumi District, Nagano, one in May 2026, and on June 15, 2026 it established ALPICO Asset Design Co., Ltd., into which it has begun consolidating real-estate management and development functions and part of the food and merchandise services previously spread across group companies. The filing nonetheless reports no material change in the scope of consolidation for the quarter and does not state what the new subsidiaries contributed.
Guidance unchanged, with the summer quarter expected to carry the half
Guidance published on May 13, 2026 was left unchanged because results are broadly tracking plan, the company says. For the first half it expects operating revenue of ¥56,500 million (+4.4%), operating profit of ¥2,700 million (−2.1%), ordinary profit of ¥2,300 million (−10.6%) and net profit of ¥1,400 million (−13.7%). For the full year FY3/2027 it expects operating revenue of ¥110,000 million (+2.4%), operating profit of ¥3,700 million (−5.5%), ordinary profit of ¥3,000 million (−15.7%) and net profit attributable to owners of ¥1,600 million (−20.0%), or ¥22.35 per share. The first quarter delivered 24.0% of guided full-year revenue but only 17.7% of guided operating profit, and the half-year guidance implies operating profit of roughly ¥2,050 million in the July–September quarter alone, against ¥653 million in April–June. The filing does not break the forecast down by quarter.
The company expects wage increases, energy prices pushed up by the weak yen and the Middle East situation, and elevated purchasing costs to persist, and says it will pursue appropriate price revisions backed by added value, together with group-wide cost cuts and productivity gains, to secure operating profit. The dividend forecast is unchanged at ¥5.00 per common share for the year, paid at the year-end, the same as for FY3/2026 and about 22% of guided earnings per share. The company also has unlisted Class B shares, on which it forecasts a ¥20.00 dividend, calculated at an annual rate of 2.0% on their paid-in amount.
| Metric | Q1 FY3/2027 | Q1 FY3/2026 | Change |
|---|---|---|---|
| Operating revenue (¥ million) | 26,425 | 25,568 | +3.4% |
| Transport operating expenses and cost of sales (¥ million) | 18,503 | 17,850 | +3.7% |
| SG&A expenses (¥ million) | 7,268 | 7,008 | +3.7% |
| Operating profit (¥ million) | 653 | 708 | −7.7% |
| Operating margin | 2.5% | 2.8% | −0.3 pt |
| Ordinary profit (¥ million) | 551 | 646 | −14.7% |
| Pre-tax profit (¥ million) | 522 | 617 | −15.3% |
| Income taxes (¥ million) | 252 | 221 | +13.8% |
| Net profit attrib. to owners of parent (¥ million) | 270 | 395 | −31.6% |
| EPS (¥) | 3.92 | 5.57 | −29.6% |
| Comprehensive income (¥ million) | 288 | 392 | −26.5% |
| Distribution — revenue (¥ million) | 19,525 | 19,054 | +2.5% |
| Distribution — segment profit (¥ million) | 371 | 515 | −27.8% |
| Transportation — revenue (¥ million) | 3,303 | 3,069 | +7.6% |
| Transportation — segment profit (¥ million) | 258 | 186 | +39.0% |
| Tourism — revenue (¥ million) | 3,165 | 2,999 | +5.5% |
| Tourism — segment profit (¥ million) | 188 | 115 | +62.3% |
| Real Estate — revenue (¥ million) | 340 | 363 | −6.2% |
| Real Estate — segment profit (¥ million) | 35 | 37 | −5.1% |
| Other Services — revenue (¥ million) | 165 | 156 | +5.8% |
| Other Services — segment profit (¥ million) | 11 | 10 | +9.0% |
| Combined segment profit (¥ million) | 865 | 865 | +0.1% |
| Unallocated corporate expenses (¥ million) | 348 | 288 | +20.5% |
| Total assets (¥ million) | 58,127 | 60,182 | −3.4% |
| Net assets (¥ million) | 15,513 | 15,628 | −0.7% |
| Equity ratio | 26.7% | 26.0% | +0.7 pt |
| FY3/2027 guidance — operating revenue (¥ million) | 110,000 | — | +2.4% |
| FY3/2027 guidance — operating profit (¥ million) | 3,700 | — | −5.5% |
| FY3/2027 guidance — ordinary profit (¥ million) | 3,000 | — | −15.7% |
| FY3/2027 guidance — net profit (¥ million) | 1,600 | — | −20.0% |
| FY3/2027 guidance — EPS (¥) | 22.35 | — | — |
| Annual dividend per share (¥) | 5.00 | 5.00 | unchanged |
JapanStockPulse provides informational content only and does not constitute investment advice. Figures are taken from the company's published earnings short report and may be subject to subsequent revision.