Sales grew 9.5%, and expenses absorbed almost all of it
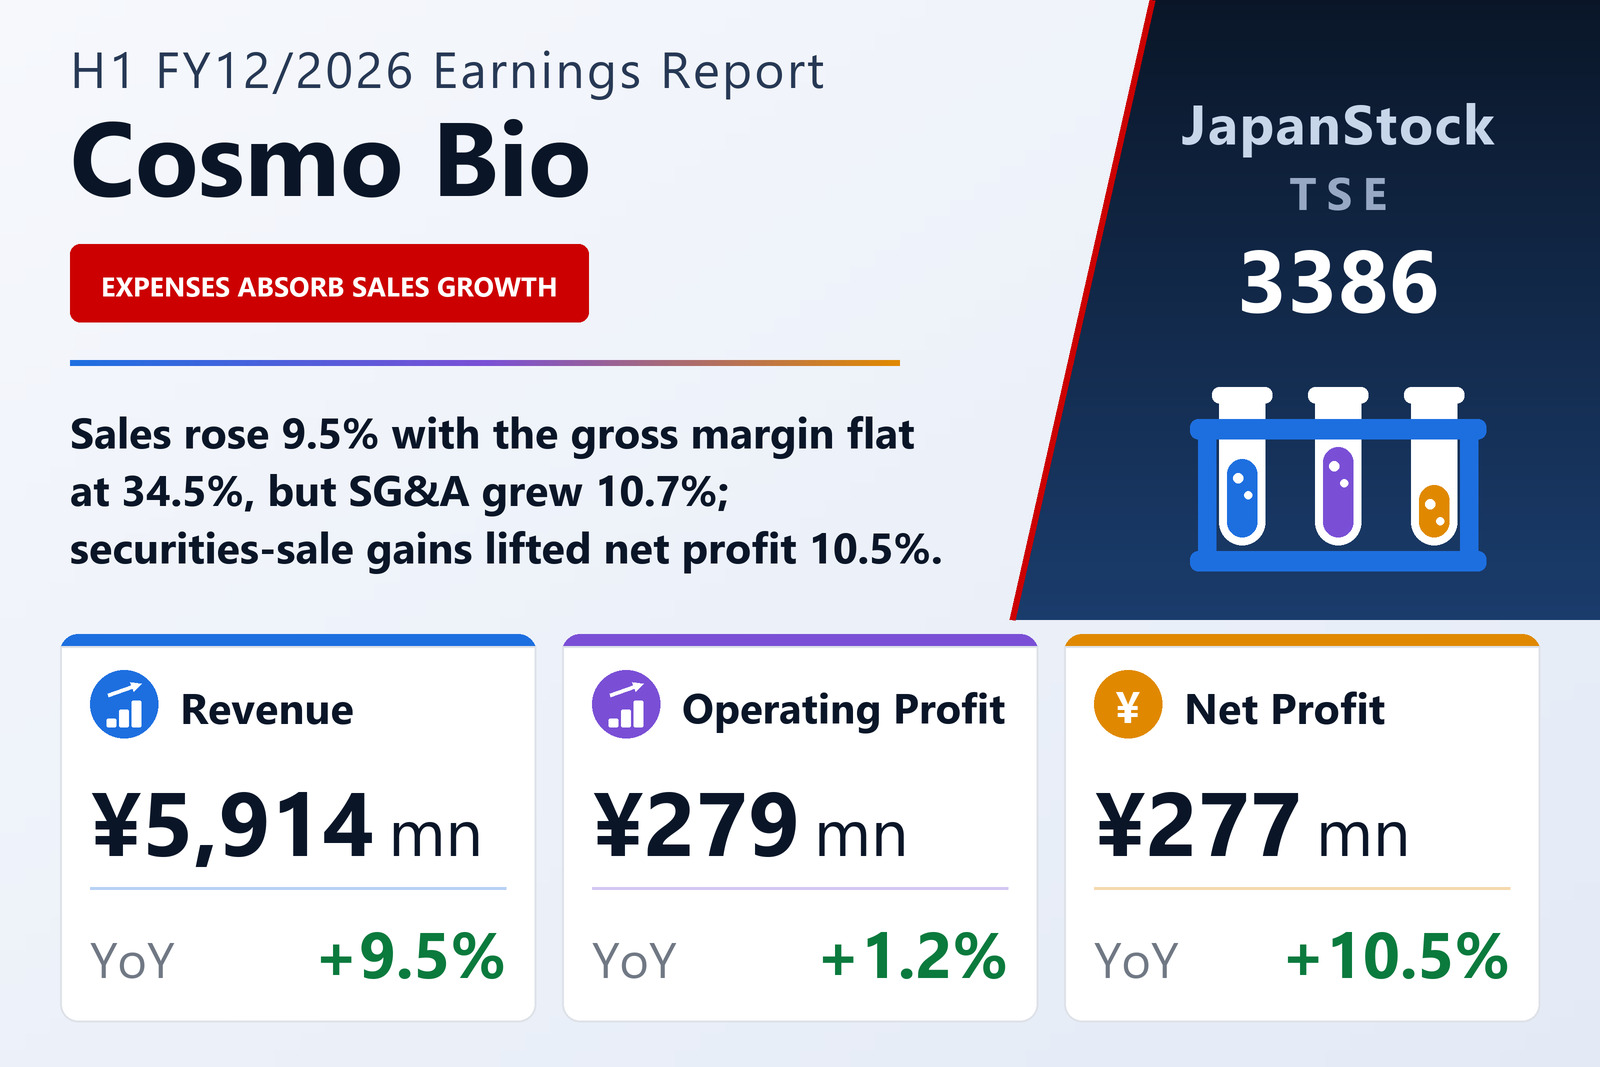
COSMO BIO CO., LTD. (TSE: 3386), which supplies research reagents and instruments to the life-science basic-research market, published consolidated results for the first half of FY12/2026 — the six months from January 1 to June 30, 2026 — on August 5, 2026 under Japanese GAAP. Net sales rose 9.5% to ¥5,914 million and operating profit 1.2% to ¥279 million, while ordinary profit slipped 0.8% to ¥340 million. Profit attributable to owners of the parent rose 10.5% to ¥277 million, for earnings of ¥48.79 per share against ¥44.03. The filing states that these half-year figures were not subject to review by an auditor.
The arithmetic is short. Cost of sales rose 9.5% to ¥3,873 million, in step with sales, so gross profit rose 9.3% to ¥2,040 million and the gross margin stayed at 34.5%, the same as a year earlier. Selling, general and administrative expenses rose 10.7% to ¥1,760 million — an increase of ¥170 million against a ¥174 million gain in gross profit. That left operating profit only ¥3 million higher, and the operating margin narrowed from 5.1% to 4.7%. The filing's only explanation is that various expenses increased. The one SG&A item it breaks out, salaries and allowances, rose to ¥522 million from ¥479 million, and depreciation in the cash-flow statement rose to ¥93 million from ¥72 million. The company also reports an average exchange rate of ¥155 per dollar against ¥149 a year earlier, without quantifying its effect.
Reagents are four-fifths of sales; instruments grew faster
Cosmo Bio reports a single segment, so the only breakdown the filing gives is by product. Research reagents brought in ¥4,694 million, up 8.2%, about 79% of sales, and instruments ¥1,219 million, up 14.4%. The filing does not print the prior-year amounts for either line, so the table shows their growth rates only. On the market, the company says universities and public research institutions have been executing their budgets steadily, but that market conditions and price competition with other suppliers remain severe.
The half was the first year of a three-year plan. Under its stated purpose of contributing to the progress of life science, the company says it is supplying a range of its own products, merchandise and services for life-science research and development, while working to optimise inventory and ship quickly. It describes a Japanese economy facing high energy and raw-material prices and a persistently weak yen, and an uncertain outlook abroad because of the prolonged situation in Ukraine and heightened tension in the Middle East.
Below the operating line, securities sales did the lifting
Non-operating income was unchanged at ¥82 million. Dividends received rose to ¥61 million from ¥49 million, offset by the loss of last year's ¥8 million foreign-exchange gain and by lower insurance surrender proceeds of ¥3 million against ¥10 million. Non-operating expenses rose to ¥21 million from ¥16 million, including a ¥3 million foreign-exchange loss and a ¥9 million loss on retirement of non-current assets against ¥4 million, which left ordinary profit at ¥340 million against ¥343 million. The difference at the bottom line came from extraordinary items: gains on the sale of investment securities of ¥70 million against ¥28 million, less a ¥1 million valuation loss. Pre-tax profit rose 10.2% to ¥409 million, income taxes were ¥120 million against ¥115 million, and profit rose to ¥289 million, of which ¥12 million was attributable to non-controlling interests against ¥5 million a year earlier.
Put simply, the ¥27 million increase in profit attributable to owners is smaller than the ¥42 million increase in securities gains; the business itself added ¥3 million of operating profit. Comprehensive income rose 36.1% to ¥506 million from ¥372 million, because other comprehensive income reached ¥217 million against ¥116 million: valuation gains on available-for-sale securities of ¥217 million against ¥177 million, a deferred hedge loss of ¥8 million against ¥42 million, and a translation gain of ¥8 million against a ¥19 million loss.
Cash rose ¥720 million as receivables were collected
Total assets rose ¥181 million to ¥12,844 million from December 31, 2025. Within current assets, cash and deposits rose ¥720 million to ¥3,468 million and securities ¥400 million, while trade receivables fell ¥485 million and merchandise and finished goods ¥89 million; investment securities fell ¥248 million. Liabilities fell ¥212 million to ¥2,494 million, with current liabilities down ¥340 million — accounts payable dropped to ¥622 million from ¥806 million — and non-current liabilities up ¥128 million. Net assets rose ¥393 million to ¥10,349 million, and the equity ratio climbed from 74.0% to 76.0%. Short-term borrowings were ¥20 million.
Operating activities generated ¥718 million, up 3.5%, chiefly from ¥409 million of pre-tax profit, a ¥488 million fall in receivables and a ¥97 million fall in inventories, partly offset by a ¥224 million fall in payables and income taxes paid of ¥138 million against ¥4 million. Investing activities brought in ¥138 million, mainly ¥162 million from selling investment securities and ¥100 million from sales and redemptions of securities, against ¥105 million spent on property, plant and equipment. Financing used ¥145 million, almost all of it ¥141 million of dividends. Cash and cash equivalents ended the half at ¥3,468 million, up from ¥2,747 million.
A full-year forecast that the first half has already passed
The full-year forecast published on July 24, 2026 is unchanged. For FY12/2026 Cosmo Bio expects net sales of ¥11,500 million (+6.8%), operating profit of ¥270 million (−21.3%), ordinary profit of ¥380 million (−22.4%) and profit attributable to owners of ¥320 million (−5.1%), for earnings per share of ¥56.32. The first half delivered 51.4% of the sales forecast but 103.3% of the operating-profit forecast, 89.5% of ordinary profit and 86.6% of net profit. Taken at face value, the forecast implies second-half sales of ¥5,586 million, below the ¥5,914 million just reported, an operating loss of about ¥9 million, ordinary profit of ¥40 million and net profit of ¥43 million. The tanshin does not explain why the second half should be weaker.
The dividend forecast was not revised. An interim dividend of ¥25.00 has been declared, with payment starting September 10, 2026, and ¥25.00 is forecast at the year-end, for an annual ¥50.00, the same as FY12/2025 — about 89% of the forecast earnings per share. The company planned a results briefing for institutional investors and analysts on August 6, 2026.
| Metric | H1 FY12/2026 | H1 FY12/2025 | Change |
|---|---|---|---|
| Net sales (¥ million) | 5,914 | 5,402 | +9.5% |
| Research reagents sales (¥ million) | 4,694 | — | +8.2% |
| Instruments sales (¥ million) | 1,219 | — | +14.4% |
| Gross profit (¥ million) | 2,040 | 1,866 | +9.3% |
| Gross margin | 34.5% | 34.5% | unchanged |
| SG&A expenses (¥ million) | 1,760 | 1,590 | +10.7% |
| Operating profit (¥ million) | 279 | 276 | +1.2% |
| Operating margin | 4.7% | 5.1% | −0.4 pt |
| Ordinary profit (¥ million) | 340 | 343 | −0.8% |
| Gain on sale of investment securities (¥ million) | 70 | 28 | +150.0% |
| Pre-tax profit (¥ million) | 409 | 371 | +10.2% |
| Net profit attrib. to owners of parent (¥ million) | 277 | 250 | +10.5% |
| Comprehensive income (¥ million) | 506 | 372 | +36.1% |
| EPS (¥) | 48.79 | 44.03 | +10.8% |
| Operating cash flow (¥ million) | 718 | 694 | +3.5% |
| Total assets (¥ million) | 12,844 | 12,662 | +1.4% |
| Cash and deposits (¥ million) | 3,468 | 2,747 | +26.2% |
| Net assets (¥ million) | 10,349 | 9,955 | +4.0% |
| Equity ratio | 76.0% | 74.0% | +2.0 pt |
| FY12/2026 guidance — revenue (¥ million) | 11,500 | — | +6.8% |
| FY12/2026 guidance — operating profit (¥ million) | 270 | — | −21.3% |
| FY12/2026 guidance — ordinary profit (¥ million) | 380 | — | −22.4% |
| FY12/2026 guidance — net profit (¥ million) | 320 | — | −5.1% |
| FY12/2026 guidance — EPS (¥) | 56.32 | — | — |
| Annual dividend per share (¥) | 50.00 | 50.00 | unchanged |
JapanStockPulse provides informational content only and does not constitute investment advice. Figures are taken from the company's published earnings short report and may be subject to subsequent revision.