A first-quarter sales record, and a thinner margin underneath it
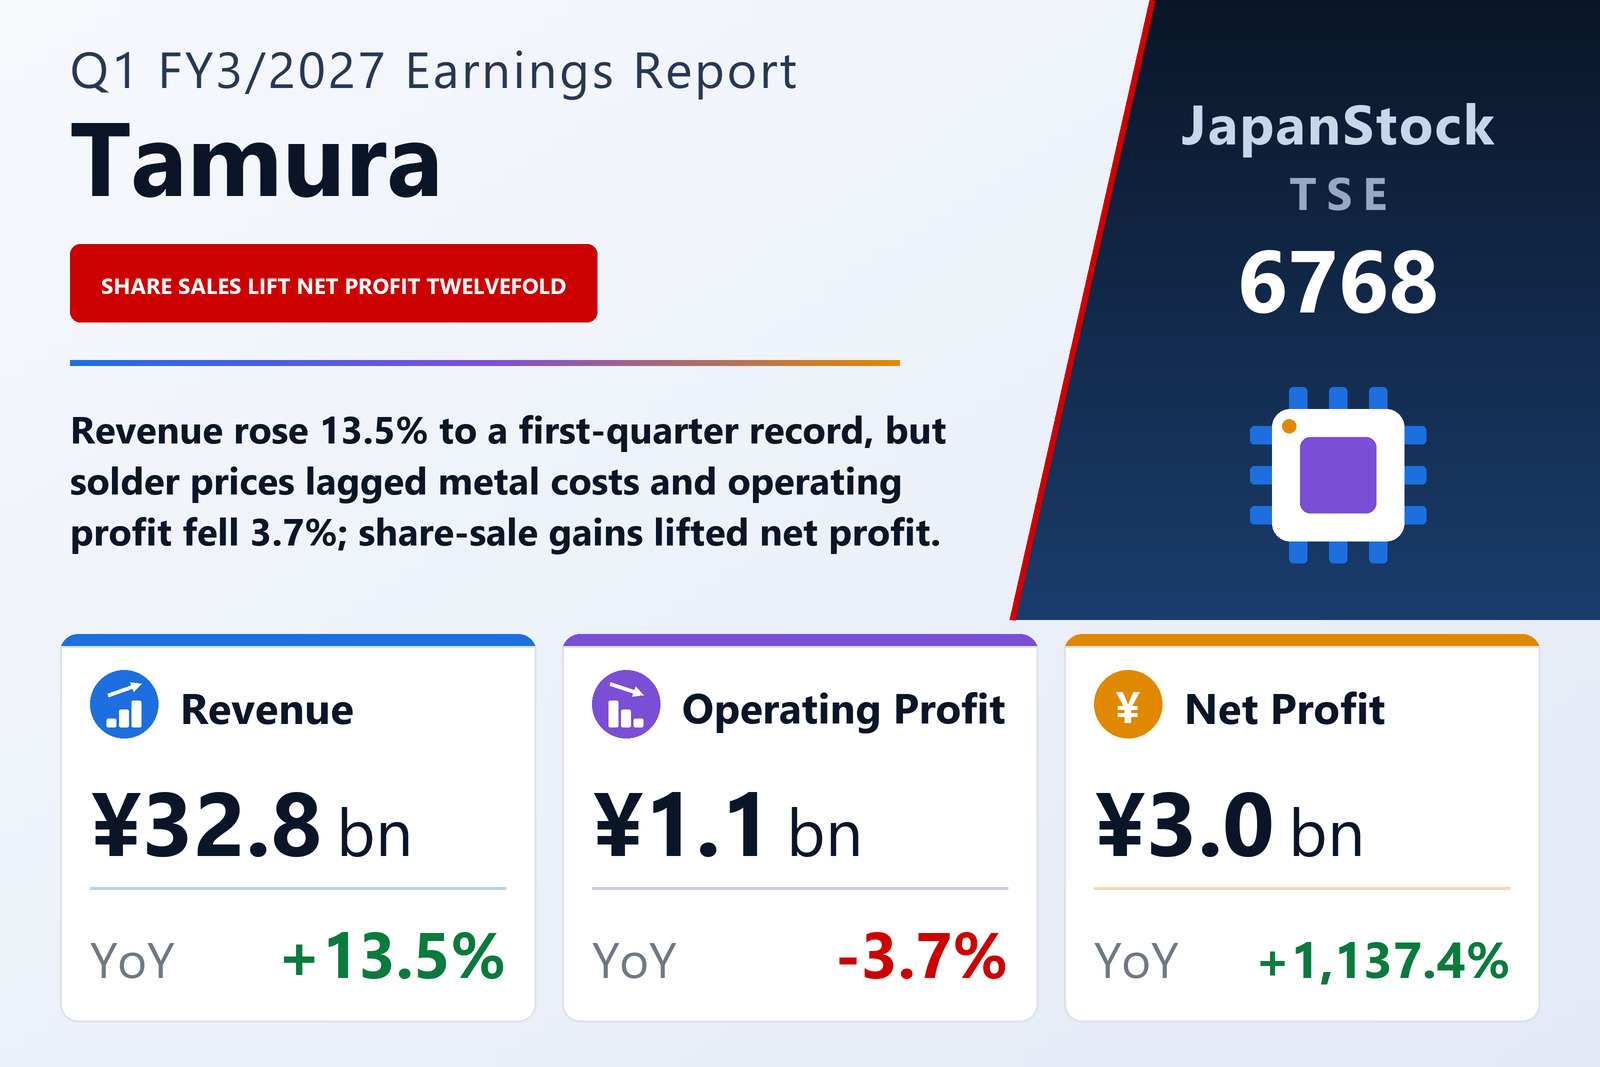
Tamura Corporation (TSE: 6768), the maker of transformers, reactors and other electronic components as well as solder paste, solder resist and mounting equipment, published consolidated results for the first quarter of FY3/2027, the three months from April 1 to June 30, 2026, on August 5, 2026 under Japanese GAAP. Revenue rose 13.5% to ¥32,784 million, which the company describes as the highest first-quarter figure since it began disclosing quarterly results. Operating profit fell 3.7% to ¥1,135 million, ordinary profit rose 19.4% to ¥1,103 million, and profit attributable to owners of the parent rose to ¥3,044 million from ¥246 million, for earnings of ¥38.25 per share against ¥3.03.
The gap between the top line and the operating line comes down to cost of sales. It rose 15.3% to ¥24,766 million, faster than revenue, so gross profit grew only 8.4% to ¥8,017 million and the gross margin narrowed from 25.6% to 24.5%. Selling, general and administrative expenses rose 10.7% to ¥6,882 million, also faster than gross profit, and the operating margin fell from 4.1% to 3.5%. The filing gives a specific reason: in the Electronic Chemicals & Mounting business, raw-material prices rose sharply, and the price-linked system under which the company passes metal costs on to customers reflected that rise only with a time lag.
Below the operating line: smaller currency losses, then two disposal gains
Ordinary profit rose even though operating profit fell, because non-operating expenses halved, from ¥569 million to ¥283 million. Foreign-exchange losses shrank from ¥165 million to ¥24 million and other non-operating expenses from ¥161 million to ¥19 million, while interest expense was almost flat at ¥239 million. Non-operating income fell from ¥314 million to ¥251 million; the prior-year quarter had included ¥128 million of settlement income.
The step from ordinary profit to net profit is almost entirely one-off. The company sold part of its investment securities to improve capital efficiency, booking a ¥1,522 million gain, and completed the transfer of its equity in one consolidated subsidiary as part of a reorganisation of its China business, booking a ¥669 million gain on the sale of affiliate shares; that subsidiary, in Foshan, left the scope of consolidation in the quarter. Pre-tax profit was therefore ¥3,287 million against ¥917 million. Income taxes fell to ¥245 million from ¥675 million, helped by a deferred-tax credit of ¥197 million, so profit attributable to owners of the parent came to ¥3,044 million, about twelve times the prior-year figure. Comprehensive income was ¥2,918 million against a loss of ¥1,775 million a year earlier, when foreign-currency translation adjustments had subtracted ¥1,836 million.
Transformers for data centres grew the profit; solder grew the sales
Electronic Components, the largest segment, grew revenue 6.9% to ¥21,146 million and segment profit 19.9% to ¥1,041 million. The filing attributes the growth to continued generative-AI demand, which lifted sales of large transformers and reactors, chiefly for power distribution units and uninterruptible power supplies in US data centres, and to recovering demand for transformers and reactors for industrial machinery. Chargers for power tools paused while reactors for air conditioners were stable. The profit gain came from higher sales of value-added products, including the large transformers and reactors and transformers for aerospace and defence.
Electronic Chemicals & Mounting grew revenue fastest, 31.6% to ¥11,565 million, but its segment profit fell 19.8% to ¥610 million. Solder paste for automotive uses was stable and demand from information and communications uses such as AI servers increased, while higher prices for tin, silver and other key metals raised selling prices and pushed revenue up. The same metal prices squeezed profit, because price revisions under the linked system could not keep pace. Solder resist for smartphone flexible circuit boards and for AI servers was firm, and mounting-equipment sales stayed low as customers in Japan and abroad were slow to resume capital spending.
Information Equipment revenue fell 71.1% to ¥90 million amid weak capital spending across the broadcasting industry, and its segment loss narrowed to ¥267 million from ¥292 million. As announced on April 8, 2026, the company plans to transfer this business on October 1, 2026. Segment figures include intersegment sales; the reconciling adjustment to operating profit was −¥249 million against −¥158 million, including unallocated corporate costs of ¥252 million, which the filing describes as head-office future-development research and core-system renewal costs.
Lower debt, higher equity
Total assets fell by ¥1,245 million to ¥131,136 million from ¥132,381 million at March 31, 2026. Investment securities fell from ¥4,915 million to ¥4,107 million after the sale of cross-shareholdings, and property, plant and equipment declined with the sale of the subsidiary, while raw materials and supplies rose from ¥12,341 million to ¥14,133 million. Liabilities fell by ¥3,523 million to ¥65,960 million, mainly through lower trade payables and borrowings, and interest-bearing debt fell by ¥1,284 million to ¥37,200 million. Net assets rose by ¥2,278 million to ¥65,175 million, mainly on a ¥2,401 million increase in retained earnings, and the equity ratio improved from 47.4% to 49.6%. The company did not prepare a quarterly cash-flow statement; depreciation was ¥1,169 million against ¥1,067 million.
Full-year guidance held; the dividend is set to rise
Tamura left unchanged the full-year FY3/2027 forecast it published on May 11, 2026: revenue of ¥130,000 million (+5.2%), operating profit of ¥5,600 million (+5.9%), ordinary profit of ¥4,900 million (+0.4%) and profit attributable to owners of ¥4,500 million, or ¥56.55 per share. The first quarter delivered 25.2% of guided revenue and 20.3% of guided operating profit, but 67.6% of guided net profit, a share inflated by the disposal gains. The company expects Electronic Components to keep growing on data-centre demand and a recovery in industrial machinery, and expects Electronic Chemicals & Mounting to improve its profitability from the second quarter as price revisions for higher metal costs take effect. It cites geopolitical risks, including the situation in the Middle East, and says any effect of higher raw-material prices linked to the Middle East is not built into the forecast because it cannot yet be reasonably estimated.
The dividend forecast is also unchanged, at ¥8.00 at the half-year and ¥8.00 at the year-end, for an annual ¥16.00 against ¥13.00 for FY3/2026, an increase of 23.1% and about 28% of the guided earnings per share.
An Italian transformer maker to join in October
After the quarter, on July 17, 2026, Tamura decided to acquire 80% of EMG Power Electric S.r.l., an Italian developer and manufacturer of large transformers and reactors, through its subsidiary TAMURA-EUROPE LIMITED, and signed a share purchase agreement. The acquisition, for cash, is scheduled for October 1, 2026, at a cost of about ¥9.5 billion including advisory fees; the final amount may change with exchange rates. The company says EMG brings medium-voltage dry-type transformer technology, including vacuum pressure impregnation and moulded transformers, to widen its large transformer and reactor range for the medium-voltage, high-capacity market. Goodwill and the assets and liabilities acquired have not yet been determined.
| Metric | Q1 FY3/2027 | Q1 FY3/2026 | Change |
|---|---|---|---|
| Revenue (¥ million) | 32,784 | 28,872 | +13.5% |
| Gross profit (¥ million) | 8,017 | 7,394 | +8.4% |
| Gross margin | 24.5% | 25.6% | −1.1 pt |
| SG&A expenses (¥ million) | 6,882 | 6,216 | +10.7% |
| Operating profit (¥ million) | 1,135 | 1,178 | −3.7% |
| Operating margin | 3.5% | 4.1% | −0.6 pt |
| Ordinary profit (¥ million) | 1,103 | 923 | +19.4% |
| Pre-tax profit (¥ million) | 3,287 | 917 | +258.5% |
| Net profit attrib. to owners of parent (¥ million) | 3,044 | 246 | +1,137.4% |
| Comprehensive income (¥ million) | 2,918 | −1,775 | loss to profit |
| EPS (¥) | 38.25 | 3.03 | +1,162.4% |
| Electronic Components — revenue (¥ million) | 21,146 | 19,783 | +6.9% |
| Electronic Components — segment profit (¥ million) | 1,041 | 868 | +19.9% |
| Electronic Chemicals & Mounting — revenue (¥ million) | 11,565 | 8,788 | +31.6% |
| Electronic Chemicals & Mounting — segment profit (¥ million) | 610 | 761 | −19.8% |
| Information Equipment — revenue (¥ million) | 90 | 312 | −71.1% |
| Information Equipment — segment profit (¥ million) | −267 | −292 | loss narrowed |
| Total assets (¥ million) | 131,136 | 132,381 | −0.9% |
| Net assets (¥ million) | 65,175 | 62,897 | +3.6% |
| Equity ratio | 49.6% | 47.4% | +2.2 pt |
| FY3/2027 guidance — revenue (¥ million) | 130,000 | — | +5.2% |
| FY3/2027 guidance — operating profit (¥ million) | 5,600 | — | +5.9% |
| FY3/2027 guidance — ordinary profit (¥ million) | 4,900 | — | +0.4% |
| FY3/2027 guidance — net profit (¥ million) | 4,500 | — | — |
| FY3/2027 guidance — EPS (¥) | 56.55 | — | — |
| Annual dividend per share (¥) | 16.00 | 13.00 | +23.1% |
JapanStockPulse provides informational content only and does not constitute investment advice. Figures are taken from the company's published earnings short report and may be subject to subsequent revision.