Copper and gold prices, not volumes, carried the quarter
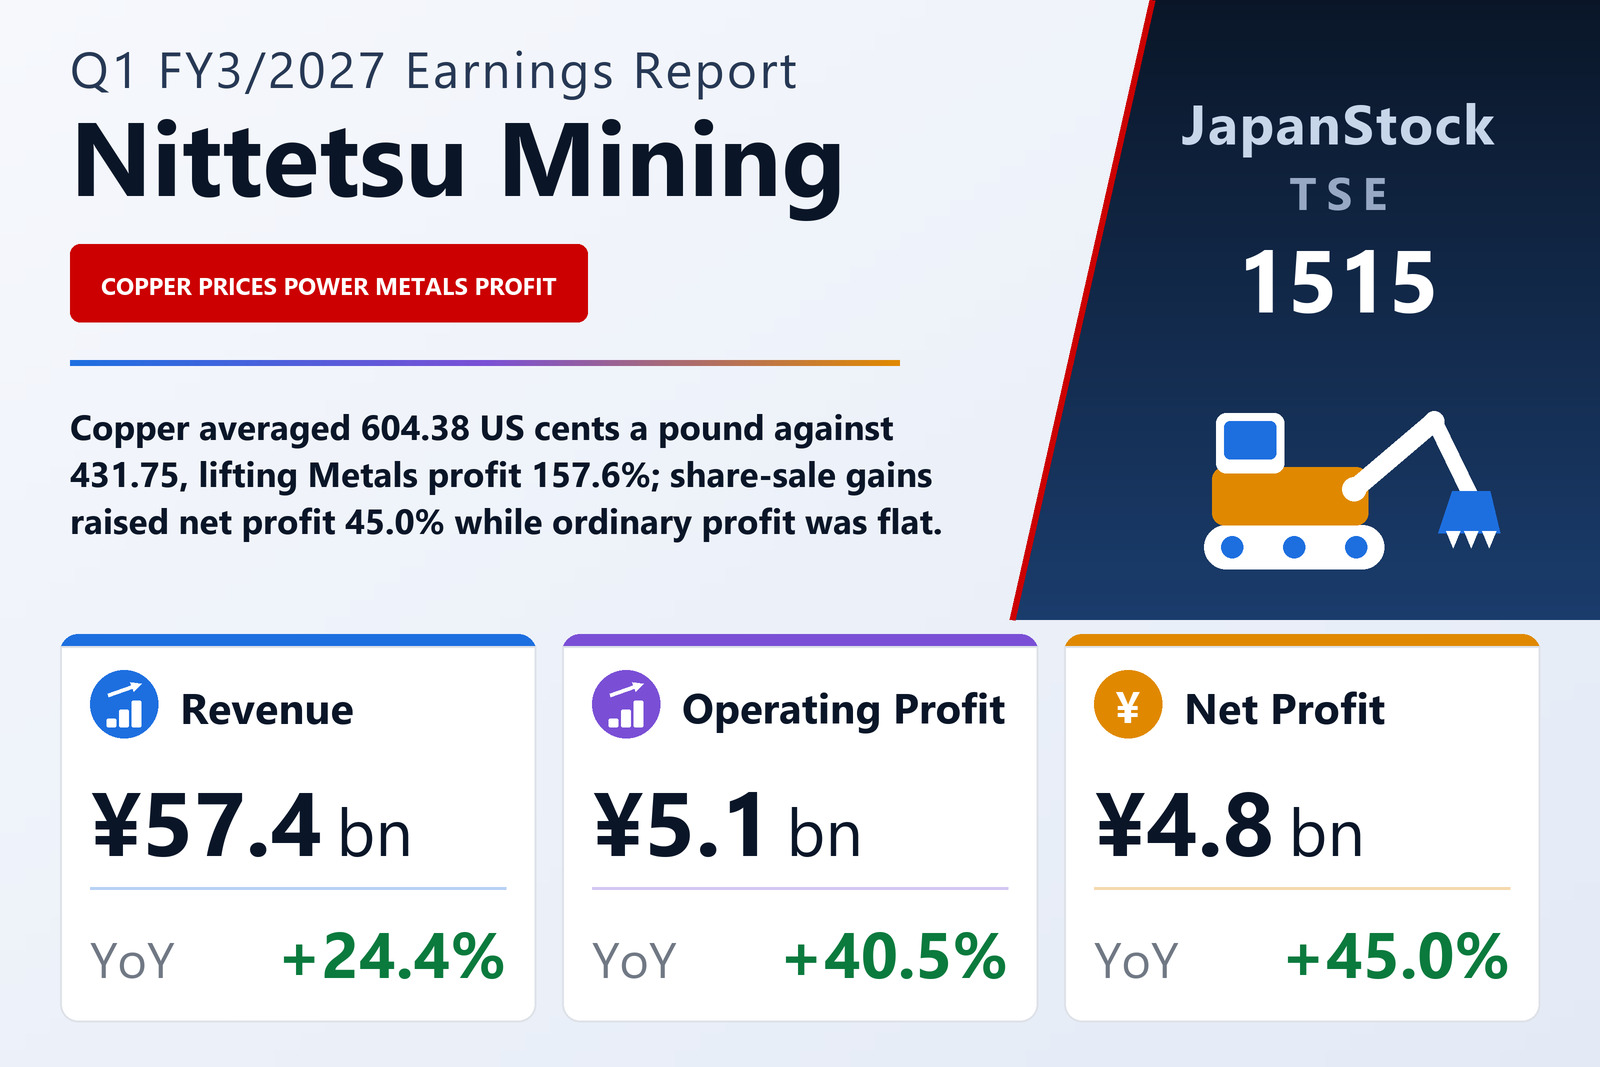
Nittetsu Mining Co., Ltd. (TSE: 1515), the resources group whose businesses span limestone, electrolytic copper and copper concentrate, industrial machinery and environmental products, real estate, and geothermal and solar power, published consolidated first-quarter results for the three months from April 1 to June 30, 2026 on August 6, 2026 under Japanese GAAP. Net sales rose 24.4% to ¥57,406 million, operating profit 40.5% to ¥5,088 million and profit attributable to owners of the parent 45.0% to ¥4,782 million, while ordinary profit edged down 0.6% to ¥4,470 million. Earnings per share were ¥61.27 against ¥41.91, the prior-year figure restated for the five-for-one share split that took effect on October 1, 2025. The company is listed on the Tokyo Stock Exchange.
The filing attributes the sales increase to the Metals segment, where higher domestic selling prices for electrolytic copper and electrolytic gold lifted sales 41.8% to ¥34,737 million. The supplementary data show how much of that was price. Copper averaged 604.38 US cents a pound against 431.75, up 40.0%, and the yen averaged ¥159.49 to the dollar against ¥144.59. Volumes went the other way: electrolytic copper sold fell to 11,028 tonnes from 11,964 and copper concentrate to 7,497 tonnes from 10,067. Yet electrolytic copper revenue rose 42.9% to ¥23,787 million from ¥16,648 million — by our arithmetic, about 55% more revenue per tonne — while concentrate revenue edged up to ¥5,019 million from ¥4,964 million, and other metals revenue, a line the filing does not break down, rose to ¥5,930 million from ¥2,882 million.
Costs rose faster than sales, but overheads barely moved
Cost of sales rose 26.4% to ¥45,789 million, two points faster than sales, so gross profit grew a slower 17.3% to ¥11,617 million and the gross margin narrowed from 21.5% to 20.2%. What turned that into a 40.5% operating gain was overhead: selling, general and administrative expenses rose only 3.9% to ¥6,529 million, lifting the operating margin from 7.8% to 8.9%. At segment level, Metals profit rose from ¥783 million to ¥2,019 million, which the filing attributes to currency movements and higher profit at the Atacama mine on the higher copper price. That ¥1,236 million step was larger than the rise in total segment profit, from ¥4,383 million to ¥5,545 million, because the other four segments combined slipped slightly. The rest of the operating improvement came from the reconciling line: unallocated corporate costs — mainly general administration, research and exploration expenses not attributed to any segment — fell to ¥505 million from ¥811 million, a decline the filing does not explain.
Equity-method and currency losses flattened ordinary profit
More than the whole ¥1,468 million operating gain was given back below the operating line. Non-operating income fell to ¥947 million from ¥1,184 million, as a year-earlier equity-method gain of ¥263 million and a small foreign-exchange gain did not recur. Non-operating expenses rose to ¥1,564 million from ¥308 million: an equity-method investment loss of ¥450 million, a foreign-exchange loss of ¥322 million, a derivative valuation loss of ¥290 million, interest expense of ¥242 million against ¥126 million, and costs of maintaining suspended and closed mines of ¥117 million against ¥62 million. Net non-operating items thus swung from +¥876 million to −¥617 million, leaving ordinary profit at ¥4,470 million against ¥4,496 million. The filing names the deterioration in equity-method results and the foreign-exchange loss as the causes; it does not identify the affiliates or the derivative positions involved.
Share sales, not trading, lifted net profit
Extraordinary income rose to ¥3,183 million from ¥543 million, chiefly a ¥2,759 million gain on the sale of investment securities, against less than ¥1 million a year earlier, and a ¥421 million gain on the sale of fixed assets against ¥8 million. Last year's figure had instead consisted mostly of ¥535 million of development contribution income, which did not recur. Extraordinary losses were ¥85 million against ¥44 million. Pre-tax profit therefore rose 51.5% to ¥7,568 million. Income taxes rose to ¥2,340 million from ¥1,311 million, an effective rate of 30.9% against 26.2%, and after ¥444 million attributable to non-controlling interests, profit attributable to owners of the parent came to ¥4,782 million. The filing attributes the increase to higher gains on the sale of shareholdings. Comprehensive income was ¥8,256 million against ¥2,490 million, up 231.5%, on other comprehensive income of ¥3,028 million against −¥1,194 million, with valuation gains on securities of ¥1,371 million against a ¥948 million loss and translation adjustments of +¥763 million against −¥1,677 million.
Limestone volumes fell; the smaller segments moved little
The Ore segment grew sales 4.1% to ¥17,363 million on fuel-related products and higher sales at some subsidiaries, but segment profit slipped 0.3% to ¥2,478 million on lower sales of limestone, its main product: volume fell to 5,199 thousand tonnes from 5,722 thousand and limestone revenue to ¥8,949 million from ¥9,380 million. Machinery & Environment grew sales 10.7% to ¥4,141 million, with machinery flat and environmental products up to ¥3,111 million from ¥2,701 million, but profit fell 14.4% to ¥419 million on higher raw-material prices for water-treatment agents, the environment division's main product. Real Estate sales fell 5.6% to ¥684 million while profit rose 3.9% to ¥445 million on lower depreciation. Renewable Energy sales slipped 1.3% to ¥478 million, with geothermal flat and solar lower, and profit fell 5.9% to ¥183 million on higher geothermal repair costs.
Inventories and borrowings rose, and two U.S. subsidiaries joined the group
Total assets rose 5.3% to ¥326,951 million from ¥310,412 million at March 31, 2026. Work in process rose to ¥29,766 million from ¥20,166 million and raw materials and supplies to ¥9,492 million from ¥4,010 million, while cash and deposits fell to ¥39,586 million from ¥43,459 million. On the other side, trade payables rose to ¥34,767 million from ¥24,826 million and long-term borrowings to ¥53,069 million from ¥44,719 million, taking total liabilities up 10.9% to ¥158,299 million. Net assets rose only 0.6% to ¥168,651 million, as the company bought back shares — treasury stock rose to 2,522,877 shares from 1,317,977 — so the equity ratio fell from 50.7% to 48.4%.
Two companies were consolidated for the first time. On April 20, 2026 the board resolved to put additional capital into its wholly owned U.S. subsidiary, Nittetsu Mining USA LLC, and, through it, to acquire interests in a U.S. company, Wedgetail Operations LLC; the investment was executed on April 28, 2026, and both companies are specified subsidiaries because their capital is at least a tenth of the parent's. The filing does not describe Wedgetail's business or the amount invested.
Guidance unchanged, on assumptions below first-quarter prices
Full-year guidance is unchanged from May 13, 2026: net sales of ¥232,500 million (+10.9%), operating profit of ¥14,000 million (−25.6%), ordinary profit of ¥11,500 million (−43.1%) and profit attributable to owners of ¥12,000 million (−14.5%), for earnings per share of ¥153.72. The first quarter delivered 24.7% of guided sales, 36.3% of operating profit, 38.9% of ordinary profit and 39.9% of net profit. The full-year assumptions of 550.00 US cents a pound for copper and ¥155.00 to the dollar are both below the first-quarter averages of 604.38 cents and ¥159.49; this filing does not explain the profit declines the guidance implies.
The dividend forecast is also unchanged, at ¥31.00 at the interim and ¥31.00 at the year-end, ¥62.00 in all. The filing leaves the FY3/2026 annual total blank because of the share split: the interim dividend was ¥117.00 before the split and the year-end ¥48.00 after it. Dividing the interim by five gives ¥23.40, which would put FY3/2026 at ¥71.40 on a post-split basis — our calculation, not the company's. After the quarter, several days of torrential rain from mid-July hit central and southern Chile, including the Coquimbo Region, where the consolidated subsidiary Arqueros Mining is located; the company says the impact on group results is still under investigation.
| Metric | Q1 FY3/2027 | Q1 FY3/2026 | Change |
|---|---|---|---|
| Net sales (¥ million) | 57,406 | 46,132 | +24.4% |
| Gross profit (¥ million) | 11,617 | 9,905 | +17.3% |
| Gross margin | 20.2% | 21.5% | −1.3 pt |
| SG&A expenses (¥ million) | 6,529 | 6,284 | +3.9% |
| Operating profit (¥ million) | 5,088 | 3,620 | +40.5% |
| Ordinary profit (¥ million) | 4,470 | 4,496 | −0.6% |
| Extraordinary income (¥ million) | 3,183 | 543 | +486.2% |
| Pre-tax profit (¥ million) | 7,568 | 4,996 | +51.5% |
| Net profit attrib. to owners of parent (¥ million) | 4,782 | 3,297 | +45.0% |
| EPS (¥) | 61.27 | 41.91 | +46.2% |
| Ore — revenue (¥ million) | 17,363 | 16,687 | +4.1% |
| Ore — segment profit (¥ million) | 2,478 | 2,486 | −0.3% |
| Metals — revenue (¥ million) | 34,737 | 24,495 | +41.8% |
| Metals — segment profit (¥ million) | 2,019 | 783 | +157.6% |
| Machinery & Environment — revenue (¥ million) | 4,141 | 3,740 | +10.7% |
| Machinery & Environment — segment profit (¥ million) | 419 | 489 | −14.4% |
| Real Estate — revenue (¥ million) | 684 | 725 | −5.6% |
| Real Estate — segment profit (¥ million) | 445 | 428 | +3.9% |
| Renewable Energy — revenue (¥ million) | 478 | 484 | −1.3% |
| Renewable Energy — segment profit (¥ million) | 183 | 195 | −5.9% |
| Electrolytic copper sales volume (tonnes) | 11,028 | 11,964 | −7.8% |
| Copper price, period average (US¢/lb) | 604.38 | 431.75 | +40.0% |
| Exchange rate, period average (¥/US$) | 159.49 | 144.59 | +10.3% |
| Total assets (¥ million) | 326,951 | 310,412 | +5.3% |
| Net assets (¥ million) | 168,651 | 167,622 | +0.6% |
| Equity attrib. to owners of parent (¥ million) | 158,111 | 157,307 | +0.5% |
| Equity ratio | 48.4% | 50.7% | −2.3 pt |
| FY3/2027 guidance — revenue (¥ million) | 232,500 | — | +10.9% |
| FY3/2027 guidance — operating profit (¥ million) | 14,000 | — | −25.6% |
| FY3/2027 guidance — ordinary profit (¥ million) | 11,500 | — | −43.1% |
| FY3/2027 guidance — net profit attrib. to owners of parent (¥ million) | 12,000 | — | −14.5% |
| FY3/2027 guidance — EPS (¥) | 153.72 | — | — |
| Annual dividend per share (¥) | 62.00 | — | — |
JapanStockPulse provides informational content only and does not constitute investment advice. Figures are taken from the company's published earnings short report and may be subject to subsequent revision.