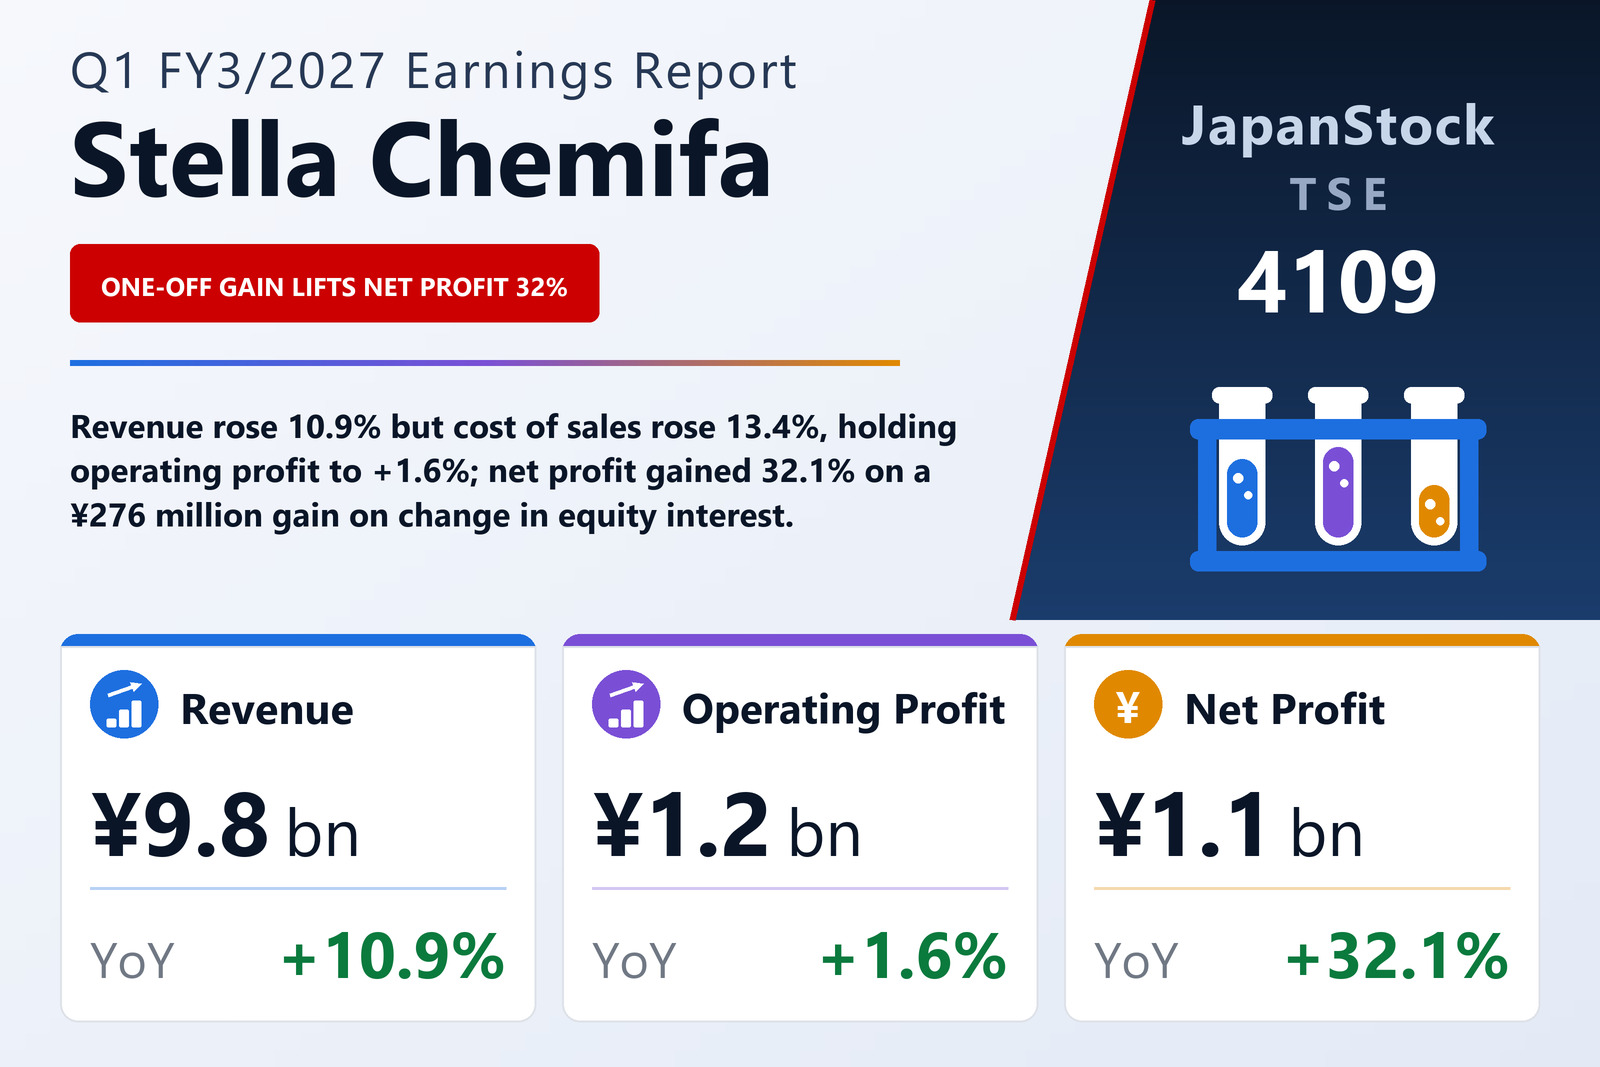
Revenue grew 10.9%, cost of sales 13.4% — and the gap lands on the operating line
Stella Chemifa Corporation (TSE: 4109), the Osaka-based maker of high-purity fluoride chemicals that also runs a chemicals logistics business built on its own specialised cargo-transport know-how, published consolidated first-quarter results for the three months from April 1 to June 30, 2026 on August 6, 2026 under Japanese GAAP. Revenue rose 10.9% to ¥9,754 million, operating profit 1.6% to ¥1,242 million, ordinary profit 2.4% to ¥1,176 million and profit attributable to owners of the parent 32.1% to ¥1,094 million, for earnings of ¥89.67 per share against ¥70.21. The filing gives the listing venue as the Tokyo Stock Exchange and states no market segment.
The gap between the top two lines is the quarter. Cost of sales rose 13.4% to ¥7,489 million against revenue growth of 10.9%, so gross profit added only 3.3%, to ¥2,265 million, and the gross margin narrowed from 24.9% to 23.2%. Selling, general and administrative expenses grew 5.5% to ¥1,022 million — slower than revenue, but faster than gross profit — and the operating margin fell from 13.9% to 12.7%. The company names the cause directly: the price of anhydrous hydrofluoric acid, its principal raw material, was sharply higher than a year earlier, and price pass-throughs together with better profitability in transport recovered only enough of that to leave operating profit ¥20 million above the same quarter of 2025, on revenue that grew by ¥959 million.
A ¥276 million equity gain is the whole of the 32% net-profit jump
Between the operating and ordinary lines the net non-operating charge narrowed. Non-operating income fell to ¥43 million from ¥73 million, but non-operating expenses fell further, to ¥109 million from ¥147 million, as the share of losses from equity-method affiliates dropped to ¥21 million from ¥73 million, while foreign-exchange losses rose to ¥68 million from ¥50 million and interest expense to ¥19 million from ¥12 million. Ordinary profit therefore rose 2.4% to ¥1,176 million, tracking the operating line closely. The step change happens below it: extraordinary gains were ¥286 million against ¥11 million, of which ¥276 million was a gain on change in equity interest — the accounting gain booked when the group's proportionate share of an affiliate's net assets rises, typically because that affiliate has issued new shares. The filing does not identify the company involved, and it reports no significant change in the scope of consolidation during the quarter.
Pre-tax profit consequently rose 26.2% to ¥1,461 million. Strip the ¥276 million out and pre-tax profit would have been roughly ¥1,185 million, about 2.3% above the prior year's ¥1,158 million — in line with the 2.4% recorded at the ordinary line, which is the cleaner reading of the quarter. Income taxes of ¥362 million, computed by applying an estimated full-year effective rate to quarterly pre-tax profit, left quarterly profit of ¥1,098 million, and ¥4 million attributable to non-controlling interests left ¥1,094 million for owners of the parent. Earnings per share rose 27.7% to ¥89.67 rather than 32.1%, because the average share count rose to 12,205,944 from 11,802,915 while issued shares were unchanged at 12,973,248. Comprehensive income was ¥1,098 million against ¥381 million, up 187.9%, because other comprehensive income was nil this time against −¥444 million a year earlier.
Transport, not chemicals, produced the profit growth
Both reporting segments grew their outside sales; only one grew its profit. High-purity Chemicals, the group's core fluoride business, sold ¥8,383 million to outside customers, up 10.2%, yet segment profit fell 9.6% to ¥902 million. Transport sold ¥1,350 million outside the group, up 16.5%, and lifted segment profit 49.1% to ¥337 million; on the segment note's total line, which adds ¥1,082 million of sales to other group companies, transport revenue was ¥2,433 million against ¥2,057 million, up 18.3%. The residual Other segment — insurance agency and vehicle maintenance — sold ¥20 million outside the group against ¥26 million, and earned ¥3 million against ¥2 million. Adding the ¥1,240 million reported-segment total to that ¥3 million and deducting ¥1 million of intersegment elimination gives consolidated operating profit of ¥1,242 million.
The causes the filing gives are short. Revenue grew on higher shipment volumes in the semiconductor and electronic-materials departments, higher sales in the purchased-goods department, and a larger volume of freight handled in the transport business. On profit, the higher anhydrous hydrofluoric acid price was offset by price pass-throughs and by improved profitability in transport. The segment split shows where each of those landed: a chemicals business whose outside sales grew a tenth while its profit fell a tenth, and a transport business that turned a sixth more revenue into half as much profit again. The filing offers no explanation for the fall in High-purity Chemicals profit beyond that raw-material price, and it does not break the segment down into the semiconductor, electronic-materials and purchased-goods departments it names in the narrative.
Cash down ¥1,888 million, inventories up ¥1,113 million
Total assets fell 0.9% to ¥63,585 million from ¥64,149 million at March 31, 2026. Current assets fell ¥478 million to ¥28,450 million: cash and deposits dropped ¥1,888 million to ¥12,929 million while inventories rose — merchandise and finished goods up ¥518 million, work in process up ¥375 million and raw materials and supplies up ¥220 million, ¥1,113 million between them — and trade receivables rose ¥271 million. Non-current assets were little changed at ¥35,134 million, down ¥84 million, with property, plant and equipment down ¥180 million; depreciation for the quarter was ¥743 million against ¥671 million. The company does not prepare a cash flow statement at the first quarter, so this filing does not split that cash movement between operating, investing and financing activity.
Liabilities fell ¥488 million to ¥15,599 million. Current liabilities fell ¥361 million to ¥8,723 million: accounts payable — other fell ¥286 million, income taxes payable ¥357 million and the bonus provision ¥213 million, against a ¥404 million rise in trade payables. Non-current liabilities fell ¥126 million to ¥6,875 million, chiefly on a ¥227 million reduction in long-term borrowings. Net assets slipped 0.2% to ¥47,986 million, as a ¥244 million increase in the foreign-currency translation adjustment was more than offset by a ¥252 million fall in unrealised gains on securities; retained earnings fell ¥80 million, so the ¥1,094 million earned in the quarter was more than absorbed by distributions. Because assets fell slightly faster than equity, the equity ratio edged up from 74.6% to 75.1% — a balance sheet three-quarters funded by its own capital.
Guidance untouched; the dividend total holds but its split moves
Stella Chemifa left the full-year FY3/2027 forecast it published on May 14, 2026 exactly as it stood: revenue of ¥39,100 million (+6.3%), operating profit of ¥4,800 million (+3.3%), ordinary profit of ¥4,900 million (+10.7%) and profit attributable to owners of ¥3,400 million (+11.2%), for earnings per share of ¥278.55. Measured against that, the first quarter delivered 24.9% of guided revenue and 25.9% of guided operating profit — close to a straight quarter of each — but 32.2% of guided net profit, a share inflated by the one-off equity gain rather than by trading. Ordinary profit, at 24.0% of the guided ¥4,900 million, is running closest to a flat quarterly rate, and it is also the line guidance expects to grow fastest over the year, at 10.7% against the operating line's 3.3%.
The dividend forecast was not revised either. The annual total is unchanged from last year at ¥180.00 per share, but the split moves: the company forecasts ¥90.00 at the half year and ¥90.00 at the year-end, against the ¥85.00 and ¥95.00 paid for FY3/2026. No first-quarter dividend is paid and this filing gives no payment start date. Against guided earnings of ¥278.55 per share, an annual ¥180.00 implies a payout of about 65%. The quarterly consolidated financial statements have not been reviewed by a certified public accountant or an audit corporation, which the company discloses on the summary page.
| Metric | Q1 FY3/2027 | Q1 FY3/2026 | Change |
|---|---|---|---|
| Revenue (¥ million) | 9,754 | 8,795 | +10.9% |
| Gross profit (¥ million) | 2,265 | 2,192 | +3.3% |
| Gross margin | 23.2% | 24.9% | −1.7 pt |
| SG&A expenses (¥ million) | 1,022 | 969 | +5.5% |
| Operating profit (¥ million) | 1,242 | 1,222 | +1.6% |
| Operating margin | 12.7% | 13.9% | −1.2 pt |
| Ordinary profit (¥ million) | 1,176 | 1,148 | +2.4% |
| Pre-tax profit (¥ million) | 1,461 | 1,158 | +26.2% |
| Net profit attrib. to owners of parent (¥ million) | 1,094 | 828 | +32.1% |
| EPS (¥) | 89.67 | 70.21 | +27.7% |
| Comprehensive income (¥ million) | 1,098 | 381 | +187.9% |
| High-purity Chemicals — revenue (¥ million) | 8,383 | 7,609 | +10.2% |
| High-purity Chemicals — segment profit (¥ million) | 902 | 998 | −9.6% |
| Transport — revenue (¥ million) | 1,350 | 1,159 | +16.5% |
| Transport — segment profit (¥ million) | 337 | 226 | +49.1% |
| Other — revenue (¥ million) | 20 | 26 | −23.1% |
| Other — segment profit (¥ million) | 3 | 2 | +50.0% |
| Total assets (¥ million) | 63,585 | 64,149 | −0.9% |
| Net assets (¥ million) | 47,986 | 48,061 | −0.2% |
| Equity ratio | 75.1% | 74.6% | +0.5 pt |
| FY3/2027 guidance — revenue (¥ million) | 39,100 | — | +6.3% |
| FY3/2027 guidance — operating profit (¥ million) | 4,800 | — | +3.3% |
| FY3/2027 guidance — ordinary profit (¥ million) | 4,900 | — | +10.7% |
| FY3/2027 guidance — net profit (¥ million) | 3,400 | — | +11.2% |
| Annual dividend per share (¥) | 180.00 | 180.00 | unchanged |
JapanStockPulse provides informational content only and does not constitute investment advice. Figures are taken from the company's published earnings short report and may be subject to subsequent revision.