A record first quarter, and a narrow one
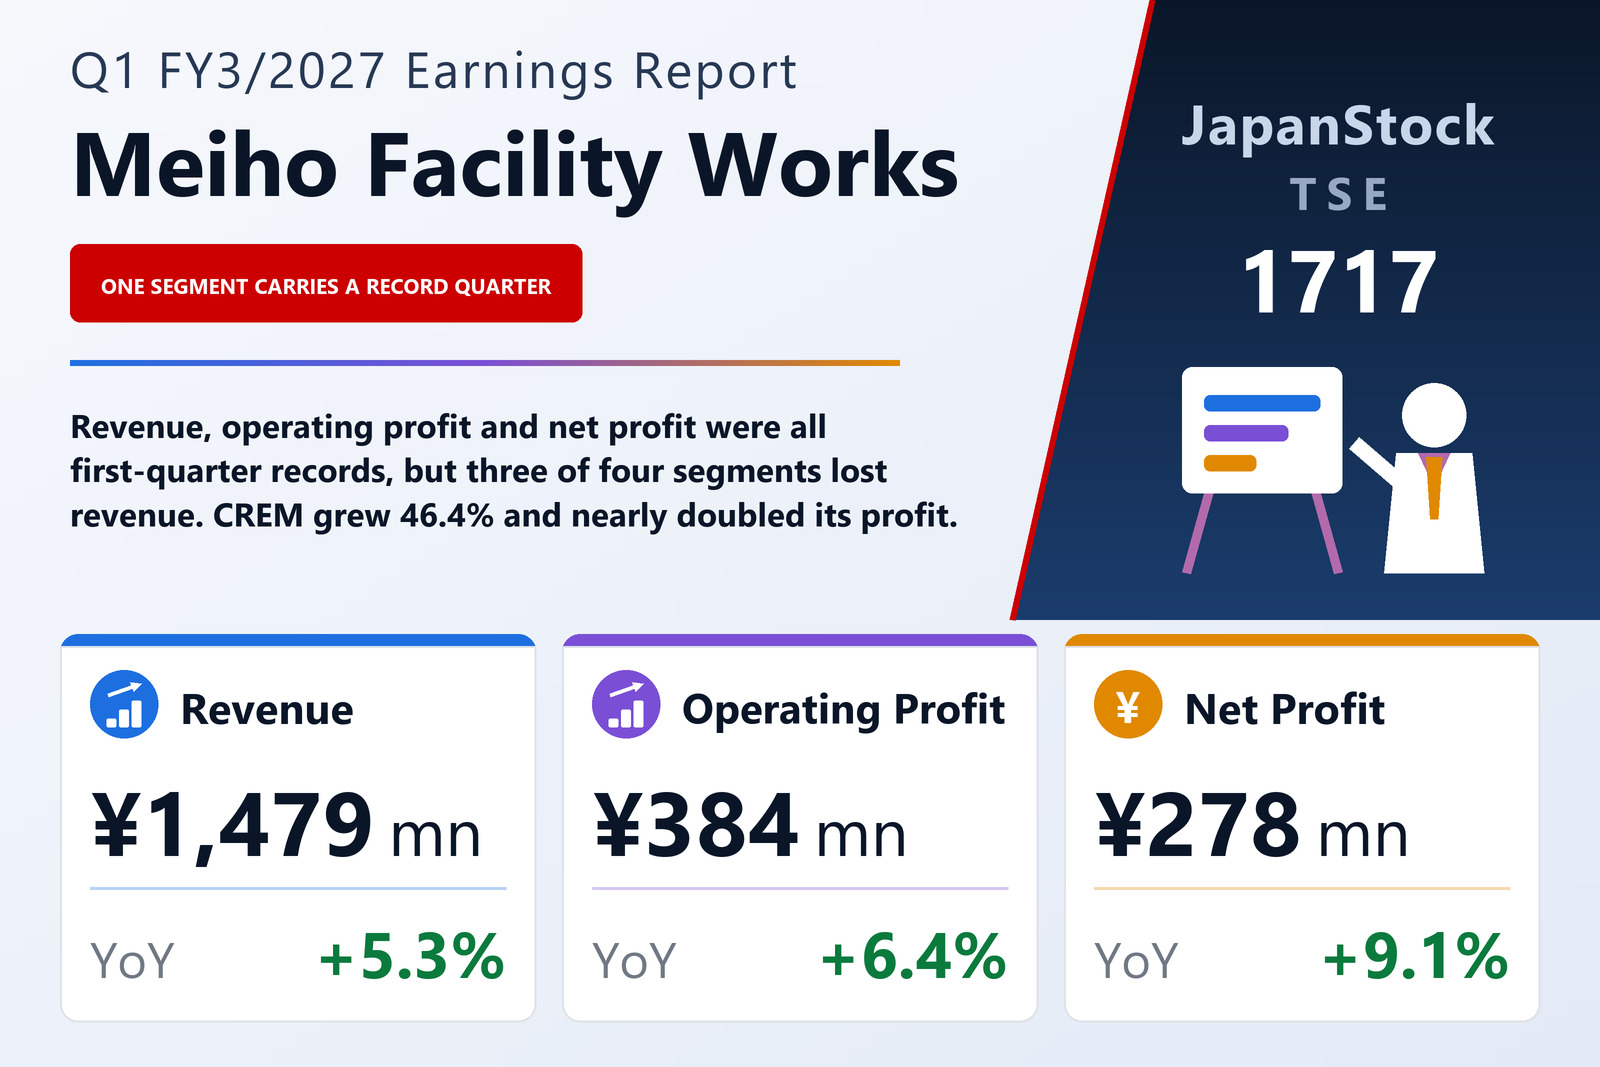
Meiho Facility Works Ltd. (TSE: 1717), a listed construction-management firm that works on the owner's side of building projects rather than the contractor's, reported non-consolidated results for the three months to June 30, 2026 on August 7, 2026 under Japanese GAAP. Revenue rose 5.3% to ¥1,479 million, gross profit 5.1% to ¥855 million, operating profit 6.4% to ¥384 million, ordinary profit 6.6% to ¥385 million and quarterly net profit 9.1% to ¥278 million, or ¥23.71 per share against ¥21.90. The company states that all five of those lines were first-quarter records.
The margin held rather than expanded. Gross margin was 57.8% against 57.9%, so the profit growth came from below the gross line: selling, general and administrative expenses rose 4.0% to ¥471 million, more slowly than revenue, and the operating margin edged up to 26.0% from 25.7%. The filing does not disclose cost of sales as a separate line, so the gross figure and the expense figure are what the reader has.
CREM grew 46.4% and carried the entire result
CREM, the corporate real-estate management business, was the only one of the four segments to grow. Its revenue rose 46.4% to ¥331 million and its segment profit 90.5% to ¥114 million — increases of roughly ¥105 million and ¥54 million. Group revenue rose about ¥75 million over the same quarter and operating profit about ¥23 million, so one segment out of four added more revenue than the company did in total, and more than twice the profit. Segment profit equals operating profit here, with no corporate-cost adjustment, so the arithmetic is direct.
CM, the largest segment, lost 12.7% of its profit
CM, at ¥714 million nearly half of revenue, fell 2.0%, and its segment profit fell 12.7% to ¥184 million — a decline of about ¥27 million, larger than the whole company's operating-profit increase. The filing does not explain why the profit fell more than six times as fast as the revenue. It does describe the market: private-sector investment decisions are temporarily cautious as construction costs rise and supply capacity tightens, though the work in hand includes difficult projects such as data centres and new pharmaceutical plants. In the public sector, enquiries for air-conditioning installation rose notably as extreme heat becomes normal, alongside new government-office construction, rebuilding and life-extension planning for public schools, refurbishment plans for halls and other public facilities, and the digitalisation of project management.
The company frames that backdrop as the argument for its own business: rising construction-material and labour costs, a short supply of people and lengthening equipment and materials lead times mean owners increasingly cannot carry out a construction investment on their own, which it says raises the social role of construction management. Its stated principles are fairness, transparency and professionals who stand on the client's side, and the work itself is to make the risk in a construction investment visible, verify the basis and reasonableness of procurement costs, and support the owner's decisions on cost, quality and schedule. Its projects also drew awards this quarter: at the CM Selection Awards 2026, run by the Japan Construction Management Association, its Minowa Sustainable Energy PG Project won a special award, and its work on Osaka University's integrated infectious-disease education and research base at Suita and on Takeda Pharmaceutical's aseptic filling line implementation won CM awards.
Office revenue fell and its profit rose
Office revenue fell 3.1% to ¥332 million because the prior-year quarter contained a large head-office relocation that has since completed, but segment profit rose 11.7% to ¥76 million, which the company attributes to internal productivity gains. The segment provides one-stop project management for relocations, new offices and workplace reform, from feasibility study and building selection through to the move itself; central Tokyo's run of new office buildings from large redevelopments is bringing it demanding private-sector work, including relocations timed to a building's completion and projects with facility requirements such as attached research facilities. In the public sector it was selected by open tender for the Ministry of Foreign Affairs' office-reform consulting commission, the fifth consecutive year it has won that work.
DX Support was the weakest line in the filing: revenue fell 4.8% to ¥103 million and segment profit 54.4% to ¥10 million, a fall of about ¥12 million that the filing does not explain. The company was certified as a DX-Certified Business Operator by Japan's Ministry of Economy, Trade and Industry in April 2024 and renewed that certification on April 1, 2026. It also notes that its people are deliberately not confined to their own segment: a self-developed project-management system lets staff work across projects, which the company says balances load between segments and improves overall efficiency — a structure that makes the four segment-profit lines less independent of one another than a table implies.
The balance sheet shrank while the quarter earned
Total assets fell 0.9% to ¥8,459 million from ¥8,539 million at March 31, 2026, and net assets fell 4.2% to ¥5,834 million — a decline of ¥257 million in a quarter that earned ¥278 million. Owners' equity fell in step, to ¥5,807 million from ¥6,064 million, and the equity ratio dropped 2.4 points to 68.6%. The filing's summary does not itemise that movement; the ¥44.00 year-end dividend for FY3/2026 falls inside the period, and it is the only distribution disclosed.
Guidance is unchanged, and it implies 2.2% growth
Full-year guidance for FY3/2027 is unchanged: revenue of ¥6,419 million (+5.0%), operating profit of ¥1,297 million (+2.2%), ordinary profit of ¥1,300 million (+2.3%) and net profit of ¥940 million (+0.2%), for earnings per share of ¥79.36. The first half is guided at revenue of ¥3,069 million (+2.7%), operating profit of ¥791 million (+2.8%), ordinary profit of ¥792 million (+2.7%) and net profit of ¥572 million (+0.2%), or ¥48.44 per share. The quarter just reported delivered 29.6% of the full-year operating-profit guide and grew operating profit 6.4% against an annual plan of 2.2%.
The dividend is unchanged too. FY3/2027 is guided at ¥44.00 per share, all of it at the year-end with no interim payment, the same amount and the same shape as FY3/2026. No revision was announced with these results. Neither the contraction in three segments nor CREM's 46.4% is visible in the guidance: the company is holding a plan set before the quarter, and the filing does not reconcile that plan with the quarter's shape.
| Metric | Q1 FY3/2027 | Q1 FY3/2026 | Change |
|---|---|---|---|
| Revenue (¥ million) | 1,479 | 1,405 | +5.3% |
| Gross profit (¥ million) | 855 | 814 | +5.1% |
| SG&A expenses (¥ million) | 471 | 453 | +4.0% |
| Operating profit (¥ million) | 384 | 361 | +6.4% |
| Ordinary profit (¥ million) | 385 | 361 | +6.6% |
| Net profit (¥ million) | 278 | 255 | +9.1% |
| EPS (¥) | 23.71 | 21.90 | +8.3% |
| Gross margin | 57.8% | 57.9% | −0.1 pt |
| Operating margin | 26.0% | 25.7% | +0.3 pt |
| Office — revenue (¥ million) | 332 | 342 | −3.1% |
| Office — segment profit (¥ million) | 76 | 68 | +11.7% |
| CM — revenue (¥ million) | 714 | 729 | −2.0% |
| CM — segment profit (¥ million) | 184 | 211 | −12.7% |
| CREM — revenue (¥ million) | 331 | 226 | +46.4% |
| CREM — segment profit (¥ million) | 114 | 60 | +90.5% |
| DX Support — revenue (¥ million) | 103 | 108 | −4.8% |
| DX Support — segment profit (¥ million) | 10 | 22 | −54.4% |
| Total assets (¥ million) | 8,459 | 8,539 | −0.9% |
| Net assets (¥ million) | 5,834 | 6,091 | −4.2% |
| Shareholders' equity (¥ million) | 5,807 | 6,064 | −4.2% |
| Equity ratio | 68.6% | 71.0% | −2.4 pt |
| FY3/2027 guidance — revenue (¥ million) | 6,419 | — | +5.0% |
| FY3/2027 guidance — operating profit (¥ million) | 1,297 | — | +2.2% |
| FY3/2027 guidance — ordinary profit (¥ million) | 1,300 | — | +2.3% |
| FY3/2027 guidance — net profit (¥ million) | 940 | — | +0.2% |
| FY3/2027 guidance — EPS (¥) | 79.36 | — | n.m. |
| Annual dividend per share (¥) | 44.00 | 44.00 | unchanged |
JapanStockPulse provides informational content only and does not constitute investment advice. Figures are taken from the company's published earnings short report and may be subject to subsequent revision.