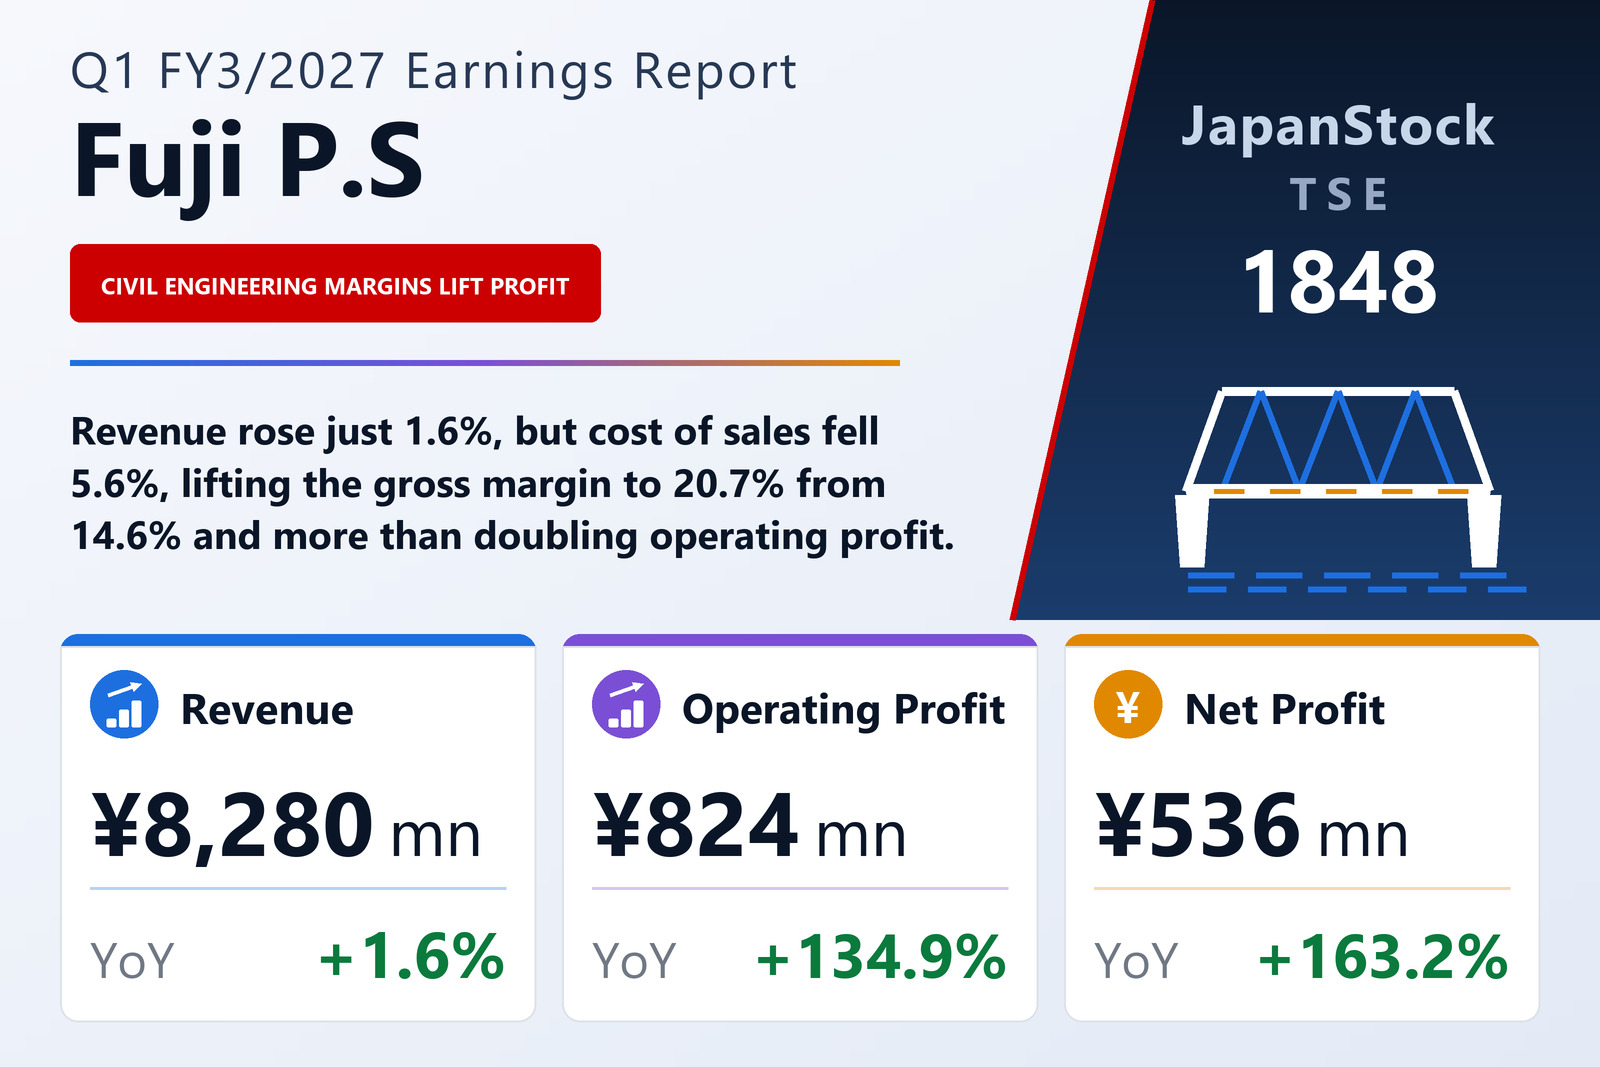
Revenue up 1.6%, operating profit up 134.9%
FUJI P.S CORPORATION (TSE: 1848), a civil-engineering and building contractor whose projects include expressway work and precast prestressed-concrete (PC) buildings, published consolidated results for the first quarter of FY3/2027 — April 1 to June 30, 2026 — on August 7, 2026 under Japanese GAAP. Revenue rose 1.6% to ¥8,280 million, operating profit 134.9% to ¥824 million, ordinary profit 138.0% to ¥787 million and net profit attributable to owners of the parent 163.2% to ¥536 million. Earnings per share were ¥30.37 against ¥11.55, up 162.9% — marginally slower than net profit, because the average number of shares rose to 17,667,667 from 17,656,692. The shares are listed on the Tokyo Stock Exchange and the Fukuoka Stock Exchange.
A 5.6% fall in cost of sales did the work
Revenue barely moved, so the jump in profit came almost entirely from margin. Cost of sales fell 5.6% to ¥6,565 million from ¥6,953 million even as revenue rose, lifting gross profit 43.8% to ¥1,715 million and the gross margin to 20.7% from 14.6%. Selling, general and administrative expenses rose 5.7% to ¥890 million, so almost all of the ¥522 million gain in gross profit reached the operating line, where profit rose by ¥473 million and the operating margin climbed to 10.0% from 4.3%. The company attributes the result to higher revenue and to improved profitability on civil-engineering contracts.
Below the operating line the moves were small. Net non-operating costs widened to ¥37 million from ¥20 million, mainly because interest expense rose to ¥39 million from ¥26 million and guarantee fees to ¥6 million from ¥3 million; ordinary profit still rose 138.0%, a touch faster than operating profit in percentage terms, because it started from a lower base. A year earlier the quarter carried a ¥32 million extraordinary loss on the retirement of fixed assets, and this year there were no extraordinary items, so pre-tax profit rose 164.1% to ¥787 million. Income taxes were ¥251 million against ¥95 million, an effective rate of about 31.9% in both years. Comprehensive income was ¥516 million, up 169.7%, below net profit because other comprehensive income was negative at ¥19 million, mostly an ¥18 million adjustment for retirement benefits.
Civil Engineering carried the quarter; Building Construction shrank but earned more
Civil Engineering, 72.0% of revenue, grew 12.2% to ¥5,961 million, and its segment profit rose 49.4% to ¥1,351 million, widening its segment margin to 22.7% from 17.0%. The company says site work and product manufacturing progressed broadly as planned, with large projects for expressway companies in the Kansai region moving forward particularly well, and credits the profit gain to higher revenue and to its continuing measures to improve contract profitability. Building Construction revenue fell 18.2% to ¥2,297 million, which the company attributes to delays, caused by clients' circumstances, on precast PC projects — a new business it is focusing on, mainly in the Kanto region. Its segment profit nonetheless rose 25.9% to ¥346 million, a margin of 15.1% against 9.8%, on better contract profitability from a profit-improvement project under way since the previous fiscal year.
Segment profit is measured before selling, general and administrative expenses. The two segments plus ¥17 million from other businesses — real-estate leasing and the leasing of construction equipment and materials, which also brought in ¥22 million of revenue — add up to ¥1,715 million, the group's gross profit, from which ¥890 million of SG&A is deducted to reach operating profit. Of the ¥522 million increase in that total, ¥447 million came from Civil Engineering and ¥71 million from Building Construction.
Orders nearly doubled on large civil-engineering awards
Consolidated orders received rose 98.7% to ¥7,958 million; the filing gives the growth rates but not the prior-year amounts. Civil Engineering orders jumped 452.5% to ¥6,271 million. Awards named in the filing include a large Chuo Shinkansen (maglev) project ordered by the Japan Railway Construction, Transport and Technology Agency, superstructure work for the four-lane widening of the Shiida Road ordered by West Nippon Expressway's Kyushu branch, and repair work for the same company's Shikoku branch. Building Construction orders fell 42.5% to ¥1,599 million: projects under planning, mainly in the Kanto region, were contracted early, but the segment faced a reaction to strong orders in the same quarter a year earlier.
During the quarter the company completed renewal work at its Kyushu Kotake plant, carried out to improve working conditions and productivity, and brought the plant into full operation. The year is the sixth of its fifth medium-term management plan, VISION2030, whose interim goal the company has pushed back by one year in response to changes in the external environment.
Receivables and deposits received lifted the balance sheet
Total assets rose 3.8% to ¥36,982 million from ¥35,613 million at March 31, 2026, an increase of ¥1,368 million, mainly because notes and accounts receivable from completed construction contracts and contract assets rose by ¥963 million to ¥22,682 million and ¥248 million of consumption taxes receivable appeared. Liabilities rose by ¥1,244 million to ¥23,714 million: deposits received increased by ¥728 million to ¥4,523 million, advances received on uncompleted construction by ¥559 million to ¥1,086 million, income taxes payable by ¥263 million and electronically recorded obligations by ¥251 million, while other current liabilities fell by ¥681 million. Short-term borrowings were ¥10,057 million against ¥9,957 million, and cash and deposits ¥1,953 million against ¥1,960 million.
Net assets rose 0.9% to ¥13,267 million, reflecting ¥536 million of profit less ¥396 million of dividends paid, and because assets grew faster, the equity ratio slipped to 35.9% from 36.9%. No cash-flow statement is prepared for the quarter; depreciation was ¥182 million against ¥185 million, and goodwill amortisation ¥12 million in both years.
Guidance and the ¥25 dividend unchanged
The full-year forecast published on May 15, 2026 was left unchanged: revenue of ¥33,128 million (+2.8%), operating profit of ¥1,660 million (+4.5%), ordinary profit of ¥1,480 million (+0.2%) and net profit attributable to owners of the parent of ¥1,010 million (+1.7%), or ¥57.18 per share. The company says operating and ordinary profit in the quarter came in above the assumptions behind that forecast, but not by enough to warrant a revision for the full year, and it expects site work and factory production in both segments to proceed broadly to plan from the second quarter onward.
The first quarter alone delivered 25.0% of forecast revenue but 49.6% of forecast operating profit and 53.1% of forecast net profit. Holding the forecast therefore implies operating profit of about ¥836 million for the remaining nine months combined, roughly what was just earned in three; the filing does not say how it expects profit to be spread across those quarters. The dividend forecast is also unchanged at ¥25.00 per share, paid entirely at the year-end, against ¥22.00 for FY3/2026 — a ¥3 increase on the ordinary dividend, and about 43.7% of forecast earnings per share.
| Metric | Q1 FY3/2027 | Q1 FY3/2026 | Change |
|---|---|---|---|
| Revenue (¥ million) | 8,280 | 8,146 | +1.6% |
| Gross profit (¥ million) | 1,715 | 1,193 | +43.8% |
| Gross margin | 20.7% | 14.6% | +6.1 pt |
| SG&A expenses (¥ million) | 890 | 842 | +5.7% |
| Operating profit (¥ million) | 824 | 351 | +134.9% |
| Operating margin | 10.0% | 4.3% | +5.7 pt |
| Ordinary profit (¥ million) | 787 | 331 | +138.0% |
| Net profit attrib. to owners of parent (¥ million) | 536 | 203 | +163.2% |
| Comprehensive income (¥ million) | 516 | 191 | +169.7% |
| EPS (¥) | 30.37 | 11.55 | +162.9% |
| Civil Engineering — revenue (¥ million) | 5,961 | 5,314 | +12.2% |
| Civil Engineering — segment profit (¥ million) | 1,351 | 904 | +49.4% |
| Building Construction — revenue (¥ million) | 2,297 | 2,807 | −18.2% |
| Building Construction — segment profit (¥ million) | 346 | 275 | +25.9% |
| Orders received (¥ million) | 7,958 | — | +98.7% |
| Civil Engineering — orders received (¥ million) | 6,271 | — | +452.5% |
| Building Construction — orders received (¥ million) | 1,599 | — | −42.5% |
| Total assets (¥ million) | 36,982 | 35,613 | +3.8% |
| Net assets (¥ million) | 13,267 | 13,143 | +0.9% |
| Equity ratio | 35.9% | 36.9% | −1.0 pt |
| FY3/2027 guidance — revenue (¥ million) | 33,128 | — | +2.8% |
| FY3/2027 guidance — operating profit (¥ million) | 1,660 | — | +4.5% |
| FY3/2027 guidance — ordinary profit (¥ million) | 1,480 | — | +0.2% |
| FY3/2027 guidance — net profit (¥ million) | 1,010 | — | +1.7% |
| FY3/2027 guidance — EPS (¥) | 57.18 | — | — |
| Annual dividend per share (¥) | 25.00 | 22.00 | +13.6% |
JapanStockPulse provides informational content only and does not constitute investment advice. Figures are taken from the company's published earnings short report and may be subject to subsequent revision.