A first quarter with nothing to compare against
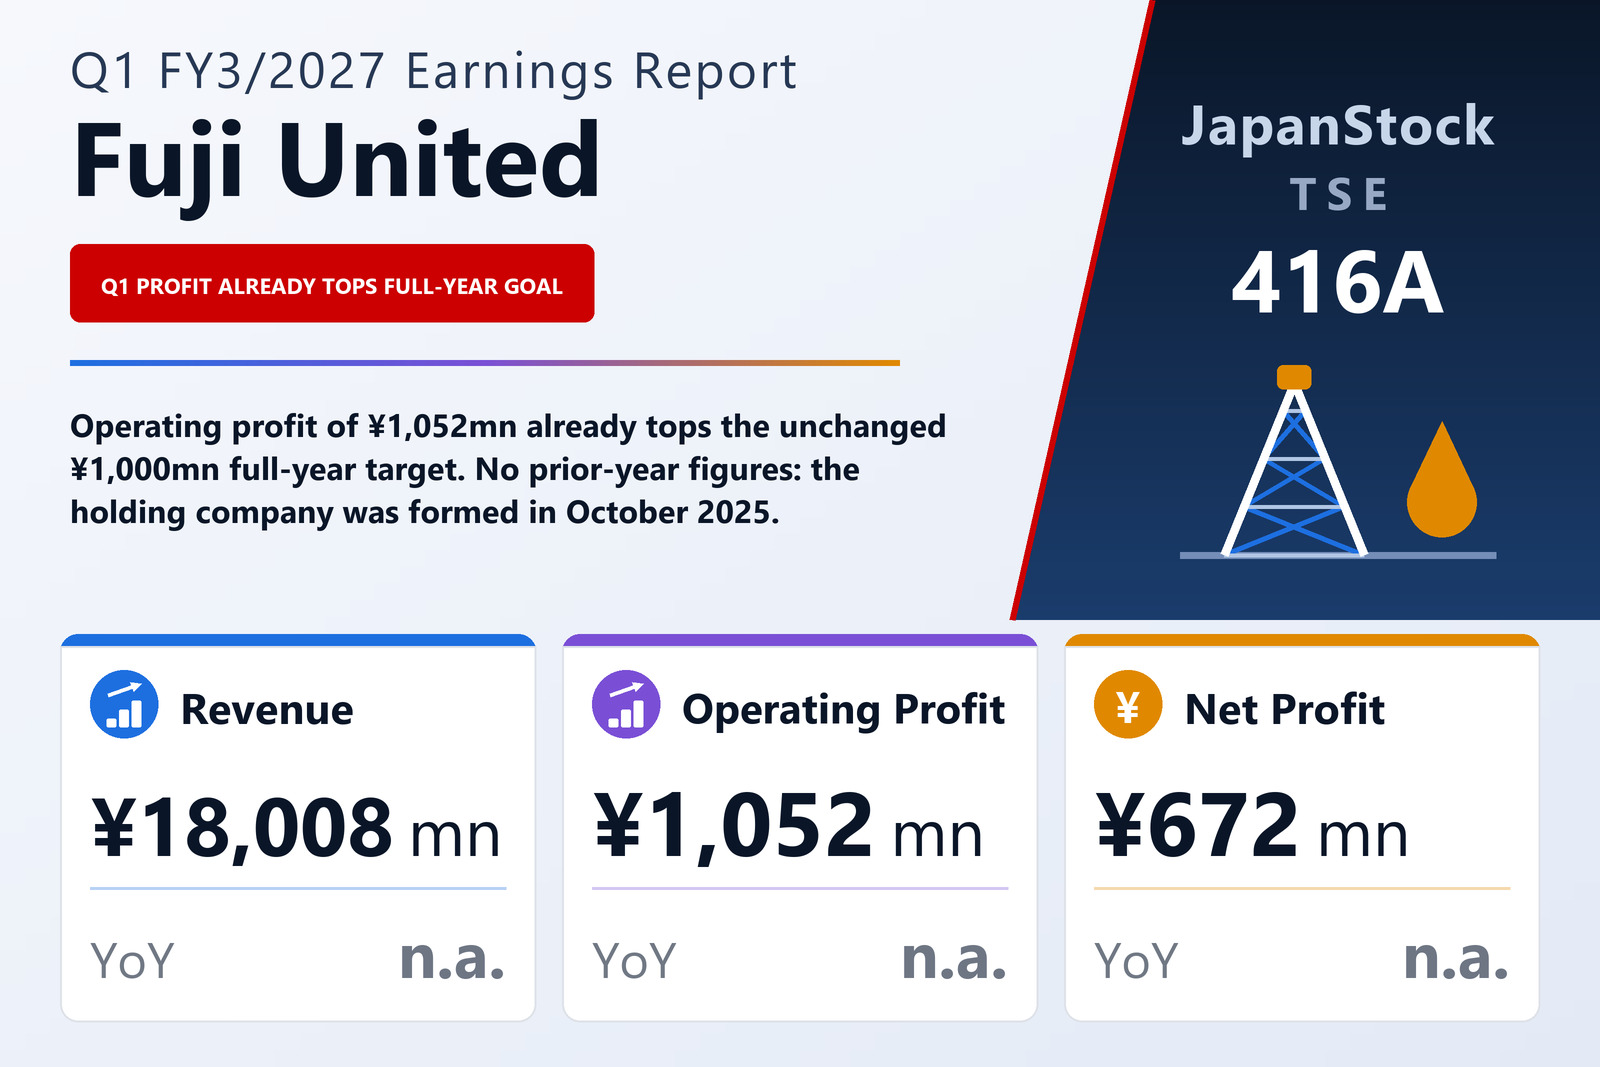
FUJI UNITED HOLDINGS COMPANY, LTD. (TSE: 416A), the Tokyo Stock Exchange-listed holding company of a group that sells fuel oil and other petroleum products and runs recycling, household-fuel and equipment-rental businesses in Hokkaido, published consolidated results for the first quarter of FY3/2027, April 1 to June 30, 2026, on August 7, 2026, under Japanese GAAP. Revenue was ¥18,008 million, operating profit ¥1,052 million, ordinary profit ¥1,040 million and net profit attributable to owners of the parent ¥672 million, or ¥101.84 per share. The quarterly statements were not reviewed by an auditor.
The company was established on October 1, 2025 through a sole share transfer, becoming the wholly owning parent of Fuji Kosan Company, Ltd., and says its scope of consolidation is substantively the same as Fuji Kosan's was before the transfer. Because the holding company did not exist a year earlier, the filing prints no prior-year figures and no year-on-year percentages for the quarter. Its narrative compares some items with Fuji Kosan's consolidated results for the first quarter of FY3/2026 but does not give those figures, so no year-on-year comparison is made here.
A 12.9% gross margin, a 5.8% operating margin
Cost of sales was ¥15,692 million, leaving gross profit of ¥2,316 million, a gross margin of 12.9%. Selling, general and administrative expenses took ¥1,263 million, 7.0% of revenue, so operating profit came to ¥1,052 million, a margin of 5.8%. Depreciation for the quarter was ¥266 million and goodwill amortisation ¥18 million; no cash-flow statement was prepared for the quarter.
Below the operating line the amounts were small. Non-operating income of ¥40 million, mainly ¥21 million of fees for services the group performs under contract and ¥12 million of rent on fixed assets, was more than offset by ¥53 million of non-operating expenses, including ¥20 million of costs for those services, ¥12 million of interest and ¥11 million of rental costs, leaving ordinary profit at ¥1,040 million. Extraordinary items amounted to a ¥1 million gain on the sale of fixed assets. Pre-tax profit of ¥1,041 million bore income taxes of ¥369 million, an effective rate of about 35.4%, for net profit of ¥672 million. Comprehensive income was ¥676 million, including a ¥4 million valuation gain on securities.
Petroleum supplied nine-tenths of revenue
Under the 2026–2028 medium-term plan it published in May, the group sorts its businesses into three domains: Green, Energy and Infrastructure. The Petroleum segment, the whole of the Energy domain, produced external revenue of ¥16,245 million, 90.2% of the group total, and segment profit of ¥941 million, 83.3% of the ¥1,130 million earned by the five segments before ¥77 million of unallocated corporate costs. The company says tension in the Middle East over Iran made crude oil and petroleum-product prices swing sharply and pushed market prices up; prices began to settle gradually from June but remained unstable. The group sold through direct fuel-oil sales, small-lot deliveries and service stations, and says it concentrated on keeping supply stable, pricing appropriately, securing procurement and making deliveries more efficient. The segment finished ahead of the company's plan. Across the group, fuel oil accounted for ¥14,613 million of revenue, ¥14,234 million of it in Petroleum.
The Rental segment, which makes up the Infrastructure domain and is based in central Hokkaido, had revenue of ¥593 million, of which ¥414 million is classed as other revenue rather than revenue from contracts with customers, and segment profit of ¥69 million, also ahead of plan. The company says the value of public-works contracts in Hokkaido rose 7.1% year on year in April to June and 6.4% in the Ishikari district, its core area, but that the rise was driven largely by Hokkaido Shinkansen-related work while growth in national, prefectural and municipal spending slowed; it responded by concentrating sales effort on contractors winning private-sector work.
Green domain: two segments beat plan, one stayed in the red
Recycling, which operates across Hokkaido, had revenue of ¥467 million and segment profit of ¥85 million, ahead of plan. The company credits a large oil-spill response contract in its environmental recycling work, and higher selling prices for recycled heavy fuel oil and for ferrous and non-ferrous scrap in its resource recycling work. Home Energy, which retails LPG, kerosene and other household fuels in central Hokkaido, had revenue of ¥526 million and segment profit of ¥49 million, also ahead of plan, which the company attributes to cost cutting. It describes a hard market: energy prices jumped on Middle East tension and the weak yen, food and service prices kept rising, and households stayed careful with spending. It says it won new customers, mainly in detached houses, and pursued new business such as green products and home renovation.
Environmental Energy, renamed this quarter from Renewable Energy with no other change, had revenue of ¥175 million and a segment loss of ¥16 million, worse than planned; sales volume missed plan because actual demand did not grow as expected. The company nonetheless says sales volume rose by more than 140% on the prior year and that the loss was smaller than a year earlier, without giving prior-year figures. The segment sells biofuels, which the company describes as drop-in fuels usable in existing combustion engines, recycled heavy fuel oil made from used lubricants and other waste, and carbon-offset fuel; it exhibited at an environmental trade show at Tokyo Big Sight in May and plans to launch a service website from the second quarter. Together the three Green-domain segments contributed ¥1,168 million of revenue and ¥118 million of segment profit. In April two group companies, one of them Fuji Kosan, also began putting into practice a resource-recycling model that uses spent toner and food-recycling by-products in road infrastructure, for which a patent application has been filed.
More cash after the dividend
Total assets rose ¥794 million from the March year-end to ¥23,147 million. Cash and deposits increased ¥701 million to ¥5,774 million and fixed assets ¥412 million to ¥8,888 million, while notes, accounts receivable and contract assets fell ¥532 million to ¥7,241 million; merchandise and finished goods rose to ¥787 million from ¥582 million. Liabilities rose ¥322 million to ¥12,895 million, chiefly a ¥222 million increase in notes and accounts payable, to ¥6,808 million, and a ¥114 million increase in lease obligations. Borrowings and bonds totalled ¥2,464 million, well below the cash balance. Net assets rose ¥471 million to ¥10,251 million, as net profit of ¥672 million outweighed ¥204 million of dividends paid, and the equity ratio edged up to 44.3% from 43.8%.
A corrected first half, and a full-year target the quarter has already passed
Alongside the results the company corrected the first-half forecast it had published on May 15, 2026, after finding an error in the process of aggregating the consolidated figures used to calculate it. Revenue guidance for the six months to September 30, 2026 stays at ¥34,000 million, but operating and ordinary profit guidance rise to ¥420 million from ¥300 million (+40.0%) and net profit guidance to ¥250 million from ¥150 million (+66.7%), or ¥37.88 per share against ¥22.72. The full-year forecast is unchanged: revenue of ¥80,000 million (+6.6%), operating profit of ¥1,000 million (−15.5%), ordinary profit of ¥950 million (−20.0%) and net profit of ¥600 million (−17.4%), or ¥90.92 per share. The company says it is keeping its original plan for both periods because uncertainty, including the situation in the Middle East, persists, and that it will disclose promptly if an upward revision becomes necessary.
Set against the first quarter, the guidance leaves nothing for the rest of the year. Operating profit of ¥1,052 million is already 105% of the full-year target and two and a half times the first-half figure, so the forecasts imply an operating loss of about ¥632 million in the July–September quarter and a small loss over the remaining nine months as a whole; net profit of ¥672 million likewise exceeds both the ¥250 million first-half and ¥600 million full-year targets. Revenue, by contrast, is 22.5% of the full-year figure. The filing gives no quarterly breakdown of the forecast and no reason why profit would fall back beyond the uncertainty it cites.
For FY3/2026 the company paid a year-end dividend of ¥31.00 per share, the only payment recorded for that year because it was formed part-way through. For FY3/2027 it forecasts ¥31.00 at the interim and ¥31.00 at the year-end, ¥62.00 in total, unchanged from its previous forecast and equal to 68.2% of forecast earnings per share. Shares issued were 6,620,259 at June 30, 2026, including 20,732 treasury shares.
| Metric | Q1 FY3/2027 | Q1 FY3/2026 | Change |
|---|---|---|---|
| Revenue (¥ million) | 18,008 | — | — |
| Gross profit (¥ million) | 2,316 | — | — |
| Gross margin | 12.9% | — | — |
| SG&A expenses (¥ million) | 1,263 | — | — |
| Operating profit (¥ million) | 1,052 | — | — |
| Operating margin | 5.8% | — | — |
| Ordinary profit (¥ million) | 1,040 | — | — |
| Net profit attrib. to owners of parent (¥ million) | 672 | — | — |
| Comprehensive income (¥ million) | 676 | — | — |
| EPS (¥) | 101.84 | — | — |
| Petroleum — revenue (¥ million) | 16,245 | — | — |
| Petroleum — segment profit (¥ million) | 941 | — | — |
| Rental — revenue (¥ million) | 593 | — | — |
| Rental — segment profit (¥ million) | 69 | — | — |
| Recycling — revenue (¥ million) | 467 | — | — |
| Recycling — segment profit (¥ million) | 85 | — | — |
| Home Energy — revenue (¥ million) | 526 | — | — |
| Home Energy — segment profit (¥ million) | 49 | — | — |
| Environmental Energy — revenue (¥ million) | 175 | — | — |
| Environmental Energy — segment profit (¥ million) | −16 | — | — |
| Total assets (¥ million) | 23,147 | 22,353 | +3.6% |
| Cash and deposits (¥ million) | 5,774 | 5,073 | +13.8% |
| Net assets (¥ million) | 10,251 | 9,780 | +4.8% |
| Equity ratio | 44.3% | 43.8% | +0.5 pt |
| FY3/2027 guidance — revenue (¥ million) | 80,000 | — | +6.6% |
| FY3/2027 guidance — operating profit (¥ million) | 1,000 | — | −15.5% |
| FY3/2027 guidance — ordinary profit (¥ million) | 950 | — | −20.0% |
| FY3/2027 guidance — net profit (¥ million) | 600 | — | −17.4% |
| FY3/2027 guidance — EPS (¥) | 90.92 | — | — |
| Annual dividend per share (¥) | 62.00 | 31.00 | n.m. |
JapanStockPulse provides informational content only and does not constitute investment advice. Figures are taken from the company's published earnings short report and may be subject to subsequent revision.