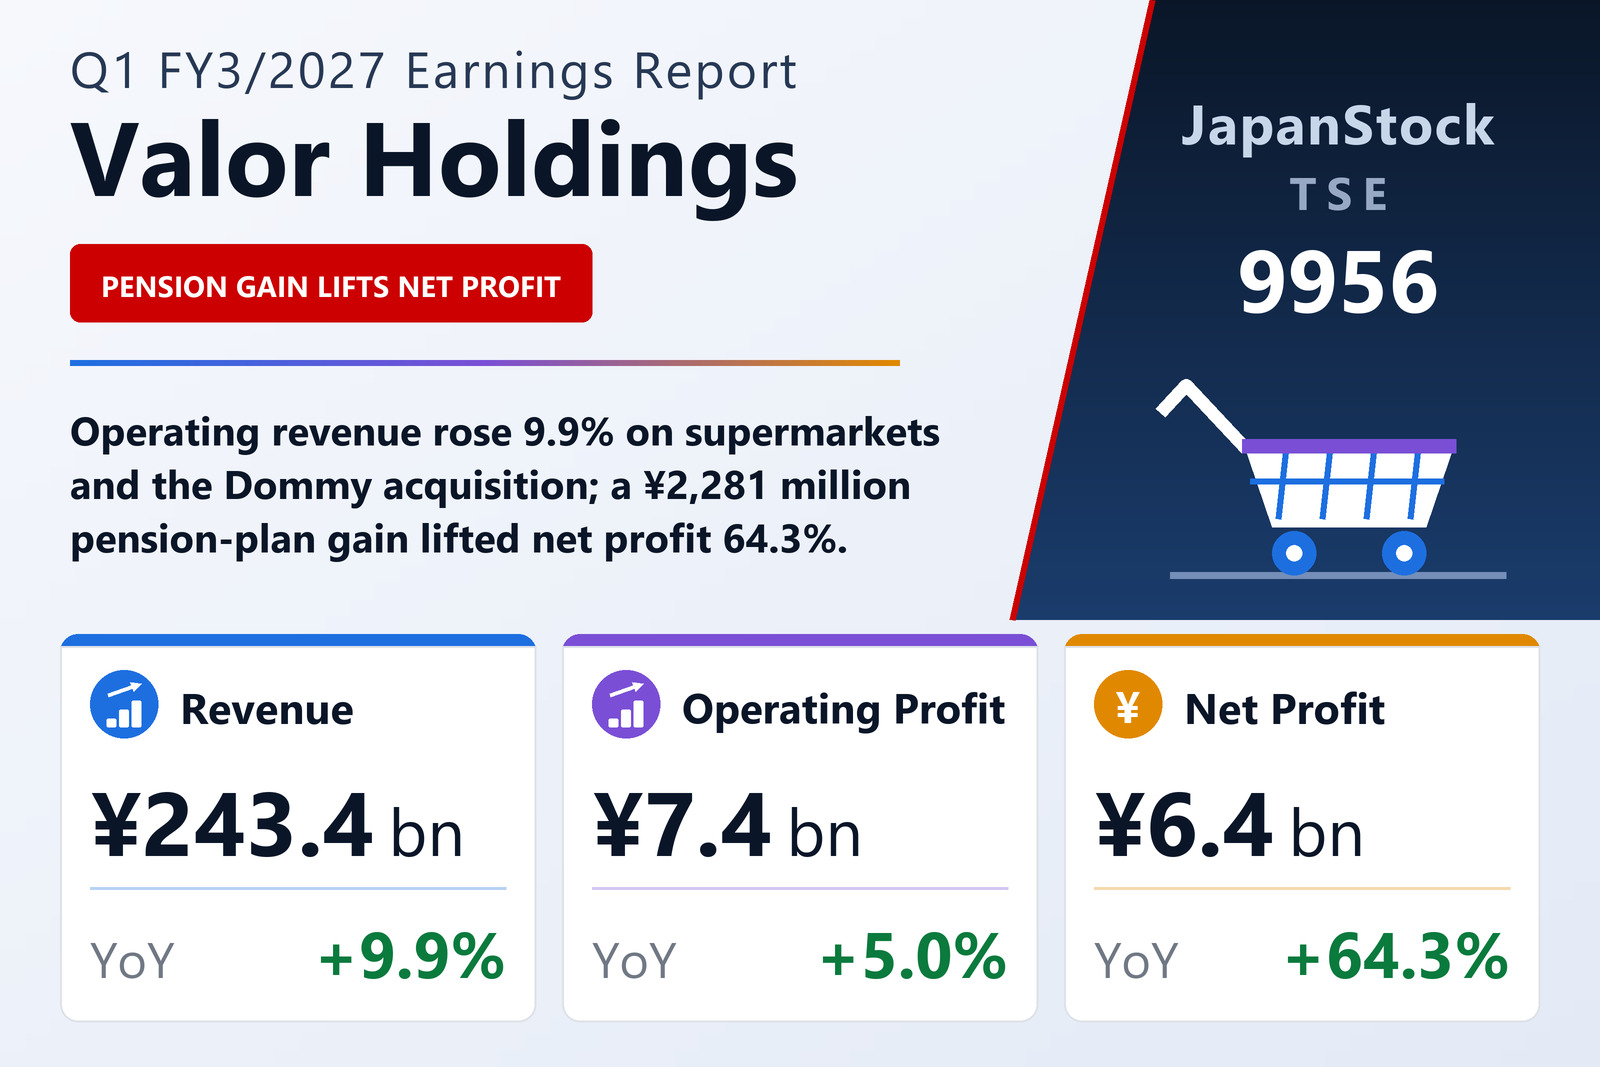
Supermarkets and the Dommy acquisition carried a 9.9% revenue rise
Valor Holdings Co., Ltd. (TSE: 9956), the retail group that runs supermarkets, drugstores, home centres, pet shops and sports clubs, published consolidated results for the first quarter of the fiscal year ending March 2027 — April 1 to June 30, 2026 — on August 7, 2026 under Japanese GAAP. Operating revenue rose 9.9% to ¥243,433 million, operating profit 5.0% to ¥7,398 million, ordinary profit 8.6% to ¥7,838 million and profit attributable to owners of the parent 64.3% to ¥6,365 million, or ¥120.85 per share against ¥73.58. The shares are listed on the Tokyo and Nagoya stock exchanges, and the group operated 1,557 stores at the end of the quarter.
The filing names three sources of the revenue growth: higher existing-store sales in the supermarket business; the addition of Dommy and its subsidiaries, which became wholly owned on October 21, 2025 and so were absent from the prior-year quarter; and new drugstore openings. At Valor Co., Ltd., the group's core supermarket company, average spend per customer rose 2.7% and customer numbers 0.9%, for existing-store sales growth of 3.6%.
Gross profit kept pace with sales; costs and head-office items did not
Operating revenue is made up of net sales of ¥235,918 million, up 9.9%, and other operating revenue of ¥7,515 million against ¥6,902 million. Gross profit on net sales rose 10.2% to ¥64,883 million, a margin of 27.5% against 27.4%, and Valor Co.'s own gross margin rose 0.4 points to 28.4%. Selling, general and administrative expenses, however, rose 10.7% to ¥65,000 million, which the filing attributes to new stores, personnel, logistics and system-related costs. Revenue growth and the higher gross profit absorbed that increase, but only just: the operating margin on operating revenue slipped 0.2 points to 3.0%.
The segment note shows where the gap between segment and group profit opened. The reportable segments and the Other category together earned ¥11,208 million against ¥9,207 million, about 21.7% more. Two reconciling items pulled the consolidated figure back down: intersegment eliminations deepened to −¥4,867 million from −¥4,406 million, and the corporate line — mainly dividend income from group companies less general expenses not allocated to segments — added ¥1,057 million against ¥2,243 million, a fall of 52.9%. The filing does not explain the decline in that corporate line.
A retirement-benefit plan gain did most of the work below the line
Non-operating income rose 41.0% to ¥1,393 million, including a ¥306 million insurance surrender refund, while non-operating expenses rose 17.0% to ¥953 million, with interest expense up to ¥455 million from ¥307 million. Ordinary profit therefore rose 8.6% to ¥7,838 million, although the ordinary margin eased 0.1 points to 3.2%.
The large move came from extraordinary items. Extraordinary income was ¥2,745 million against ¥17 million, of which ¥2,281 million was a gain on a revision of the retirement-benefit plan, with gains of ¥220 million on the sale of fixed assets and ¥202 million on the sale of investment securities. Extraordinary losses fell 84.7% to ¥49 million; the prior-year quarter had carried a ¥212 million write-down of shares in an affiliate. Pre-tax profit rose 52.4% to ¥10,534 million, and the pension gain alone accounts for roughly 63% of that ¥3,620 million increase. Income taxes rose 41.9% to ¥3,601 million and profit attributable to non-controlling interests 13.3% to ¥567 million. On the balance sheet, the net defined benefit liability fell to ¥2,286 million from ¥7,098 million.
Supermarkets led; pet shops were the one segment to lose profit
Supermarkets, much the largest segment, grew revenue 15.5% to ¥144,037 million and segment profit 26.0% to ¥6,611 million, including part of Dommy's results. The filing credits existing-store growth at Valor Co., a new store in Fukui opened in April 2026, eight renovated stores, and higher sales and profit at three supermarket subsidiaries, including Tachiya and Yamata. The segment ended the quarter with 366 stores.
Drugstores grew revenue 1.6% to ¥46,842 million and profit 3.5% to ¥730 million. Existing-store sales fell 1.5% as customer numbers dropped 4.2% while spend per customer rose 2.8%; new openings, a strong prescription-dispensing business, lower waste losses and head-office cost reviews made up the difference. The segment had 581 stores, 241 of them handling prescriptions. Home Centres grew revenue 0.8% to ¥33,142 million and profit 5.1% to ¥1,859 million; existing-store sales rose 1.1% on spend per customer up 4.4% and customer numbers down 3.1%, and the filing cites gross-margin improvement from joint purchasing, price revisions and private-brand sales.
Pet Shops grew revenue 6.0% to ¥9,264 million but profit fell 25.2% to ¥63 million, as higher personnel costs, cashless-payment fees and new-store start-up costs at the Amigo chain outweighed the rise in gross profit. Sports Clubs grew revenue 7.8% to ¥2,987 million and swung to a profit of ¥60 million from a loss of ¥23 million, helped by two clubs taken over in April 2026. Distribution-related businesses — logistics and supplies for the group and outside customers — grew revenue 11.3% to ¥5,541 million and profit 19.8% to ¥1,470 million, and Other, which includes property leasing, the credit-card business and clothing sales, grew revenue 22.1% to ¥1,618 million and profit 111.3% to ¥413 million.
Debt shifted from bonds to bank loans; a share issue and split are under way
Total assets rose ¥12,193 million to ¥527,600 million from March 31, 2026, chiefly on merchandise up ¥5,897 million, receivables up ¥3,915 million and property, plant and equipment up ¥4,374 million; cash and deposits fell to ¥29,569 million from ¥32,983 million. Liabilities rose ¥7,502 million to ¥319,587 million: bonds fell by ¥10,014 million while long-term borrowings rose ¥11,154 million and trade payables ¥7,660 million. Net assets reached ¥208,013 million and the equity ratio held at 35.9%. The year-end comparatives have been restated to reflect the finalised purchase-price allocation for Dommy, which cut the goodwill recognised on that deal to ¥3,406 million from ¥4,442 million.
On June 30, 2026 the company decided on a new share issue and a secondary offering to fund supermarket, drugstore and home-centre openings and food plants. A public offering of 4,694,600 new shares was paid in on July 15, 2026, and a third-party allotment of 704,100 shares is scheduled for payment on August 13, 2026. The company also signed a capital and business alliance with Kohnan Shoji Co., Ltd. covering mutual supply of private-brand goods, logistics, store development and personnel, and will split each share into two with effect from October 1, 2026.
Guidance unchanged; dividend raised on a pre-split basis
Full-year guidance for the year to March 2027 is unchanged from May 13, 2026: operating revenue of ¥1,000,000 million, up 8.2%, operating profit of ¥28,000 million, up 1.5%, ordinary profit of ¥30,500 million, up 1.6%, and net profit of ¥16,500 million, up 0.1%. The first quarter delivered 26.4% of the operating-profit target and, thanks to the pension gain, 38.6% of the net-profit target. For the first half the company expects operating revenue of ¥506,000 million, up 12.3%, and operating profit of ¥14,400 million, up 2.5%. Forecast full-year EPS of ¥146.11 reflects the new shares and the split; without the split it would be ¥292.23.
The dividend forecast, raised on June 30, 2026, is an interim dividend of ¥40.00 and a year-end dividend of ¥20.00 after the split — equivalent to ¥40.00 before it, for an annual ¥80.00 on a pre-split basis against ¥74.00 for the year to March 2026. The quarterly financial statements had not yet been reviewed by the auditor at release; the company plans to republish the report with the review report attached on August 14, 2026.
| Metric | Q1 FY3/2027 | Q1 FY3/2026 | Change |
|---|---|---|---|
| Operating revenue (¥ million) | 243,433 | 221,546 | +9.9% |
| Net sales (¥ million) | 235,918 | 214,643 | +9.9% |
| Gross profit (¥ million) | 64,883 | 58,859 | +10.2% |
| Gross margin | 27.5% | 27.4% | +0.1 pt |
| SG&A expenses (¥ million) | 65,000 | 58,716 | +10.7% |
| Operating profit (¥ million) | 7,398 | 7,045 | +5.0% |
| Operating margin | 3.0% | 3.2% | −0.2 pt |
| Ordinary profit (¥ million) | 7,838 | 7,218 | +8.6% |
| Pre-tax profit (¥ million) | 10,534 | 6,914 | +52.4% |
| Net profit attrib. to owners of parent (¥ million) | 6,365 | 3,875 | +64.3% |
| EPS (¥) | 120.85 | 73.58 | +64.2% |
| Supermarkets — revenue (¥ million) | 144,037 | 124,738 | +15.5% |
| Supermarkets — segment profit (¥ million) | 6,611 | 5,248 | +26.0% |
| Drugstores — revenue (¥ million) | 46,842 | 46,110 | +1.6% |
| Drugstores — segment profit (¥ million) | 730 | 706 | +3.5% |
| Home Centres — revenue (¥ million) | 33,142 | 32,882 | +0.8% |
| Home Centres — segment profit (¥ million) | 1,859 | 1,769 | +5.1% |
| Pet Shops — revenue (¥ million) | 9,264 | 8,738 | +6.0% |
| Pet Shops — segment profit (¥ million) | 63 | 84 | −25.2% |
| Sports Clubs — revenue (¥ million) | 2,987 | 2,771 | +7.8% |
| Sports Clubs — segment profit (¥ million) | 60 | −23 | loss to profit |
| Distribution-Related — revenue (¥ million) | 5,541 | 4,979 | +11.3% |
| Distribution-Related — segment profit (¥ million) | 1,470 | 1,227 | +19.8% |
| Other — revenue (¥ million) | 1,618 | 1,325 | +22.1% |
| Other — segment profit (¥ million) | 413 | 195 | +111.3% |
| Total assets (¥ million) | 527,600 | 515,407 | +2.4% |
| Net assets (¥ million) | 208,013 | 203,323 | +2.3% |
| Equity ratio | 35.9% | 35.9% | unchanged |
| FY3/2027 guidance — operating revenue (¥ million) | 1,000,000 | — | +8.2% |
| FY3/2027 guidance — operating profit (¥ million) | 28,000 | — | +1.5% |
| FY3/2027 guidance — ordinary profit (¥ million) | 30,500 | — | +1.6% |
| FY3/2027 guidance — net profit (¥ million) | 16,500 | — | +0.1% |
| Annual dividend per share, pre-split basis (¥) | 80.00 | 74.00 | +8.1% |
JapanStockPulse provides informational content only and does not constitute investment advice. Figures are taken from the company's published earnings short report and may be subject to subsequent revision.