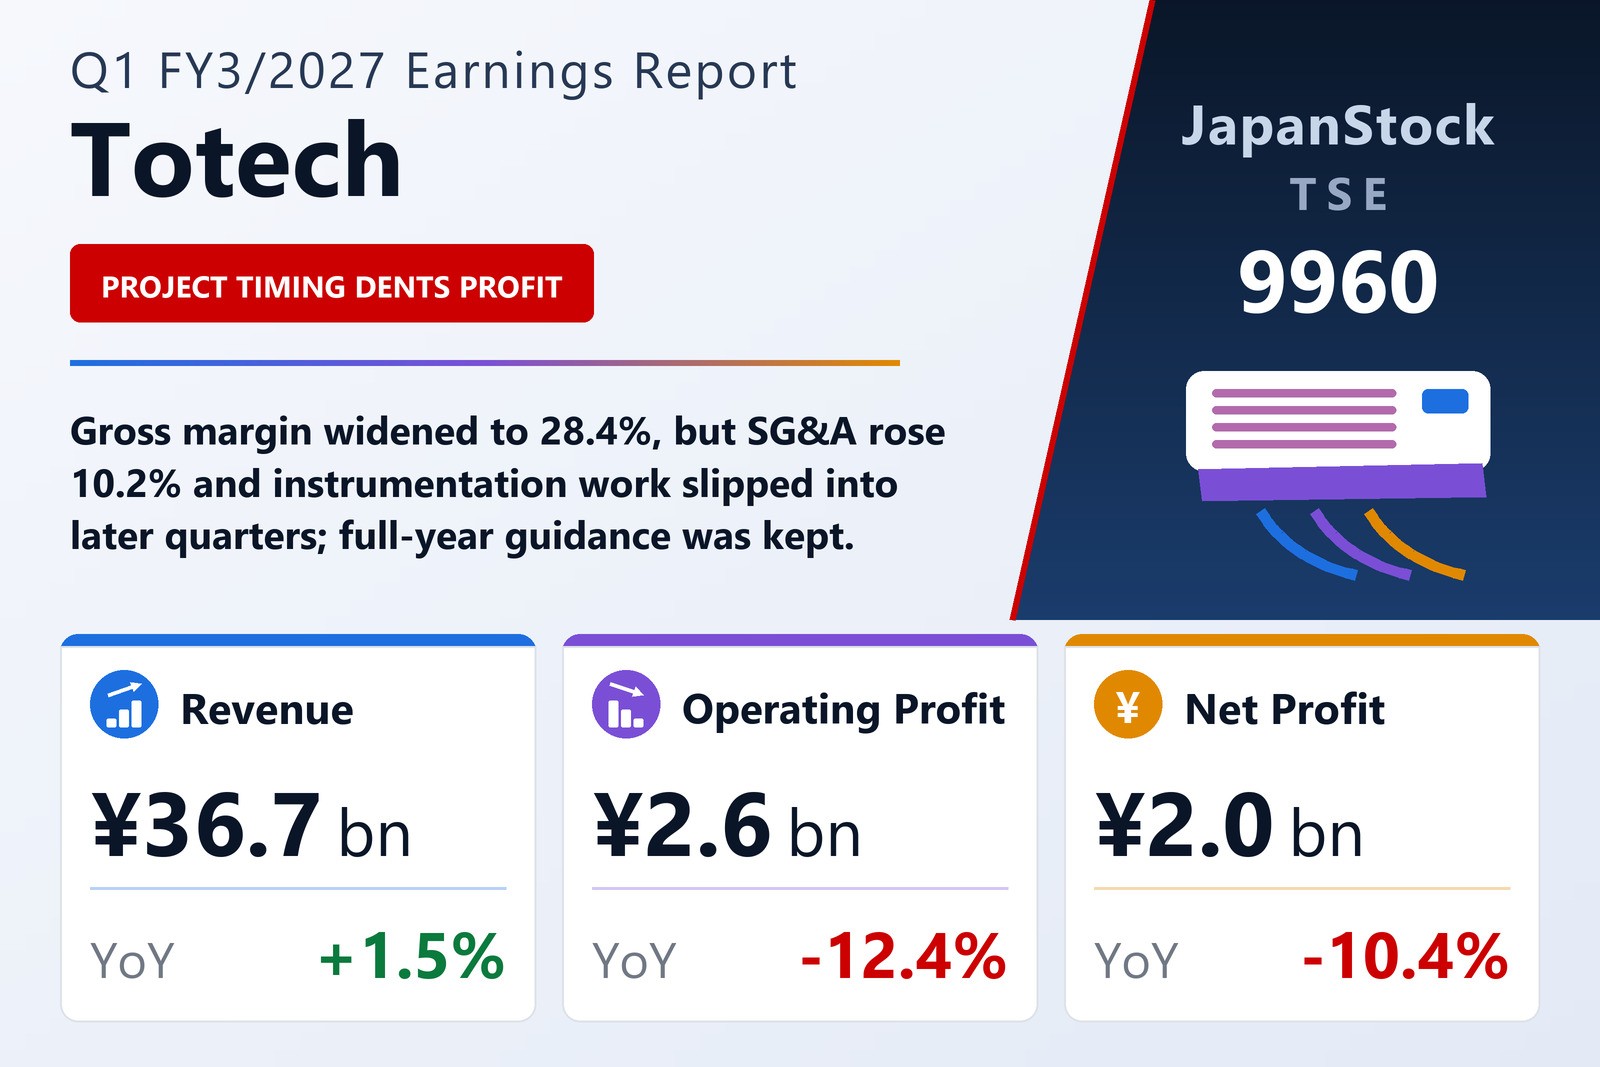
Revenue edged up 1.5%, while operating profit fell 12.4%
Totech Corp. (TSE: 9960), which sells air-conditioning, control and building equipment and designs and installs instrumentation, piping and electrical works, published consolidated results for the first quarter of FY3/2027 — the three months from April 1 to June 30, 2026 — on August 7, 2026 under Japanese GAAP. Revenue rose 1.5% to ¥36,691 million, but operating profit fell 12.4% to ¥2,601 million, ordinary profit 9.5% to ¥2,977 million and profit attributable to owners of the parent 10.4% to ¥1,978 million, for earnings of ¥48.24 per share against ¥53.63. The filing lists the Tokyo Stock Exchange as the company's exchange.
The decline did not come from pricing or project margins. Cost of sales rose only 0.7% to ¥26,260 million, so gross profit grew faster than revenue — up 3.5% to ¥10,430 million — and the gross margin widened from 27.9% to 28.4%. The whole of the fall sits in overheads: selling, general and administrative expenses rose 10.2% to ¥7,829 million, an increase of ¥723 million against a gross-profit gain of ¥356 million. The operating margin therefore narrowed from 8.2% to 7.1%.
Two causes, both named in the filing: project timing and hiring
The company gives two reasons for the lower operating profit. First, instrumentation work — which the filing calls the main source of the group's profit — kept winning orders, but as projects became larger and longer, progress that would have been booked in the first quarter shifted into the second quarter and beyond, moving revenue recognition out of the period. Product sales, by contrast, were strong in both revenue and profit. Second, SG&A rose because Totech expanded its new-graduate hiring and group companies raised base pay, spending the company describes as building a foundation for medium- to long-term growth under its second medium-term management plan, which began this fiscal year.
Management says orders received and the order backlog remained firm, citing a supplementary presentation released the same day; this filing does not print those figures, and it does not quantify how much revenue shifted out of the quarter. It says the company aims to meet its full-year targets as construction progress catches up.
Below the operating line, higher dividends received softened the fall
Non-operating income rose to ¥493 million from ¥437 million, mainly because dividends received increased to ¥300 million from ¥210 million, while non-operating expenses were little changed at ¥117 million against ¥115 million. Ordinary profit therefore fell less than operating profit, by 9.5%. There were no extraordinary items, so pre-tax profit equalled ordinary profit at ¥2,977 million. Income taxes were ¥998 million against ¥1,084 million, an effective rate of about 33.5% against 32.9%, leaving net profit attributable to owners down 10.4%. Comprehensive income moved the other way, rising 40.0% to ¥4,806 million from ¥3,432 million, as other comprehensive income of ¥2,827 million — chiefly a ¥2,775 million rise in unrealised gains on securities — came on top of the quarter's profit.
Both segments grew, but external sales grew less
Product Sales, which sells and maintains air-conditioning, control and building equipment, posted revenue of ¥21,626 million, up 2.6%, and segment gross profit of ¥4,871 million, up 7.8%, which the filing attributes to firm orders from urban redevelopment projects. Construction, built around instrumentation work together with piping and electrical works and maintenance, posted revenue of ¥16,171 million, up 2.9%, but segment gross profit of just ¥5,570 million, up 0.4%, citing strong construction demand and proposal-based maintenance orders. Segment profit is measured at the gross-profit level, and the flat Construction figure is consistent with the timing shift the company describes.
Group revenue grew only 1.5% although both segments grew by more, because the segment figures include intersegment sales, which rose to ¥1,119 million from ¥638 million — almost all of it Product Sales selling to the rest of the group (¥1,104 million against ¥592 million). Sales to external customers were ¥20,521 million against ¥20,486 million in Product Sales and ¥16,156 million against ¥15,669 million in Construction. A solar-power business outside the reporting segments added ¥12 million. On the market, the company says construction investment stayed firm in urban redevelopment, data centres and renewable energy, while high materials prices and labour shortages remain ongoing challenges for schedule management and securing construction capacity, and that the direct effect of the Middle East situation on procurement, construction and sales has so far been minor.
Higher securities values lifted the equity ratio to 66.1%
Total assets fell ¥2,102 million to ¥113,018 million from March 31, 2026. Trade receivables and inventories declined by ¥6,953 million, while investment securities rose by ¥4,073 million to ¥25,351 million on higher market values and cash and deposits rose by ¥776 million to ¥12,079 million. Liabilities fell ¥3,099 million to ¥38,350 million: trade payables and electronically recorded obligations fell by ¥3,554 million, income taxes payable by ¥2,679 million and the bonus provision by ¥2,602 million after bonuses were paid, partly offset by increases of ¥2,136 million in deferred tax liabilities, ¥2,049 million in other current liabilities and ¥1,509 million in interest-bearing debt. Net assets rose ¥997 million to ¥74,667 million: retained earnings fell by ¥1,848 million as dividends paid exceeded the quarter's profit, while the valuation difference on securities rose by ¥2,775 million. The equity ratio rose from 64.0% to 66.1%.
One subsidiary, Quantum Automation (Shanghai) Co., Ltd., left the scope of consolidation during the quarter. The prior-year first-quarter figures reflect the finalisation of provisional accounting for a business combination completed on April 1, 2025, which reduced the goodwill from ¥954 million to ¥526 million and added ¥661 million of customer-related assets. Depreciation was ¥386 million against ¥463 million, and goodwill amortisation ¥55 million against ¥77 million.
Guidance held, with a fifth of revenue but a seventh of operating profit booked
Totech left unchanged the full-year FY3/2027 guidance it published on May 14, 2026: revenue of ¥180,000 million (+5.9%), operating profit of ¥18,000 million (+5.1%), ordinary profit of ¥18,500 million (+2.9%) and profit attributable to owners of ¥13,700 million (+4.3%), for earnings per share of ¥334.03. The first quarter delivered 20.4% of guided revenue but 14.5% of guided operating profit and 14.4% of guided net profit, so the plan depends on the delayed instrumentation progress being recognised in the remaining three quarters.
The dividend forecast was also unchanged at an annual ¥128.00 per share, the same total as FY3/2026 but split differently: ¥42.00 at the interim against ¥35.00, and ¥86.00 at the year-end against ¥93.00. That is a payout of about 38% of the guided ¥334.03 of earnings per share.
| Metric | Q1 FY3/2027 | Q1 FY3/2026 | Change |
|---|---|---|---|
| Revenue (¥ million) | 36,691 | 36,161 | +1.5% |
| Gross profit (¥ million) | 10,430 | 10,074 | +3.5% |
| Gross margin | 28.4% | 27.9% | +0.6 pt |
| SG&A expenses (¥ million) | 7,829 | 7,106 | +10.2% |
| Operating profit (¥ million) | 2,601 | 2,968 | −12.4% |
| Operating margin | 7.1% | 8.2% | −1.1 pt |
| Ordinary profit (¥ million) | 2,977 | 3,290 | −9.5% |
| Net profit attrib. to owners of parent (¥ million) | 1,978 | 2,207 | −10.4% |
| EPS (¥) | 48.24 | 53.63 | −10.1% |
| Comprehensive income (¥ million) | 4,806 | 3,432 | +40.0% |
| Product Sales — revenue (¥ million) | 21,626 | 21,079 | +2.6% |
| Product Sales — segment gross profit (¥ million) | 4,871 | 4,518 | +7.8% |
| Construction — revenue (¥ million) | 16,171 | 15,714 | +2.9% |
| Construction — segment gross profit (¥ million) | 5,570 | 5,547 | +0.4% |
| Total assets (¥ million) | 113,018 | 115,120 | −1.8% |
| Net assets (¥ million) | 74,667 | 73,670 | +1.4% |
| Equity ratio | 66.1% | 64.0% | +2.1 pt |
| FY3/2027 guidance — revenue (¥ million) | 180,000 | — | +5.9% |
| FY3/2027 guidance — operating profit (¥ million) | 18,000 | — | +5.1% |
| FY3/2027 guidance — ordinary profit (¥ million) | 18,500 | — | +2.9% |
| FY3/2027 guidance — net profit (¥ million) | 13,700 | — | +4.3% |
| FY3/2027 guidance — EPS (¥) | 334.03 | — | — |
| Annual dividend per share (¥) | 128.00 | 128.00 | unchanged |
JapanStockPulse provides informational content only and does not constitute investment advice. Figures are taken from the company's published earnings short report and may be subject to subsequent revision.