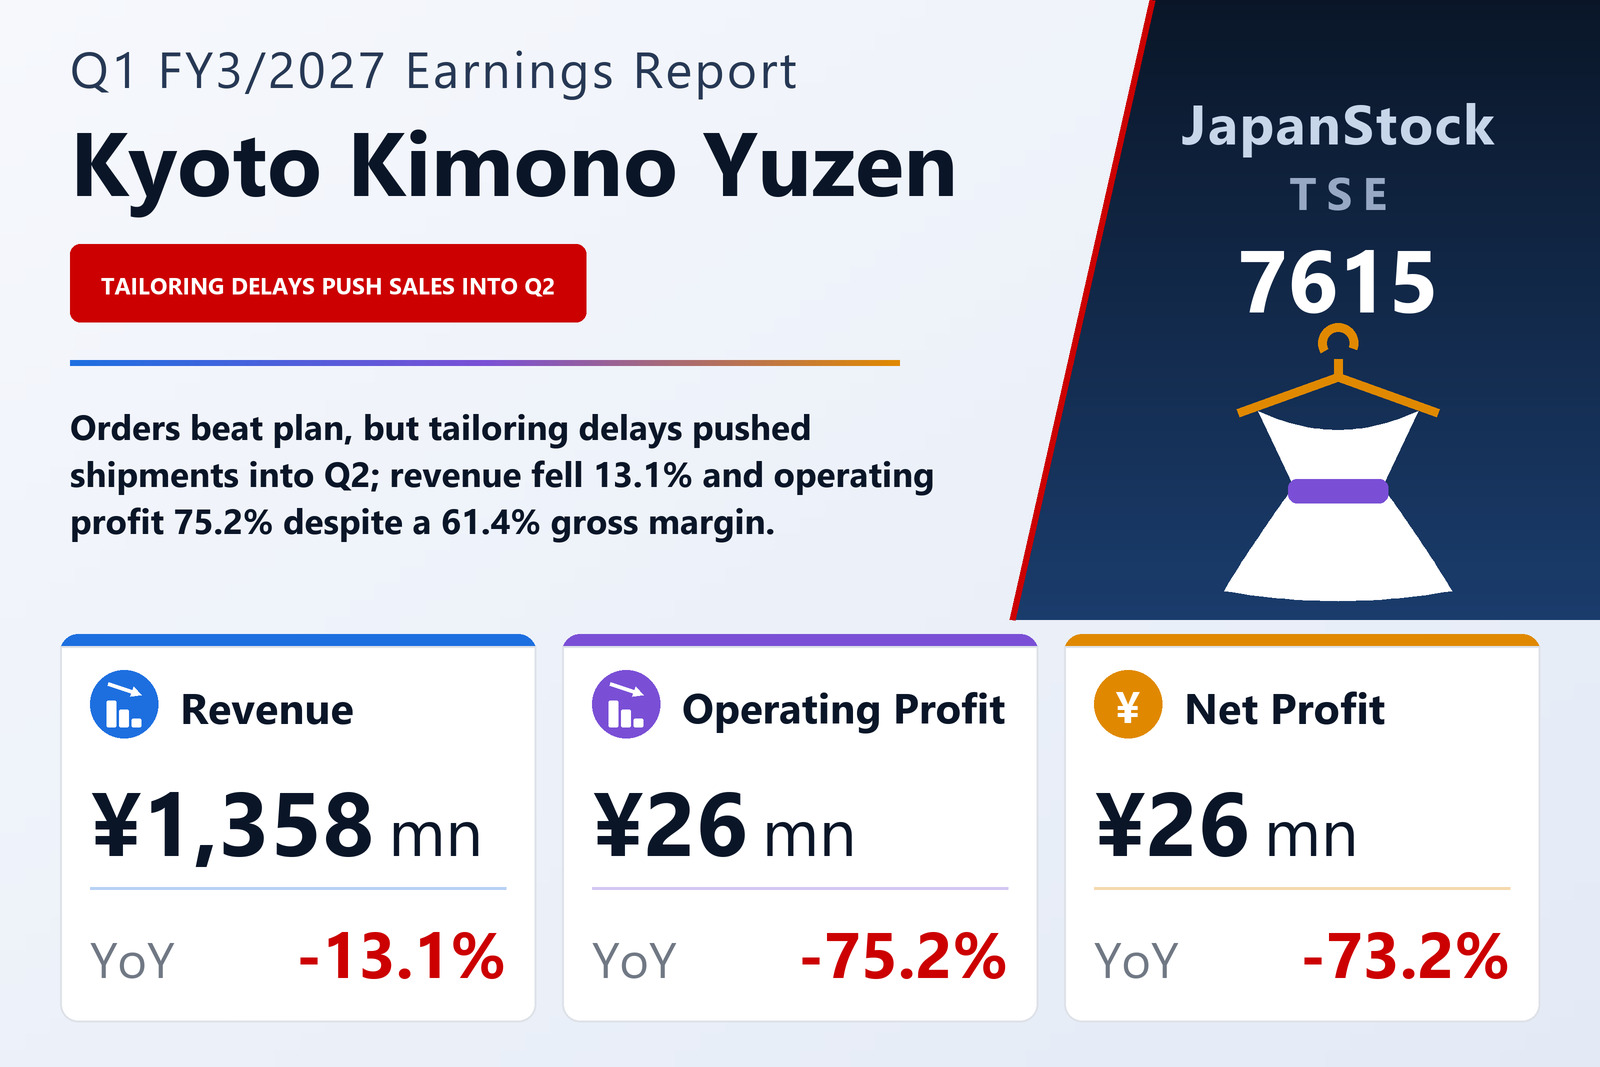
Orders beat plan, but revenue fell 13.1% because kimonos were still being tailored
Kyoto Kimono Yuzen Holdings Co., Ltd. (TSE: 7615), a kimono group that reports a single Japanese-dress (wasō) business spanning general kimono, furisode sales and rental, photography and an online store, published consolidated results for the first quarter of the fiscal year ending March 2027 — April 1 to June 30, 2026 — on August 10, 2026 under Japanese GAAP. Revenue fell 13.1% to ¥1,358 million, operating profit 75.2% to ¥26 million, ordinary profit 74.5% to ¥26 million and profit attributable to owners of the parent 73.2% to ¥26 million, for earnings of ¥1.26 per share against ¥6.92. The shares are listed on the Tokyo Stock Exchange.
The filing's explanation for the revenue decline is one of timing rather than demand. Orders as a whole came in above the company's plan, with furisode orders ahead of last year and general kimono tracking the initial plan. But tailoring the garments after an order is taken required more time, and shipments of part of the merchandise slipped into the second quarter or later, so less of that order intake reached revenue within the quarter. The company states that revenue and every profit line were in line with its initial plan and that progress toward the full-year forecast is on schedule.
A higher gross margin and lower costs could not absorb the lost volume
Cost of sales fell 15.3% to ¥524 million, faster than revenue, so gross profit declined by a smaller 11.7% to ¥833 million and the gross margin widened from 60.4% to 61.4%, a gain the filing attributes to setting selling prices at more appropriate levels. Selling, general and administrative expenses fell 3.7% to ¥807 million; the company cites the cost-structure optimisation it has pursued since last year, partly offset by up-front spending for future growth. The arithmetic is still unforgiving: gross profit fell by about ¥111 million while SG&A fell by only about ¥31 million, so operating profit shrank by roughly ¥80 million and the operating margin dropped from 6.8% to 1.9%. SG&A absorbed about 97% of gross profit in the quarter.
Below the operating line the items are small. Non-operating income rose to ¥1.4 million from ¥0.6 million, including ¥1.0 million of dividends received, and non-operating expenses fell to ¥1.3 million from ¥2.6 million as interest paid dropped to ¥1.3 million from ¥2.3 million, leaving ordinary profit at ¥26 million. The prior-year quarter carried a ¥4.2 million extraordinary loss on the cancellation of lease contracts; this year had none. Income taxes were only ¥0.5 million against ¥2.9 million, thanks to a ¥2.5 million deferred-tax benefit, so net profit of ¥26 million was almost equal to pre-tax profit. Comprehensive income was ¥31 million, down 67.7%, including a ¥5.4 million valuation gain on securities.
Furisode and photography grew; general kimono orders fell
The group has a single reporting segment, so the filing gives no segment table; instead it describes its sales categories, in percentages only. General kimono orders fell 11.7% year on year because of changes to the schedule of sales events, though the company says they tracked its initial plan. Furisode sales and rental benefited from a review of customer-acquisition measures: store visitors rose sharply against both last year and plan, and furisode orders grew 12.2%. Photography sales rose 31.8% as more furisode orders brought in demand for advance portrait shoots, and the online store grew sales 14.8%, led by furisode accessories.
The filing frames the quarter within a turnaround. After an organisational reform and improvement measures drawn up in the fiscal year to March 2025, the group returned to profit in the fiscal year to March 2026; it calls the current year a growth phase, in which it aims to turn the existing kimono business into a stable, repeatable earnings base and to build a new business portfolio. It describes the Japanese economy as recovering moderately, with the outlook clouded by persistent inflation, U.S. policy, financial-market volatility and geopolitical risk.
Earnings per share fell faster than profit because the share count rose by almost half
Earnings per share fell 81.8%, more steeply than the 73.2% drop in net profit, because the average number of shares outstanding rose to 20,699,526 from 14,047,290, an increase of 47.4%. This document does not explain the increase. It notes that shares held by a stock-benefit ESOP (335,800 in the prior-year quarter) were deducted as treasury stock and that the ESOP ended in September 2025. Issued shares stood at 21,614,700 at both March 31 and June 30, 2026, with treasury stock of 915,186 shares at the quarter-end. Diluted earnings per share were ¥1.24.
The balance sheet shrank slightly and the equity ratio rose
Total assets fell 2.5% to ¥7,952 million from March 31, 2026. Current assets were down 3.2% at ¥5,777 million: cash and deposits fell ¥79 million to ¥2,934 million as the company paid its dividend and repaid borrowings, accounts receivable fell ¥70 million and merchandise ¥24 million. Liabilities fell 4.1% to ¥4,854 million, as the bonus provision fell ¥67 million, income taxes payable ¥44 million and short-term borrowings ¥25 million, to ¥224 million, while contract liabilities rose ¥50 million. Current liabilities also include ¥1,160 million of advances received and ¥1,971 million of deposits received, which the filing does not discuss.
Net assets were essentially flat at ¥3,097 million against ¥3,098 million: the ¥26 million of quarterly profit was offset by a ¥31 million dividend payment. Because total assets shrank, the equity ratio rose from 37.9% to 38.9%. Under a resolution of the June 24, 2026 annual meeting, the company reduced its share capital by ¥542 million and transferred the whole amount to other capital surplus, leaving capital at ¥100 million; the filing notes this has no effect on total net assets.
Guidance unchanged, and it already assumes a weaker year
The full-year forecast published on May 11, 2026 was left unchanged. It calls for revenue of ¥6,070 million (+2.0%), operating profit of ¥158 million (−38.9%), ordinary profit of ¥120 million (−53.5%) and profit attributable to owners of the parent of ¥104 million (−52.9%), or ¥5.03 per share. The first quarter delivered about 22% of guided revenue and about a sixth of guided operating profit; the company says that is on plan, and the shipments that slipped out of this quarter fall into the second quarter or later. The dividend forecast is also unchanged: no interim payment and a year-end dividend of ¥1.50, the same as for the fiscal year to March 2026.
As a subsequent event, the board resolved on July 17, 2026 to dispose of 40,600 treasury shares to two directors as restricted-stock compensation, at ¥99 per share for a total of ¥4,019,400, with a disposal date of August 14, 2026.
| Metric | Q1 FY3/2027 | Q1 FY3/2026 | Change |
|---|---|---|---|
| Revenue (¥ million) | 1,358 | 1,563 | −13.1% |
| Gross profit (¥ million) | 833 | 944 | −11.7% |
| Gross margin | 61.4% | 60.4% | +1.0 pt |
| SG&A expenses (¥ million) | 807 | 837 | −3.7% |
| Operating profit (¥ million) | 26 | 106 | −75.2% |
| Operating margin | 1.9% | 6.8% | −4.9 pt |
| Ordinary profit (¥ million) | 26 | 104 | −74.5% |
| Net profit attrib. to owners of parent (¥ million) | 26 | 97 | −73.2% |
| EPS (¥) | 1.26 | 6.92 | −81.8% |
| Comprehensive income (¥ million) | 31 | 97 | −67.7% |
| Average shares outstanding (Q1) | 20,699,526 | 14,047,290 | +47.4% |
| Cash and deposits (¥ million) | 2,934 | 3,013 | −2.6% |
| Total assets (¥ million) | 7,952 | 8,160 | −2.5% |
| Net assets (¥ million) | 3,097 | 3,098 | −0.0% |
| Equity ratio | 38.9% | 37.9% | +1.0 pt |
| FY3/2027 guidance — revenue (¥ million) | 6,070 | — | +2.0% |
| FY3/2027 guidance — operating profit (¥ million) | 158 | — | −38.9% |
| FY3/2027 guidance — ordinary profit (¥ million) | 120 | — | −53.5% |
| FY3/2027 guidance — net profit (¥ million) | 104 | — | −52.9% |
| FY3/2027 guidance — EPS (¥) | 5.03 | — | — |
| Annual dividend per share (¥) | 1.50 | 1.50 | unchanged |
JapanStockPulse provides informational content only and does not constitute investment advice. Figures are taken from the company's published earnings short report and may be subject to subsequent revision.