A tripling driven by credit costs
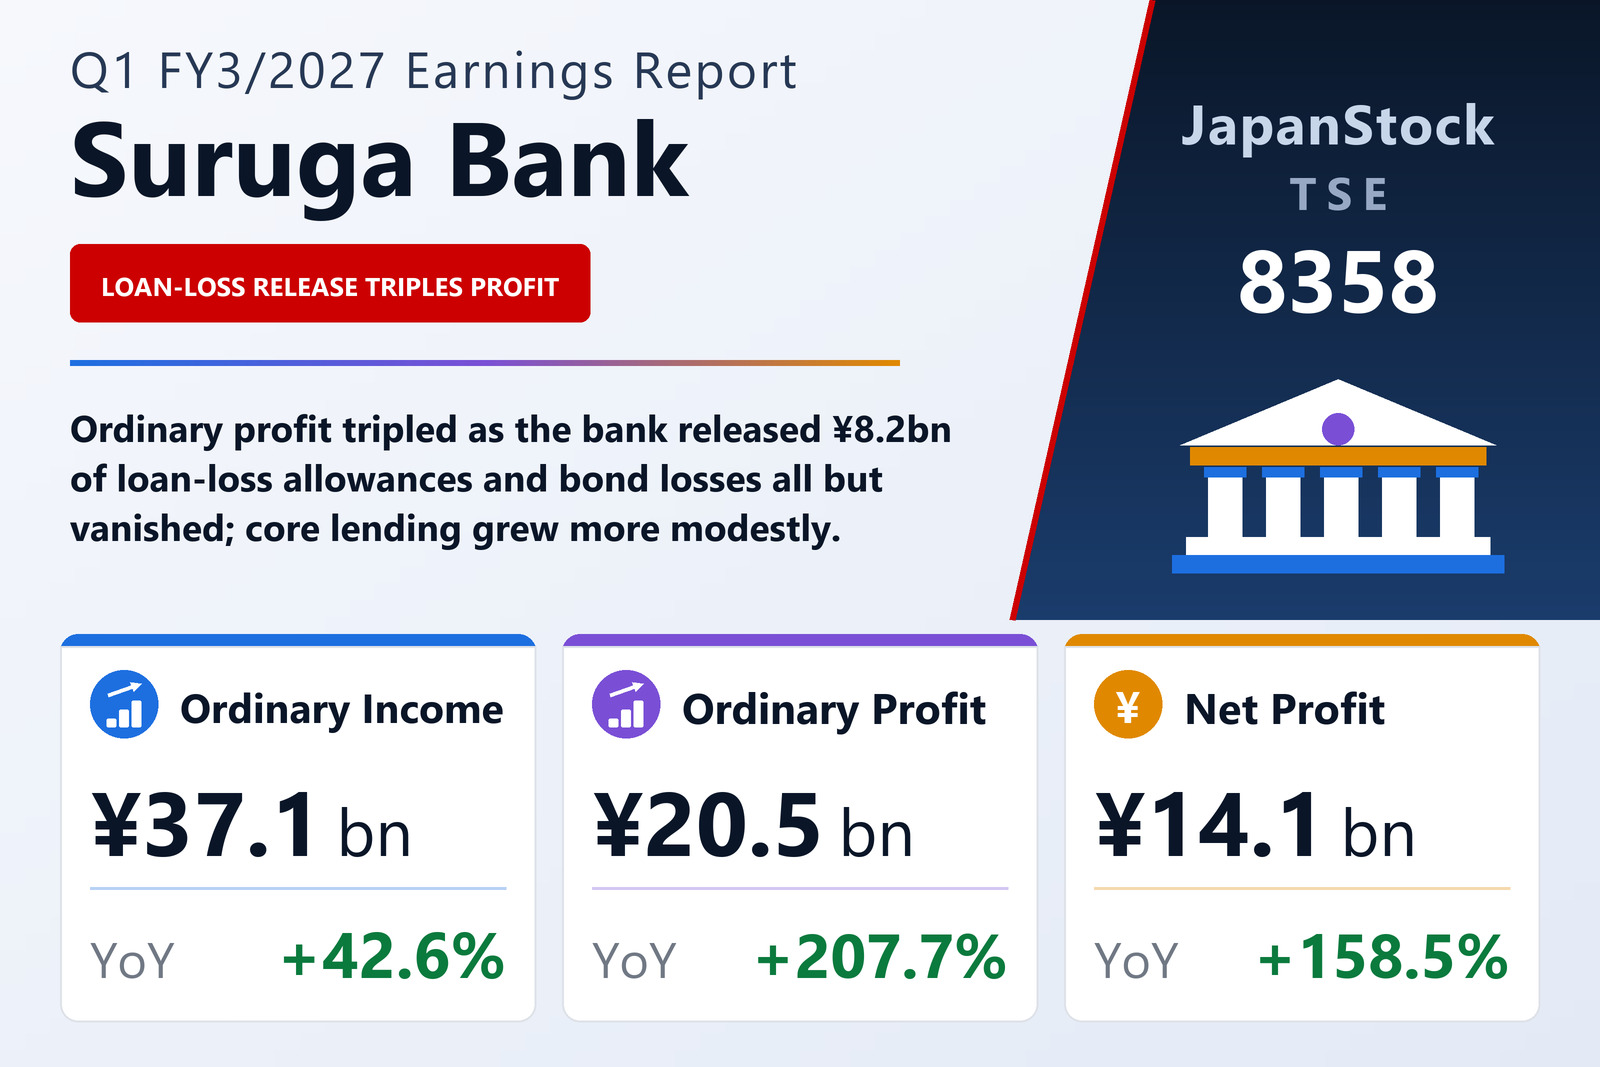
Suruga Bank Ltd. (TSE: 8358), which reports a banking segment alongside subsidiaries engaged in lending, leasing, back-office services, credit cards and loan guarantees, published consolidated results for the three months from April 1 to June 30, 2026 on August 10, 2026 under Japanese GAAP. Ordinary income — a bank's top line — rose 42.6% to ¥37,105 million, ordinary profit 207.7% to ¥20,521 million and net profit attributable to owners of the parent 158.5% to ¥14,086 million. Earnings per share came to ¥82.70 against ¥29.88, and comprehensive income rose 34.5% to ¥14,475 million.
The bank's own explanation is short: ordinary income grew on higher interest on loans and on the booking of a reversal of the allowance for loan losses, and ordinary expenses fell mainly because losses on the redemption of government and other bonds shrank. The income statement shows how lopsided the gain was. Of the ¥11,085 million rise in ordinary income, ¥7,314 million came from other ordinary income, which jumped from ¥3,079 million to ¥10,393 million. On the expense side, other business expenses fell from ¥4,435 million to ¥1,525 million, taking ordinary expenses down 14.3% to ¥16,583 million.
The parent-only supplement quantifies both items. In the quarter the bank released ¥8,171 million of loan-loss allowances, because reversals of general and specific allowances exceeded new provisions, and collected ¥824 million on loans previously written off, against ¥328 million of bad-debt disposals. Its net credit cost was therefore a gain of ¥8,667 million, compared with a gain of ¥935 million a year earlier. Losses on government and other bonds narrowed to ¥282 million from ¥3,951 million.
The core business grew more modestly
Stripped of those items, the lending business improved but did not triple. Consolidated interest income rose 16.4% to ¥23,069 million, with interest on loans up 15.6% to ¥18,759 million and interest and dividends on securities up 26.3% to ¥2,351 million. Funding costs climbed 85.2% to ¥2,811 million, almost all of it deposit interest, which rose from ¥1,517 million to ¥2,794 million. General and administrative expenses fell 4.3% to ¥9,272 million.
At the parent, the loan yield rose 0.20 percentage points to 2.99% and the deposit yield 0.16 points to 0.35%, leaving the loan-deposit spread at 1.52%, up 0.01 points. Core gross business profit rose ¥2,267 million to ¥19,062 million and core net business profit ¥2,137 million to ¥10,270 million, with expenses up only ¥129 million to ¥8,791 million; the overhead ratio improved 5.4 points to 46.1%. Parent-only ordinary profit was ¥20,228 million, of which ¥10,240 million was temporary gains and losses — including the allowance reversal and ¥1,219 million of gains on equities — so roughly half of the quarter's profit did not come from core banking.
Segments
The banking segment's ordinary income, including intersegment income, rose 46.1% to ¥34,850 million and its segment profit 212.2% to ¥20,228 million from ¥6,479 million. The other segment — the consolidated subsidiaries' lending, leasing, back-office, credit-card and guarantee businesses — grew ordinary income 3.9% to ¥2,528 million and profit 48.8% to ¥320 million. A ¥27 million adjustment, mostly goodwill amortization, reconciles the segments to consolidated ordinary profit.
Asset quality and the balance sheet
The allowance for loan losses on the consolidated balance sheet fell from ¥76,632 million at March 31, 2026 to ¥67,167 million at June 30, 2026. Parent-only disclosed claims under the Financial Reconstruction Act totalled ¥145,349 million, down from ¥181,883 million a year earlier, and the ratio of disclosed claims to total credit fell 2.2 points to 6.02%. Excluding borrowers in organized negotiations with the bank, the ratio was 3.76% against 4.75%. The coverage ratio from collateral and guarantees was 83.72%.
Total assets were ¥3,561,131 million, up 0.5% from March 31, 2026. Loans rose ¥12,070 million to ¥2,410,864 million and securities ¥12,032 million to ¥431,111 million, while deposits slipped ¥6,919 million to ¥3,190,303 million. Net assets rose 2.2% to ¥330,472 million, for an equity ratio of 9.2%; the bank notes this is not the regulatory capital ratio. That ratio, on the domestic standard with Basel III final rules applied in full, was 12.02% on a consolidated basis, up from 11.40%, and 11.43% for the parent.
Under a board resolution of April 24, 2026, the bank cancelled 25,000 thousand treasury shares, reducing capital surplus and treasury stock by ¥28,956 million each; the resulting negative balance in other capital surplus was charged against retained earnings, which fell ¥21,369 million to ¥270,662 million. Shares issued fell to 172,139,248 from 197,139,248. The average share count for the quarter was 170,332,484 against 182,300,700 a year earlier, which is why earnings per share rose faster (176.8%) than net profit.
Guidance and dividend unchanged
The bank left its forecasts published on May 14, 2026 unchanged. For the full year to March 31, 2027 it expects ordinary profit of ¥47,500 million (+33.7%) and net profit attributable to owners of the parent of ¥32,000 million (−7.8%), or ¥187.72 per share; for the first half it guides to ¥25,000 million (+49.3%) and ¥17,000 million (+7.4%). The first quarter alone delivered 43.2% of the full-year ordinary-profit forecast and 82.1% of the first-half one. The filing does not explain why net profit is forecast to fall while ordinary profit rises; the parent-only figures it prints for FY3/2026 show a tax charge of only ¥680 million on pre-tax profit of ¥34,701 million, against ¥6,284 million on ¥20,144 million in this quarter alone.
The parent-only plan assumes a net credit cost gain of ¥5,000 million for the first half and ¥6,000 million for the year, both already exceeded by the first quarter's ¥8,667 million. The dividend forecast is unchanged at ¥60.00 per share for the year, split into ¥30.00 at the half and ¥30.00 at year-end, matching FY3/2026's ¥60.00 (¥22.00 interim and ¥38.00 year-end).
| Metric | Q1 FY3/2027 | Q1 FY3/2026 | Change |
|---|---|---|---|
| Ordinary income (¥ million) | 37,105 | 26,020 | +42.6% |
| — interest income (¥ million) | 23,069 | 19,822 | +16.4% |
| —— interest on loans (¥ million) | 18,759 | 16,221 | +15.6% |
| — other ordinary income (¥ million) | 10,393 | 3,079 | +237.5% |
| Ordinary expenses (¥ million) | 16,583 | 19,352 | −14.3% |
| — funding costs (¥ million) | 2,811 | 1,518 | +85.2% |
| — other business expenses (¥ million) | 1,525 | 4,435 | −65.6% |
| — general and administrative expenses (¥ million) | 9,272 | 9,690 | −4.3% |
| Ordinary profit (¥ million) | 20,521 | 6,667 | +207.7% |
| Pre-tax profit (¥ million) | 20,437 | 6,612 | +209.1% |
| Net profit attrib. to owners of parent (¥ million) | 14,086 | 5,448 | +158.5% |
| Comprehensive income (¥ million) | 14,475 | 10,758 | +34.5% |
| EPS (¥) | 82.70 | 29.88 | +176.8% |
| Banking segment — ordinary income (¥ million) | 34,850 | 23,859 | +46.1% |
| Banking segment — segment profit (¥ million) | 20,228 | 6,479 | +212.2% |
| Other — ordinary income (¥ million) | 2,528 | 2,433 | +3.9% |
| Other — segment profit (¥ million) | 320 | 215 | +48.8% |
| Total assets (¥ million) | 3,561,131 | 3,543,585 | +0.5% |
| Deposits (¥ million) | 3,190,303 | 3,197,222 | −0.2% |
| Loans and bills discounted (¥ million) | 2,410,864 | 2,398,794 | +0.5% |
| Securities (¥ million) | 431,111 | 419,079 | +2.9% |
| Allowance for loan losses (¥ million) | 67,167 | 76,632 | −12.4% |
| Net assets (¥ million) | 330,472 | 323,441 | +2.2% |
| Equity ratio | 9.2% | 9.1% | +0.1 pt |
| Capital adequacy ratio, consolidated (domestic standard) | 12.02% | 11.40% | +0.62 pt |
| FY3/2027 guidance — ordinary profit (¥ million) | 47,500 | — | +33.7% |
| FY3/2027 guidance — net profit (¥ million) | 32,000 | — | −7.8% |
| FY3/2027 guidance — EPS (¥) | 187.72 | — | — |
| Annual dividend per share (¥) | 60.00 | 60.00 | unchanged |
JapanStockPulse provides informational content only and does not constitute investment advice. Figures are taken from the company's published earnings short report and may be subject to subsequent revision.