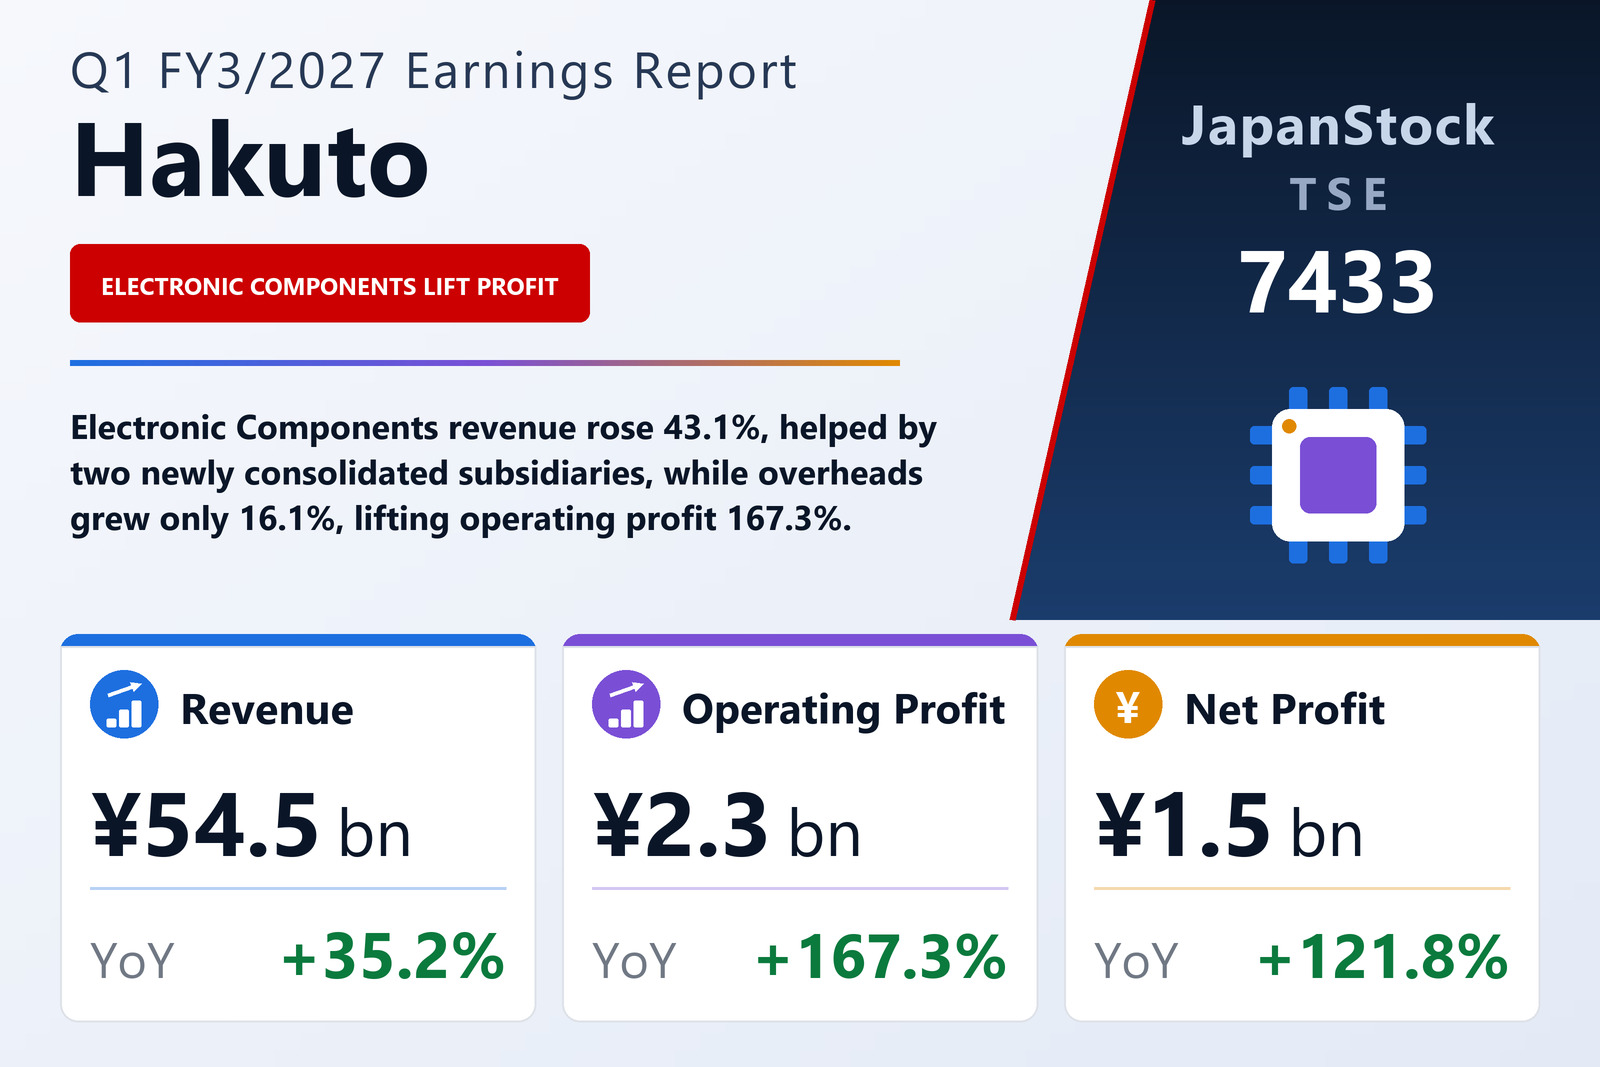
Revenue up 35.2%, operating profit up 167.3%
Hakuto Co., Ltd. (TSE: 7433), the electronics-focused trading group whose businesses span electronic components, electronic and electrical equipment, and chemicals, published consolidated results for the first quarter of FY3/2027 — April 1 to June 30, 2026 — on August 12, 2026 under Japanese GAAP. Revenue rose 35.2% to ¥54,537 million, operating profit 167.3% to ¥2,323 million, ordinary profit 219.1% to ¥2,295 million and profit attributable to owners of the parent 121.8% to ¥1,462 million, for earnings of ¥77.67 per share against ¥35.03.
The step from revenue to operating profit is a cost story. Gross profit rose 39.0% to ¥7,989 million, a little faster than revenue, lifting the gross margin from 14.3% to 14.6%. Selling, general and administrative expenses rose only 16.1% to ¥5,665 million — under half the rate of revenue growth — so of ¥2,241 million of extra gross profit, ¥787 million went on higher overheads and ¥1,454 million reached the operating line. The operating margin nearly doubled, from 2.2% to 4.3%. Within overheads, salaries and allowances rose to ¥1,688 million from ¥1,453 million and other expenses to ¥3,160 million from ¥2,589 million.
A currency swing below the operating line, partly offset by higher interest
Ordinary profit grew faster than operating profit because last year's foreign-exchange loss of ¥174 million turned into a gain of ¥163 million. That more than covered a sharp rise in interest expense, to ¥282 million from ¥79 million, for which the filing gives no explanation. Non-operating income totalled ¥289 million against ¥109 million, and non-operating expenses ¥317 million against ¥258 million. An extraordinary gain of ¥288 million on sales of investment securities (¥252 million a year earlier) took pre-tax profit to ¥2,583 million from ¥971 million.
Income taxes were ¥1,018 million against ¥312 million, leaving quarterly profit of ¥1,564 million. Of that, ¥102 million was attributable to non-controlling interests, a line that was blank a year earlier, which is why profit attributable to owners of the parent grew a slower 121.8%. Comprehensive income was ¥2,748 million, up 78.2%, lifted by ¥691 million of unrealised gains on securities and ¥493 million of foreign-currency translation adjustments.
Electronic Components, with two new subsidiaries, carried the quarter
Electronic Components, by far the largest segment, grew revenue 43.1% to ¥44,873 million and segment profit 287.3% to ¥2,021 million from ¥521 million. The filing cites firm automotive demand, a recovery in demand from industrial equipment, strong optical components on next-generation communications infrastructure and 5G investment, and the contribution of two newly consolidated subsidiaries; it attributes the profit gain to higher sales and currency effects. Amortisation of goodwill rose to ¥302 million from ¥79 million, and goodwill stood at ¥15,761 million at June 30. The filing reports no change in the scope of consolidation during the quarter itself, so the new subsidiaries were already consolidated when it began.
Electronic & Electrical Equipment revenue rose 15.6% to ¥6,173 million and segment profit 2.8% to ¥430 million. Customer inquiries have risen sharply on active investment in semiconductors, AI and data centres, but the company says the long lead time from order to sale limited the contribution to first-quarter revenue; sales of PCB manufacturing equipment grew. Chemicals revenue fell 3.6% to ¥2,639 million and segment profit 10.1% to ¥136 million: raw-material costs rose as crude oil, naphtha and logistics prices climbed on instability in the Middle East, and overseas shipments of cosmetic base materials declined, while petroleum and petrochemical and paper and pulp sales were flat.
The Other segment — contracted business and logistics management, solar power generation and, since the second half of last year, contract analysis and testing — posted revenue of ¥948 million, down 5.2%, and a segment loss of ¥325 million, narrower than the ¥370 million loss a year earlier. Segment profit totalled ¥2,262 million before ¥61 million of adjustments.
Receivables, payables and short-term debt all higher
Total assets rose 2.2% to ¥168,044 million from ¥164,484 million at March 31, 2026, mainly on a ¥2,054 million increase in notes and accounts receivable and contract assets and a ¥1,004 million rise in investment securities as share prices increased. Liabilities rose ¥2,664 million to ¥97,316 million: trade payables were up ¥2,755 million and short-term borrowings ¥1,495 million, to ¥34,726 million, while long-term borrowings fell ¥1,754 million to ¥22,393 million. Net assets rose ¥894 million to ¥70,728 million, and the equity ratio edged down from 41.6% to 41.2%.
Operating cash flow was an inflow of ¥3,128 million against ¥4,430 million a year earlier. Pre-tax profit of ¥2,583 million and a ¥2,730 million rise in payables were partly offset by a ¥1,946 million increase in receivables, which had fallen by ¥3,384 million in the prior-year quarter. Investing activities brought in ¥55 million, mainly ¥299 million from sales of investment securities, and financing used ¥2,354 million, chiefly ¥1,786 million of dividends. Cash and cash equivalents rose ¥1,083 million to ¥19,833 million.
Guidance raised on July 29 stands; a three-for-one split follows
Hakuto raised its guidance on July 29, 2026, citing growing demand for semiconductors and general electronic components and more inquiries for vacuum equipment and PCB manufacturing equipment, and left it unchanged with this release. For the six months to September 30 it expects revenue of ¥111,500 million (+33.1%) and operating profit of ¥3,900 million (+66.0%); for the full year, revenue of ¥227,500 million (+25.6%), operating profit of ¥9,600 million (+57.9%), ordinary profit of ¥8,600 million (+54.1%) and profit attributable to owners of the parent of ¥6,400 million (+27.7%). The first quarter delivered 48.9% of first-half revenue guidance but 59.6% of first-half operating profit guidance, which implies second-quarter operating profit of about ¥1,577 million against the ¥2,323 million just booked; the filing does not comment on that shape.
On the same July 29 the board approved a three-for-one stock split with a record date of September 30, 2026, effective October 1, raising shares issued from 21,137,213 to 63,411,639. On a post-split basis, first-quarter earnings per share would be ¥25.89 against ¥11.68. The full-year EPS guidance of ¥113.32 already reflects the split (¥339.95 without it). The dividend forecast is unchanged: ¥120.00 at the half-year and ¥135.00 at the year-end on a pre-split basis — ¥45.00 after the split — for an annual ¥255.00 against ¥200.00, up 27.5%.
Earthquake exposure under review
The filing also discloses exposure to the Kumamoto earthquake of July 28, 2026. Hakuto outsources assembly of part of its own-brand printed-circuit-board manufacturing equipment to a partner company in Yatsushiro, Kumamoto Prefecture, which held Hakuto inventory with a book value of ¥1,340 million at June 30, 2026, alongside ¥91 million of assembly equipment owned by Hakuto. The effect on results is still under investigation, and the company says it will disclose promptly once any matter requiring disclosure becomes clear.
| Metric | Q1 FY3/2027 | Q1 FY3/2026 | Change |
|---|---|---|---|
| Revenue (¥ million) | 54,537 | 40,337 | +35.2% |
| Gross profit (¥ million) | 7,989 | 5,748 | +39.0% |
| Gross margin | 14.6% | 14.3% | +0.4 pt |
| SG&A expenses (¥ million) | 5,665 | 4,878 | +16.1% |
| Operating profit (¥ million) | 2,323 | 869 | +167.3% |
| Operating margin | 4.3% | 2.2% | +2.1 pt |
| Ordinary profit (¥ million) | 2,295 | 719 | +219.1% |
| Net profit attrib. to owners of parent (¥ million) | 1,462 | 659 | +121.8% |
| Comprehensive income (¥ million) | 2,748 | 1,542 | +78.2% |
| EPS (¥) | 77.67 | 35.03 | +121.7% |
| Electronic Components — revenue (¥ million) | 44,873 | 31,359 | +43.1% |
| Electronic Components — segment profit (¥ million) | 2,021 | 521 | +287.3% |
| Electronic & Electrical Equipment — revenue (¥ million) | 6,173 | 5,341 | +15.6% |
| Electronic & Electrical Equipment — segment profit (¥ million) | 430 | 418 | +2.8% |
| Chemicals — revenue (¥ million) | 2,639 | 2,737 | −3.6% |
| Chemicals — segment profit (¥ million) | 136 | 151 | −10.1% |
| Other — revenue (¥ million) | 948 | 1,000 | −5.2% |
| Other — segment profit (¥ million) | −325 | −370 | loss narrowed |
| Total assets (¥ million) | 168,044 | 164,484 | +2.2% |
| Net assets (¥ million) | 70,728 | 69,833 | +1.3% |
| Equity ratio | 41.2% | 41.6% | −0.4 pt |
| FY3/2027 guidance — revenue (¥ million) | 227,500 | — | +25.6% |
| FY3/2027 guidance — operating profit (¥ million) | 9,600 | — | +57.9% |
| FY3/2027 guidance — ordinary profit (¥ million) | 8,600 | — | +54.1% |
| FY3/2027 guidance — net profit (¥ million) | 6,400 | — | +27.7% |
| FY3/2027 guidance — EPS, post-split (¥) | 113.32 | — | — |
| Annual dividend per share, pre-split basis (¥) | 255.00 | 200.00 | +27.5% |
JapanStockPulse provides informational content only and does not constitute investment advice. Figures are taken from the company's published earnings short report and may be subject to subsequent revision.