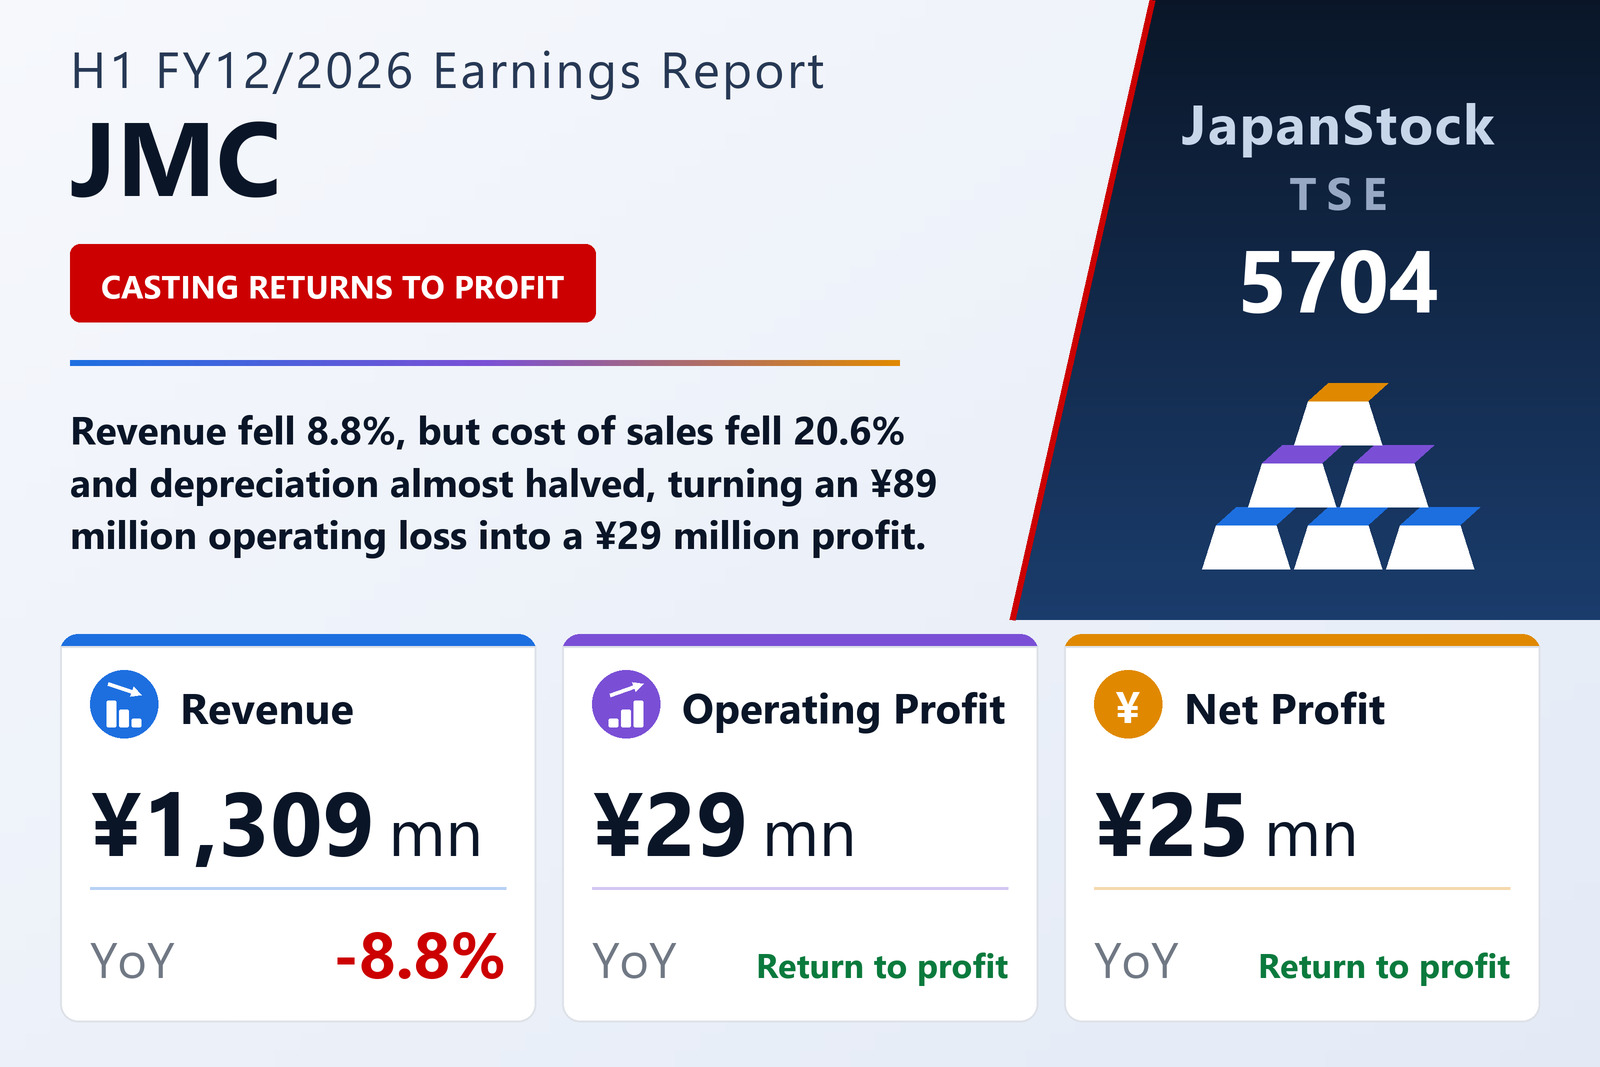
Revenue fell 8.8%, but costs fell much faster
JMC Corporation (TSE: 5704), which produces prototypes and parts by 3D printing and metal casting and offers industrial CT scanning, published non-consolidated results for the first half of its fiscal year ending December 2026 — the six months from January 1 to June 30, 2026 — on August 13, 2026 under Japanese GAAP. Revenue fell 8.8% to ¥1,309 million, yet the company booked an operating profit of ¥29 million against an operating loss of ¥89 million a year earlier, ordinary profit of ¥34 million against a ¥94 million loss, and interim net profit of ¥25 million against a ¥72 million loss. Earnings per share were ¥4.54 against a loss of ¥13.02. The filing names the Tokyo Stock Exchange as the company's listing, and the interim report was not reviewed by an auditor.
The turnaround sits in the cost of sales. It fell 20.6% to ¥836 million, more than twice as fast as revenue, so gross profit rose 23.5% to ¥473 million on lower sales and the gross margin widened from 26.7% to 36.1%. Selling, general and administrative expenses fell 6.1% to ¥443 million, and the operating margin moved from −6.2% to 2.2%. The cash-flow statement points to one large ingredient: depreciation dropped to ¥99 million from ¥190 million, down 47.7%, and the filing says the impairment loss booked in fiscal 2025 lowered fixed costs in the casting business. It does not say how much of the cost saving came from depreciation and how much from lower volumes.
Below the operating line, every small item moved the right way
Non-operating income rose to ¥8.2 million from ¥2.0 million, mainly on ¥5.0 million of compensation received and a ¥2.3 million foreign-exchange gain, while non-operating expenses fell to ¥3.3 million from ¥7.0 million as interest expense dropped to ¥2.8 million from ¥5.1 million and last year's ¥1.9 million exchange loss disappeared. That took ordinary profit to ¥34.3 million. A ¥2.7 million loss on the disposal of fixed assets left pre-tax profit at ¥31.6 million against a pre-tax loss of ¥98.3 million. Taxes were a charge of ¥6.3 million this year against a net credit of ¥26.1 million a year earlier, when a deferred-tax adjustment of ¥29.9 million cushioned the loss, so interim net profit came to ¥25.2 million.
Casting swung to a segment profit; CT fell by a third
The three segments moved in three directions. Casting, the largest at 63% of revenue, saw sales fall 8.7% to ¥826 million but swung to a segment profit of ¥70 million from a ¥74 million loss. 3D Printer revenue rose 8.5% to ¥329 million and segment profit 37.5% to ¥91 million. CT revenue fell 32.3% to ¥153 million and segment profit 32.8% to ¥109 million. Together the segments earned ¥272 million against ¥155 million, but unallocated corporate expenses — mainly general administrative costs — took ¥242 million, against ¥244 million a year earlier, leaving the ¥29 million operating profit.
The filing's account of casting is mixed. Automakers at home and abroad and their Tier 1 suppliers brought development work on EV-related and drivetrain parts, and orders came in for large castings for industrial robots, both prototypes and replacement parts. In the latter part of the half, however, customer projects progressed more slowly than expected and total order volume fell, while demand for larger, thinner-walled and stronger castings made profits hard to earn. Against that, the company says its quality-control system is broadly in place, and together with the lower fixed costs that followed the fiscal 2025 impairment, the segment recovered. General machinery manufacturers accounted for 62.1% of casting sales.
In 3D printing, the company added staff behind HEARTROID, its own cardiac-catheter simulator, and says it captured customer demand in Japan and overseas, taking the product above last year; the print-output service, which ranges from industrial prototype parts to mock-ups for trade shows and events, was roughly flat. CT fell because the company did not find large scanning jobs and booked no CT equipment sale this half, after one in the prior-year period, despite trade-show appearances, customer seminars, free first-scan offers and information exchanges with specialist trading companies.
Receivables collected, debt paid down
Total assets fell 7.2% to ¥2,656 million from December 31, 2025, largely because notes and accounts receivable dropped to ¥261 million from ¥500 million and electronically recorded receivables to ¥7 million from ¥113 million. Cash and deposits rose ¥139 million to ¥564 million. Borrowings fell to ¥491 million from ¥662 million: short-term loans of ¥50 million were repaid in full and long-term borrowings due after one year fell to ¥165 million from ¥286 million. Net assets rose 1.8% to ¥1,676 million on the half's profit, and the equity ratio climbed from 57.5% to 63.1%.
Operating cash flow was ¥386 million against ¥368 million, driven by a ¥344 million decrease in receivables and ¥99 million of depreciation, with ¥32 million of income taxes paid against a ¥65 million refund a year earlier. Investing outflows shrank to ¥43 million from ¥134 million, with capital spending on property, plant and equipment of ¥36 million. Financing used ¥203 million: ¥221 million of long-term debt repayment and a ¥50 million net cut in short-term loans, partly offset by ¥100 million of new long-term borrowing.
Guidance unchanged, but the second half has to carry it
JMC kept the full-year FY12/2026 forecast it published on February 13, 2026: revenue of ¥3,020 million (−6.3%), operating profit of ¥205 million (+97.9%), ordinary profit of ¥199 million (+96.6%) and net profit of ¥132 million, or ¥23.79 per share. The first half delivered 43.4% of guided revenue but only 14.4% of guided operating profit, which implies a second half of roughly ¥1,710 million in revenue and ¥176 million in operating profit — six times the ¥29 million just booked. The company itself says the half ran slightly below its assumptions and that it needs to examine current conditions and watch developments carefully, without giving a second-half breakdown. No dividend is planned: the interim dividend was zero and the year-end forecast is zero, as in fiscal 2025.
| Metric | H1 FY12/2026 | H1 FY12/2025 | Change |
|---|---|---|---|
| Revenue (¥ million) | 1,309 | 1,435 | −8.8% |
| Cost of sales (¥ million) | 836 | 1,052 | −20.6% |
| Gross profit (¥ million) | 473 | 383 | +23.5% |
| Gross margin | 36.1% | 26.7% | +9.4 pt |
| SG&A expenses (¥ million) | 443 | 472 | −6.1% |
| Operating profit (¥ million) | 29 | −89 | loss to profit |
| Operating margin | 2.2% | −6.2% | +8.5 pt |
| Ordinary profit (¥ million) | 34 | −94 | loss to profit |
| Pre-tax profit (¥ million) | 31 | −98 | loss to profit |
| Net profit (¥ million) | 25 | −72 | loss to profit |
| EPS (¥) | 4.54 | −13.02 | loss to profit |
| Depreciation (¥ million) | 99 | 190 | −47.7% |
| 3D Printer — revenue (¥ million) | 329 | 303 | +8.5% |
| 3D Printer — segment profit (¥ million) | 91 | 66 | +37.5% |
| Casting — revenue (¥ million) | 826 | 904 | −8.7% |
| Casting — segment profit (¥ million) | 70 | −74 | loss to profit |
| CT — revenue (¥ million) | 153 | 227 | −32.3% |
| CT — segment profit (¥ million) | 109 | 162 | −32.8% |
| Unallocated corporate expenses (¥ million) | −242 | −244 | −0.6% |
| Operating cash flow (¥ million) | 386 | 368 | +4.9% |
| Total assets (¥ million) | 2,656 | 2,863 | −7.2% |
| Cash and deposits (¥ million) | 564 | 425 | +32.8% |
| Borrowings (¥ million) | 491 | 662 | −25.9% |
| Net assets (¥ million) | 1,676 | 1,647 | +1.8% |
| Equity ratio | 63.1% | 57.5% | +5.6 pt |
| FY12/2026 guidance — revenue (¥ million) | 3,020 | — | −6.3% |
| FY12/2026 guidance — operating profit (¥ million) | 205 | — | +97.9% |
| FY12/2026 guidance — ordinary profit (¥ million) | 199 | — | +96.6% |
| FY12/2026 guidance — net profit (¥ million) | 132 | — | n.m. |
| FY12/2026 guidance — EPS (¥) | 23.79 | — | n.m. |
| Annual dividend per share (¥) | 0.00 | 0.00 | unchanged |
JapanStockPulse provides informational content only and does not constitute investment advice. Figures are taken from the company's published earnings short report and may be subject to subsequent revision.