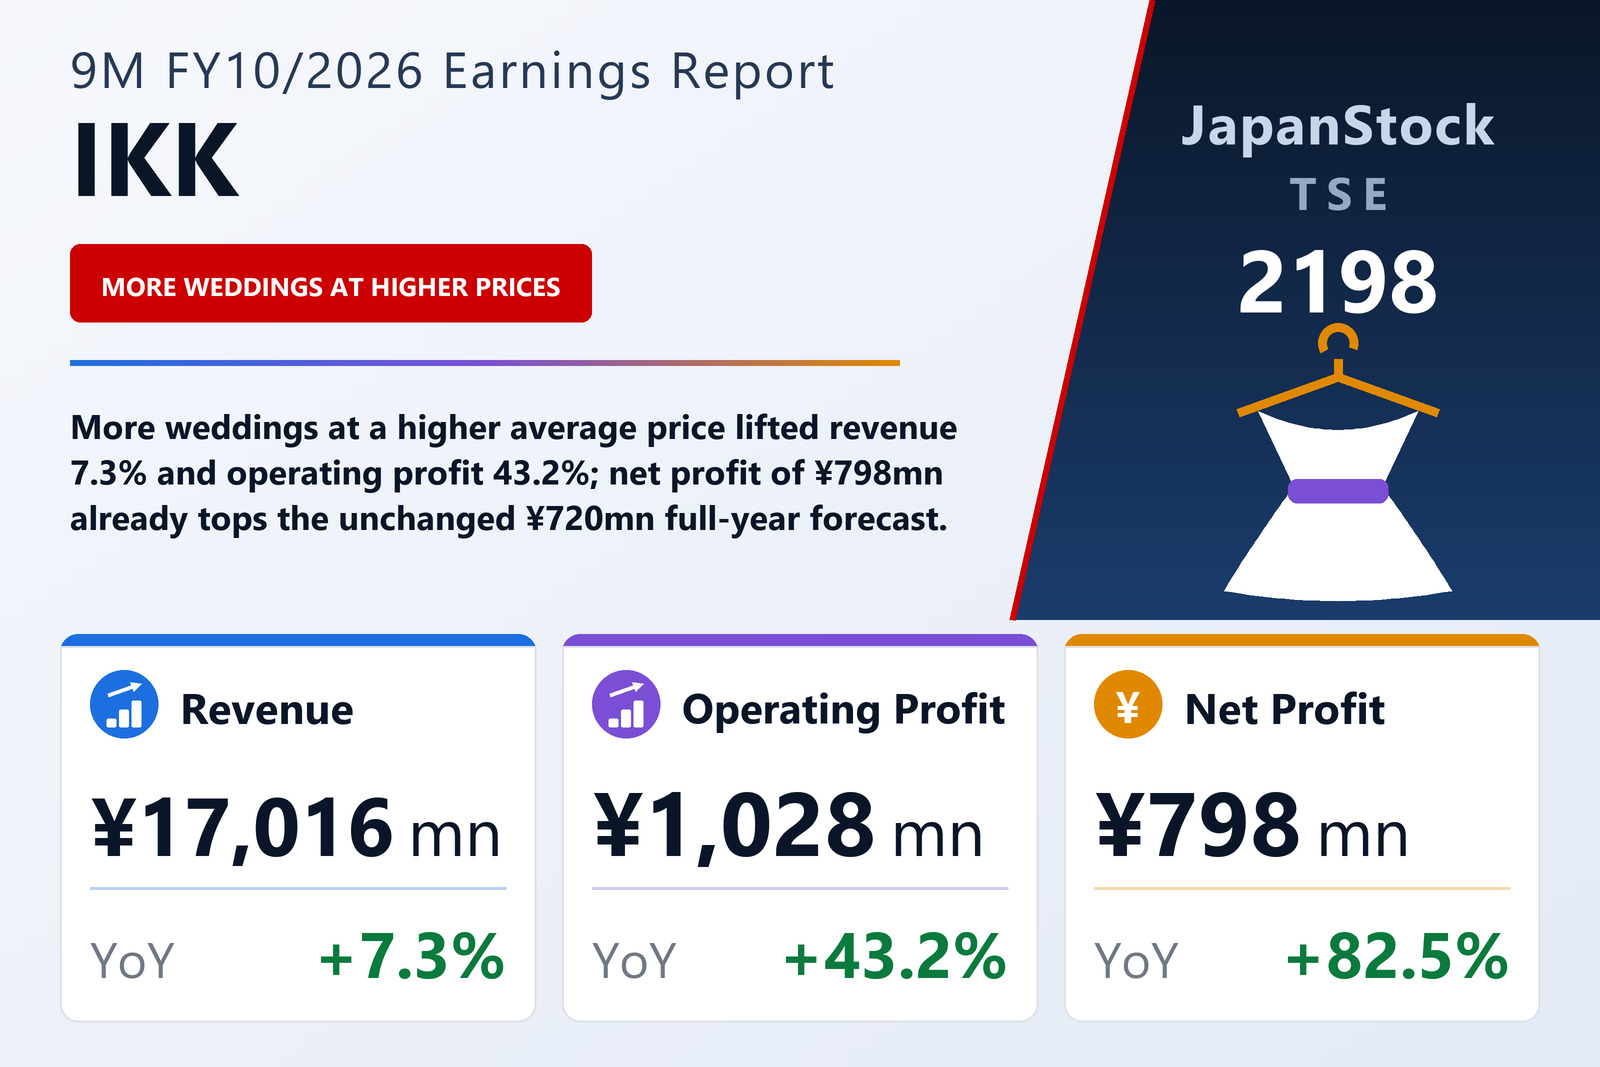
Revenue up 7.3%, operating profit up 43.2% — because costs grew more slowly than sales
IKK Holdings Inc. (TSE: 2198), which operates wedding venues and runs smaller nursing-care, food and photo-studio businesses, published consolidated results for the first nine months of its fiscal year ending October 31, 2026 — the period from November 1, 2025 to July 31, 2026 — on September 10, 2026 under Japanese GAAP. Revenue rose 7.3% to ¥17,016 million, operating profit 43.2% to ¥1,028 million, ordinary profit 52.4% to ¥1,148 million and profit attributable to owners of the parent 82.5% to ¥798 million, for earnings of ¥27.39 per share against ¥15.17. The company is listed on the Tokyo Stock Exchange.
The operating line moved far more than sales because costs grew more slowly than revenue at both steps. Cost of sales rose 6.5% to ¥6,745 million, so gross profit rose 7.8% to ¥10,271 million and the gross margin edged up from 60.1% to 60.4%. Selling, general and administrative expenses — the larger of the two cost lines, at 54.3% of revenue — rose only 4.9% to ¥9,243 million. Gross profit therefore gained ¥742 million while SG&A absorbed only ¥432 million of it, and the ¥310 million difference is the entire rise in operating profit. The operating margin widened from 4.5% to 6.0%. Depreciation, which the company discloses in place of a cash-flow statement for the period, was ¥819 million against ¥827 million.
Below the operating line: more non-operating income and a gain on an asset sale
Ordinary profit rose faster still, 52.4% to ¥1,148 million, because non-operating income more than doubled to ¥143 million from ¥59 million while non-operating expenses stayed at ¥23 million. The largest movements were commission income of ¥44 million against ¥5 million and interest on securities of ¥34 million against ¥13 million; the filing does not explain either. Extraordinary items then added more: a ¥127 million gain on the sale of fixed assets and a ¥41 million reversal of asset retirement obligations took extraordinary income to ¥168 million from ¥4 million, against extraordinary losses of ¥5 million in both years. Pre-tax profit rose 74.3% to ¥1,312 million. Income taxes rose a slower 66.0%, to ¥510 million, and profit attributable to non-controlling interests fell to ¥2 million from ¥7 million, which is why profit attributable to owners grew faster than any line above it. Comprehensive income was ¥817 million, up 112.6%.
Weddings: more ceremonies, at a higher price per wedding
The wedding business is most of the company: its revenue of ¥15,417 million, up 5.5%, is 87% of segment revenue before intersegment eliminations. The filing attributes the growth to increases in both the average price per wedding and the number of weddings held, though it gives neither figure. Segment profit rose 19.8% to ¥1,282 million, lifting the segment margin from 7.3% to 8.3%. The company says it continued internal and external training aimed at its staff's hospitality skills, used its own sales-support system to sharpen information gathering and analysis, pushed brand-building through a dedicated team, applied AI to strengthen its proposals, and ran an internal award scheme for outstanding plans and services.
The market backdrop the filing describes is steady rather than growing. It cites 480,000 marriages in Japan in 2025, about 4,000 more than the year before, from preliminary Ministry of Health, Labour and Welfare statistics, and says that although the shrinking population of marrying age remains a structural problem, the number of ceremonies and receptions has held up and the guest-house wedding market has been broadly firm.
The smaller businesses: food turns profitable, photo pays for a new studio
Food more than doubled its revenue, up 143.7% to ¥791 million, on higher orders for catalogue gifts and wedding return gifts (hikidemono), and swung to a segment profit of ¥94 million from a ¥23 million loss. Most of that revenue stays inside the group: ¥612 million of it was intersegment sales, leaving ¥179 million from outside customers, against ¥84 million a year earlier. Photo revenue rose 39.2% to ¥925 million with the start of Studio Clori.TOKYO Shinjuku, opened in November 2025, but segment profit fell 32.2% to ¥111 million; the filing ties both figures to the new studio without separating its start-up costs. Nursing care was flat, with revenue of ¥495 million (+0.5%) and profit of ¥24 million (+1.7%), and the filing gives no reason.
Two further lines complete the bridge to operating profit. A new, non-reportable Other segment — a human-resources business — lost ¥46 million; there was no such line a year ago. Adjustments, mainly unallocated corporate costs, fell to ¥438 million from ¥516 million. Reportable-segment profit of ¥1,513 million, less the ¥46 million loss and the ¥438 million adjustment, reconciles to the ¥1,028 million operating profit, allowing for rounding. The prior-year segment figures have been restated: from this fiscal year the company changed how part of its corporate costs is allocated to segments, and the comparison uses the new method.
Balance sheet: cash moved into fixed assets, part-funded by borrowing
Total assets rose 1.0% to ¥21,007 million from ¥20,802 million at October 31, 2025, but the mix moved more than the total. Property, plant and equipment rose ¥1,228 million to ¥11,385 million; the increase came in the category shown as other, up ¥1,422 million to ¥1,987 million from ¥564 million, while buildings and structures fell ¥193 million, and the filing does not say what the other category contains. Cash and deposits fell ¥968 million to ¥4,525 million. On the other side, long-term borrowings including the current portion rose ¥715 million to ¥3,110 million, while accounts payable fell ¥318 million, income taxes payable ¥215 million and the bonus provision ¥181 million, leaving total liabilities essentially unchanged at ¥8,598 million. Net assets rose ¥205 million to ¥12,408 million — the ¥798 million of profit and ¥95 million from sales of treasury shares and similar items, less ¥710 million of dividends — and the equity ratio rose from 58.4% to 58.8%.
Guidance left unchanged — even though net profit has already passed it
IKK Holdings kept the full-year FY10/2026 forecast it published on December 11, 2025: revenue of ¥22,850 million (+1.8%), operating profit of ¥1,200 million (−34.1%), ordinary profit of ¥1,175 million (−37.9%) and profit attributable to owners of ¥720 million (−63.3%), or ¥25.02 per share. Nine months in, the company has booked 74.5% of forecast revenue, 85.7% of forecast operating profit, 97.7% of forecast ordinary profit and 110.8% of forecast net profit, and its nine-month EPS of ¥27.39 is already above the full-year ¥25.02. Taken literally, the forecast implies a fourth quarter, August to October, with revenue of about ¥5,833 million, operating profit of about ¥172 million, ordinary profit of about ¥27 million and a net loss of about ¥78 million.
The filing explains why it has not moved the numbers. Results through the third quarter have run broadly ahead of plan, it says, but the timing and amount of the costs for renovations and new openings scheduled for the fourth quarter are not yet fixed, so their effect cannot be reasonably estimated; it will disclose promptly if a revision becomes necessary. The forecast's own percentages make the same point from the other side: full-year operating profit is guided down 34.1% even though the first nine months rose 43.2%, which can only be squared if the fourth quarter is expected to be far weaker than the same quarter a year earlier. The dividend forecast is also unchanged, at a single year-end payment of ¥24.00 per share, the same as last year — about 96% of the forecast EPS of ¥25.02, though only 88% of the ¥27.39 already earned.
| Metric | 9M FY10/2026 | 9M FY10/2025 | Change |
|---|---|---|---|
| Revenue (¥ million) | 17,016 | 15,861 | +7.3% |
| Gross profit (¥ million) | 10,271 | 9,529 | +7.8% |
| Gross margin | 60.4% | 60.1% | +0.3 pt |
| SG&A expenses (¥ million) | 9,243 | 8,811 | +4.9% |
| Operating profit (¥ million) | 1,028 | 717 | +43.2% |
| Operating margin | 6.0% | 4.5% | +1.5 pt |
| Ordinary profit (¥ million) | 1,148 | 753 | +52.4% |
| Extraordinary income (¥ million) | 168 | 4 | n.m. |
| Pre-tax profit (¥ million) | 1,312 | 752 | +74.3% |
| Net profit attrib. to owners of parent (¥ million) | 798 | 437 | +82.5% |
| EPS (¥) | 27.39 | 15.17 | +80.6% |
| Comprehensive income (¥ million) | 817 | 384 | +112.6% |
| Depreciation (¥ million) | 819 | 827 | −1.0% |
| Weddings — revenue (¥ million) | 15,417 | 14,620 | +5.5% |
| Weddings — segment profit (¥ million) | 1,282 | 1,070 | +19.8% |
| Nursing Care — revenue (¥ million) | 495 | 493 | +0.5% |
| Nursing Care — segment profit (¥ million) | 24 | 24 | +1.7% |
| Food — revenue (¥ million) | 791 | 324 | +143.7% |
| Food — segment profit (¥ million) | 94 | −23 | loss to profit |
| Photo — revenue (¥ million) | 925 | 664 | +39.2% |
| Photo — segment profit (¥ million) | 111 | 164 | −32.2% |
| Other (human resources) — segment profit (¥ million) | −46 | — | new |
| Adjustments, mainly corporate expenses (¥ million) | −438 | −516 | — |
| Total assets (¥ million) | 21,007 | 20,802 | +1.0% |
| Cash and deposits (¥ million) | 4,525 | 5,494 | −17.6% |
| Property, plant and equipment (¥ million) | 11,385 | 10,157 | +12.1% |
| Long-term borrowings incl. current portion (¥ million) | 3,110 | 2,394 | +29.9% |
| Net assets (¥ million) | 12,408 | 12,202 | +1.7% |
| Equity ratio | 58.8% | 58.4% | +0.4 pt |
| FY10/2026 guidance — revenue (¥ million) | 22,850 | — | +1.8% |
| FY10/2026 guidance — operating profit (¥ million) | 1,200 | — | −34.1% |
| FY10/2026 guidance — ordinary profit (¥ million) | 1,175 | — | −37.9% |
| FY10/2026 guidance — net profit (¥ million) | 720 | — | −63.3% |
| FY10/2026 guidance — EPS (¥) | 25.02 | — | — |
| Annual dividend per share (¥) | 24.00 | 24.00 | unchanged |
JapanStockPulse provides informational content only and does not constitute investment advice. Figures are taken from the company's published earnings short report and may be subject to subsequent revision.