A record top line, and almost all of it from one segment
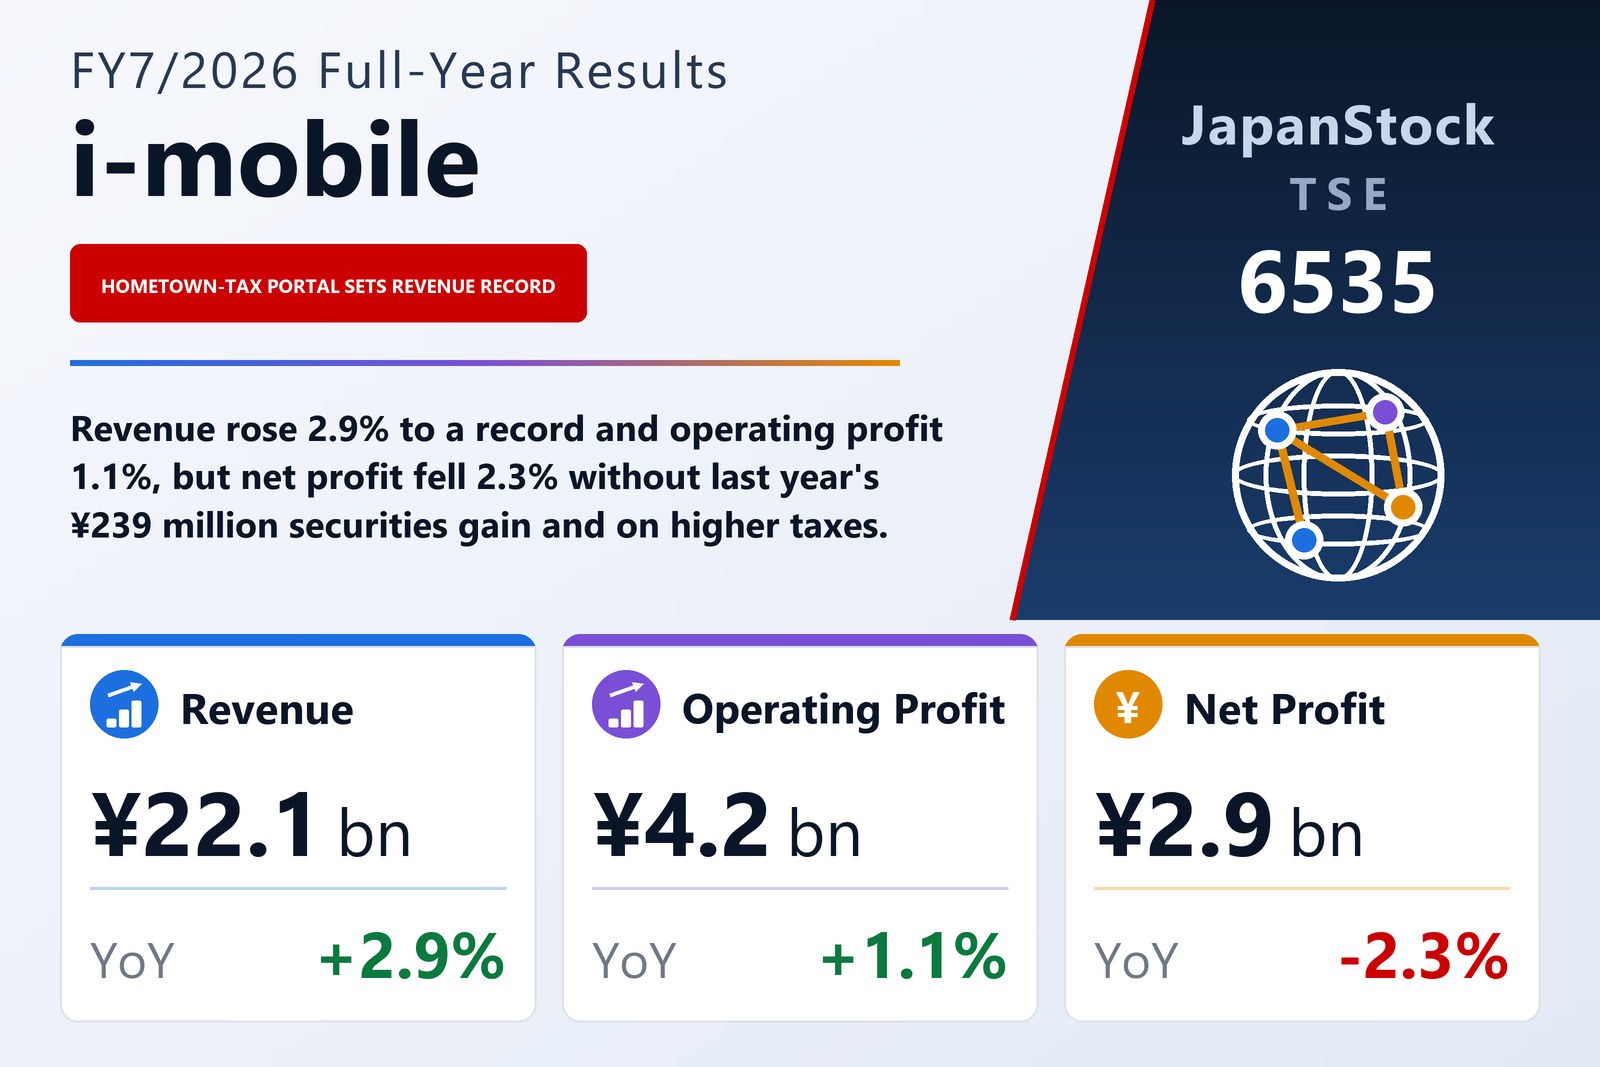
i-mobile Co., Ltd. (TSE: 6535), the internet-marketing group that runs the Furunavi hometown-tax (furusato nozei) donation portal alongside an ad-network business, published consolidated results for the full year from August 1, 2025 to July 31, 2026 on September 10, 2026 under Japanese GAAP. Revenue rose 2.9% to ¥22,146 million, a record that, the company says, met its full-year plan. Operating profit rose 1.1% to ¥4,177 million, ordinary profit 5.1% to ¥4,277 million, and profit attributable to owners of the parent fell 2.3% to ¥2,890 million. Earnings per share nonetheless rose to ¥51.64 from ¥51.40, because share buybacks cut the average number of shares by 2.7%. The company is listed on the Prime market of the Tokyo Stock Exchange.
The group reports two segments, and the gap between them is the story of the year. Consumer — the Furunavi portal plus travel, restaurant-PR and points services — produced revenue of ¥19,538 million, up 2.5%, and segment profit of ¥4,101 million, up 2.0%: 88.2% of group revenue and 98.2% of the two segments' combined profit. The company says donations received through the business and its revenue both set new records, helped by expanded payment services, TV-commercial campaigns and a stable repeat rate. Internet Advertising — the ad network, influencer marketing, media solutions and app operation — shrank to ¥2,316 million, down 4.0%, and its segment profit fell 51.4% to ¥74 million, a margin of 3.2% against 6.3%. The filing blames budget cuts at large ad-network clients and lower industry-wide ad spending, and says the shift in the dominant ad formats has slowed growth in the ad-network market in particular.
Promotion spending was the swing factor inside Consumer
The Consumer profit line reflects a deliberate first quarter. The company says it made strategic promotion investments in that quarter to seize a chance to enlarge its member base, which pushed sales-promotion costs above plan; from the second quarter, with the larger base in place, promotion spending was brought back to appropriate levels and the margin improved, leaving full-year segment profit above the prior year. On the market, the filing cites Ministry of Internal Affairs and Communications data showing hometown-tax donations of ¥1.3314 trillion in fiscal 2025, up 4.6%, and a record of about 11.51 million people claiming the tax deduction, while its own estimate of the usage rate is only 18.5%. It reads that as ample room for further growth, though of a more stable kind now that tax and rule changes have ended the earlier high-growth phase.
Cost lines and taxes explain why profit lagged revenue
The arithmetic is thin but clear. Revenue rose ¥618 million; selling, general and administrative expenses — which at ¥17,749 million absorb 80.1% of revenue — rose ¥382 million, or 2.2%, and cost of sales, still small, rose to ¥219 million from ¥28 million. Operating profit therefore gained only ¥44 million, and the operating margin slipped to 18.9% from 19.2%. Below the operating line the picture improved: non-operating income rose to ¥126 million from ¥19 million, chiefly interest income of ¥60 million against ¥17 million, and non-operating expenses fell to ¥26 million from ¥83 million as donations paid dropped to ¥21 million from ¥69 million. That is why ordinary profit grew 5.1%.
Two items then took the gain back. The prior year had included ¥252 million of extraordinary gains, mostly a ¥239 million profit on selling investment securities; this year there were none, while an impairment loss of ¥170 million (¥148 million a year earlier) left pre-tax profit 0.4% lower at ¥4,107 million. Income taxes rose to ¥1,217 million from ¥1,167 million, an effective rate of about 29.6% against 28.3%: current taxes fell to ¥761 million from ¥1,365 million, but deferred taxes swung from a ¥197 million credit to a ¥455 million charge. Net profit came out 2.3% lower. The filing does not comment on the tax movement.
Deposits received drove a one-third jump in the balance sheet
Total assets rose 32.9% to ¥36,226 million, an increase of ¥8,961 million, chiefly from other receivables up ¥4,626 million, construction in progress up ¥1,654 million and machinery and equipment up ¥1,235 million. Liabilities rose ¥8,084 million to ¥19,128 million because deposits received rose ¥11,053 million to ¥15,822 million, more than offsetting a ¥1,706 million fall in the sales-promotion provision and a ¥712 million fall in income taxes payable; the filing does not say what the deposits relate to. Net assets rose only ¥876 million, to ¥17,098 million — ¥2,890 million of profit less ¥1,457 million of dividends and ¥502 million of share buybacks — so the equity ratio fell to 47.0% from 59.3%. That is the effect of a larger balance sheet, not of lower equity. One subsidiary, Cyber Consultant, left the consolidation scope during the year.
The same line dominates cash flow. Operating cash flow rose to ¥7,442 million from ¥4,816 million, but the ¥11,052 million increase in deposits received alone exceeds that whole inflow; against it stood a ¥4,645 million increase in other receivables, the ¥1,706 million fall in the promotion provision and ¥1,437 million of taxes paid. The investing outflow of ¥2,862 million was mainly ¥3,289 million of tangible fixed-asset purchases and ¥999 million of securities, partly offset by a ¥1,500 million net fall in time deposits. The filing does not itemise the capital spending, but its narrative describes a green-energy build-out over the same year: 29 solar plants started operating, taking the total to 51, and a grid-scale battery storage station connected in November 2025 entered the balancing market in March 2026. That business is not listed in either segment; revenue not attributed to a reportable segment rose to ¥304 million from ¥63 million. Cash and equivalents closed at ¥19,973 million, up ¥2,477 million, after ¥1,456 million of dividends paid and ¥502 million of buybacks.
Flat revenue, higher profit guided for FY7/2027 — and an unchanged ¥27 dividend
For FY7/2027 i-mobile guides revenue of ¥22,200 million (+0.2%), operating profit of ¥4,500 million (+7.7%), ordinary profit of ¥4,530 million (+5.9%) and net profit of ¥3,140 million (+8.6%), for earnings per share of ¥57.00. The earnings report itself gives no reason for profit growing on flat revenue; it refers readers to results presentation materials released at the same time. In its narrative, management says it is rebuilding the ad-network business around combined product solutions and revised customer targets, and on February 1, 2026 it merged the ad-network, influencer-marketing and media-solution businesses into a single Internet Marketing business.
The FY7/2026 dividend is ¥27.00 per share, paid entirely at the year end, against ¥26.00, for a total of ¥1,487 million and a payout ratio of 52.3%; the board resolved it on September 10, 2026 and payment starts on October 5, 2026. For FY7/2027 the company plans the same ¥27.00, made up of a ¥20.00 ordinary dividend and a ¥7.00 commemorative dividend for the 20th anniversary of its founding, a payout of 47.4% on guided earnings. The policy for FY7/2024 through FY7/2027 targets a payout ratio of around 50% plus flexible buybacks; under it the company bought 1,009,700 shares for ¥502 million between June 12 and June 30, 2026, taking treasury stock to 3,062,015 shares out of 58,147,188 issued. After the year end, the board resolved on August 24, 2026 to issue paid and free stock acquisition rights, allotted on September 9, and on August 31, 2026 the company signed a syndicated committed credit line; the filing gives no amounts for either.
| Metric | FY7/2026 | FY7/2025 | Change |
|---|---|---|---|
| Revenue (¥ million) | 22,146 | 21,528 | +2.9% |
| SG&A expenses (¥ million) | 17,749 | 17,367 | +2.2% |
| Operating profit (¥ million) | 4,177 | 4,133 | +1.1% |
| Operating margin | 18.9% | 19.2% | −0.3 pt |
| Ordinary profit (¥ million) | 4,277 | 4,069 | +5.1% |
| Pre-tax profit (¥ million) | 4,107 | 4,124 | −0.4% |
| Net profit attrib. to owners of parent (¥ million) | 2,890 | 2,957 | −2.3% |
| EPS (¥) | 51.64 | 51.40 | +0.5% |
| Return on equity | 17.4% | 18.7% | −1.3 pt |
| Consumer — revenue (¥ million) | 19,538 | 19,059 | +2.5% |
| Consumer — segment profit (¥ million) | 4,101 | 4,021 | +2.0% |
| Internet Advertising — revenue (¥ million) | 2,316 | 2,411 | −4.0% |
| Internet Advertising — segment profit (¥ million) | 74 | 153 | −51.4% |
| Total assets (¥ million) | 36,226 | 27,264 | +32.9% |
| Deposits received (¥ million) | 15,822 | 4,769 | +231.8% |
| Net assets (¥ million) | 17,098 | 16,221 | +5.4% |
| Equity ratio | 47.0% | 59.3% | −12.3 pt |
| Operating cash flow (¥ million) | 7,442 | 4,816 | +54.5% |
| Cash and equivalents at year end (¥ million) | 19,973 | 17,496 | +14.2% |
| FY7/2027 guidance — revenue (¥ million) | 22,200 | — | +0.2% |
| FY7/2027 guidance — operating profit (¥ million) | 4,500 | — | +7.7% |
| FY7/2027 guidance — ordinary profit (¥ million) | 4,530 | — | +5.9% |
| FY7/2027 guidance — net profit (¥ million) | 3,140 | — | +8.6% |
| FY7/2027 guidance — EPS (¥) | 57.00 | — | +10.4% |
| Annual dividend per share (¥) | 27.00 | 27.00 | unchanged |
| Dividend payout ratio | 47.4% | 52.3% | −4.9 pt |
JapanStockPulse provides informational content only and does not constitute investment advice. Figures are taken from the company's published earnings short report and may be subject to subsequent revision.