Sales up for a fifth straight year, net profit down 88.2%
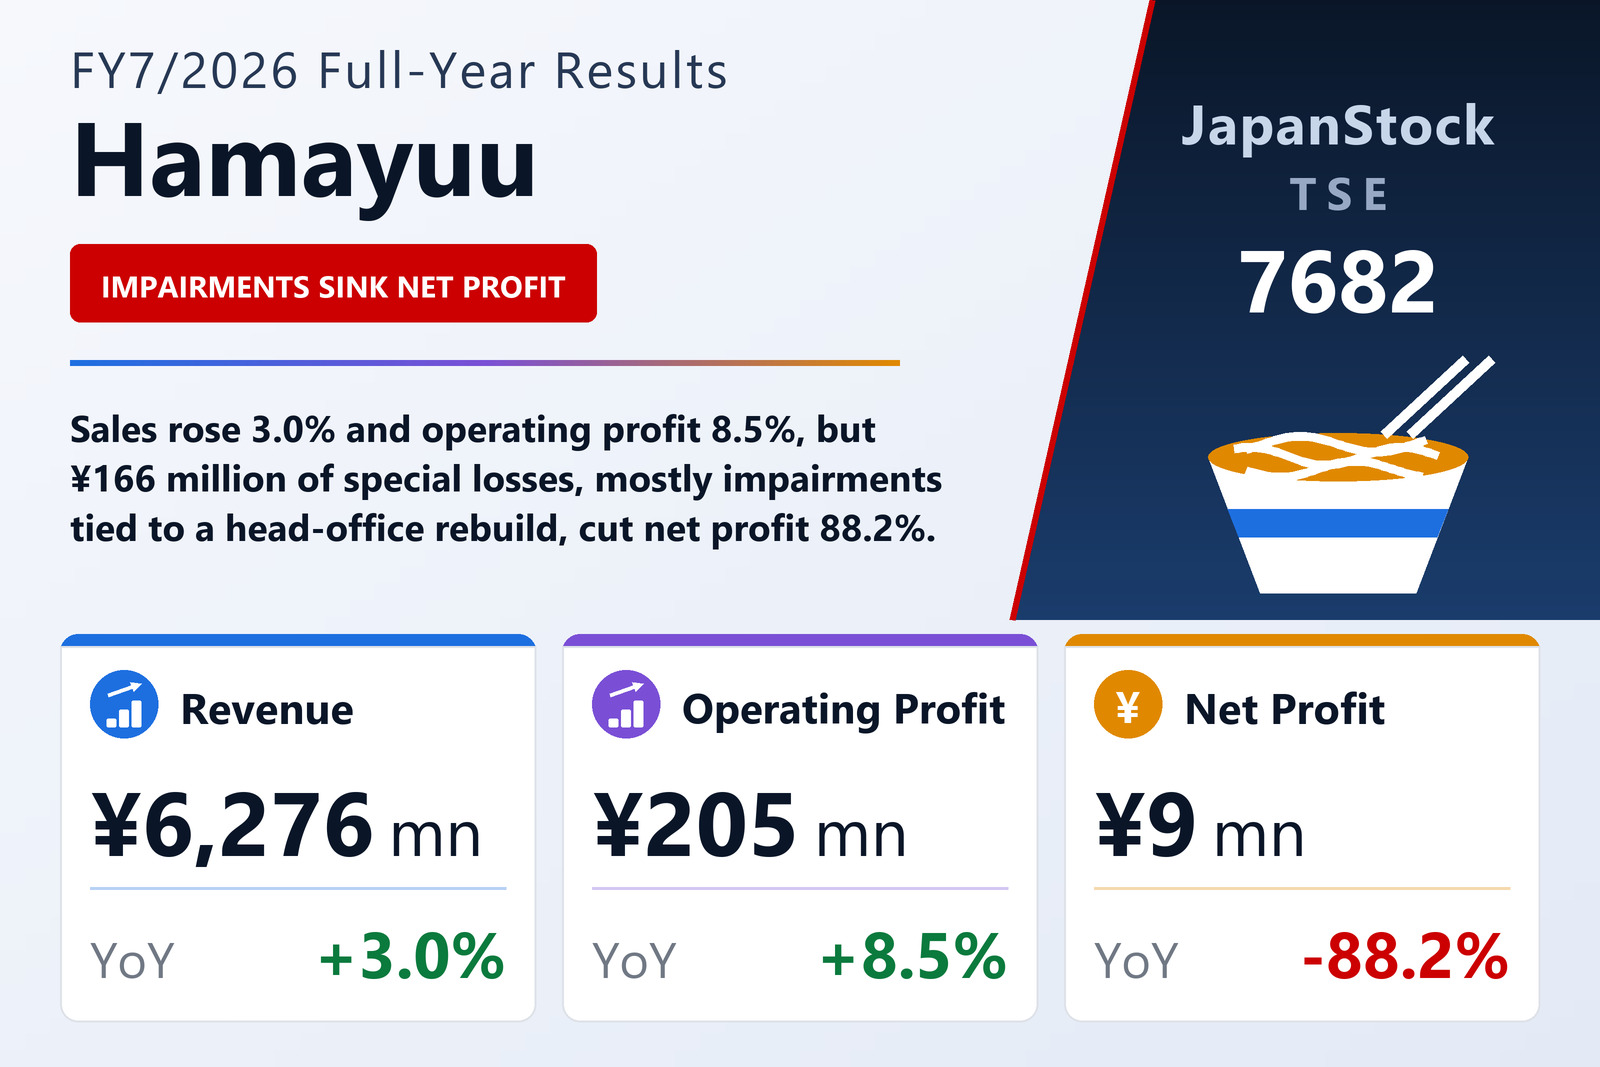
HAMAYUU CO., LTD. (TSE: 7682), which operates Chinese restaurants — 31 of its 43 outlets carry the Hamayuu name — published non-consolidated results for the fiscal year from August 1, 2025 to July 31, 2026 on September 10, 2026, under Japanese GAAP. Net sales rose 3.0% to ¥6,276 million, the fifth consecutive year of growth; operating profit rose 8.5% to ¥205 million and ordinary profit 7.9% to ¥207 million. Net profit fell 88.2% to ¥9 million from ¥81 million, and earnings per share to ¥4.43 from ¥37.56. The company is listed on the Tokyo Stock Exchange Standard market and on the Nagoya Stock Exchange Main market.
Sales grew by ¥184 million, which the company attributes to two new outlets, one of them a restaurant it runs under contract, and to the renovation of three existing ones. Cost of sales rose only 1.4% to ¥1,609 million: ingredient prices kept rising, the company says, but cost control brought the cost-of-sales ratio down from 26.0% to 25.6%, and gross profit rose 3.6% to ¥4,667 million. Selling, general and administrative expenses rose 3.4% to ¥4,461 million, lifting their share of sales from 70.8% to 71.1% and absorbing most of that gain — salaries and allowances grew 5.0% to ¥2,042 million and depreciation within SG&A 17.7% to ¥187 million, while rent rose 2.0% to ¥414 million. The operating margin edged up from 3.1% to 3.3%. Non-operating items netted to about ¥2 million, with interest expense up to ¥16.9 million from ¥13.3 million.
Impairments for a rebuild and a restructuring took the profit
Below ordinary profit the year carried extraordinary losses of ¥166 million against ¥48 million, of which impairment losses were ¥165.9 million against ¥27.7 million; extraordinary gains were only ¥1.4 million, from the sale of fixed assets. The company gives two reasons for the impairments: the decision to rebuild its head-office building and the Hamayuu Yamate-dori Honten restaurant, and a decision to reorganise some of its restaurant formats to optimise how it allocates resources. The filing does not name those formats; it says the company will now concentrate resources on Hamayuu, its main format. Pre-tax profit fell 71.5% to ¥42 million. Income taxes of ¥32.8 million — ¥65.8 million of current taxes less a ¥33.0 million deferred-tax credit — took about 77% of that, leaving net profit of ¥9.6 million.
Two openings, three renovations, no closures
The company describes a restaurant market in which inbound tourism kept demand for eating out broadly firm, while higher ingredient prices and a chronic labour shortage pushed operating costs up across the board and prolonged inflation and falling real wages made consumers more careful with money. In October 2025 it opened Meito Saikan in Nagoya's Meito ward, a new format that uses premises left fitted out by a previous tenant to keep the initial investment low, and in the same month began running the restaurant at the Aichi Country Club under an operating contract. It renovated and reopened Hamayuu Gifu Kenchomae in October 2025, Hamayuu Kokubunji Kitamachi in Tokyo in November 2025 and Hamayuu Iwatsuka in Nagoya in July 2026.
With no closures or format changes, the year ended with 43 outlets, all directly operated: 31 Hamayuu, three Shikitei, three Tourikei, four Chugoku Shokudo Hamayuu, one Meito Saikan and the Aichi Country Club restaurant. As part of making the workplace easier for staff, every outlet also closed on four days — August 18, December 31, January 6 and January 7.
Cash fell ¥316 million as the company repaid debt
Total assets fell 4.4% to ¥4,516 million, mainly because cash and deposits fell ¥321 million. Liabilities fell to ¥2,908 million from ¥3,116 million: long-term borrowings, including the current portion, came down from ¥1,565 million to ¥1,319 million, and ¥200 million of bonds moved into current liabilities as they fall due within a year. Net assets were essentially flat at ¥1,607 million — ¥23 million of newly issued shares against a ¥22 million fall in retained earnings, as ¥32 million of dividends exceeded the year's profit — and on the smaller balance sheet the equity ratio rose from 34.0% to 35.6%.
Operating cash flow was ¥360 million against ¥349 million, helped by ¥224 million of depreciation and by the impairment charge, neither of which used cash. Investing activities used ¥347 million, mainly ¥332 million for property and equipment, against ¥451 million a year earlier. Financing used ¥328 million, chiefly ¥246 million of loan repayments and ¥48 million of lease payments, where a year earlier ¥550 million of new long-term borrowing had made it an inflow of ¥214 million. Cash and cash equivalents ended the year at ¥864 million, down ¥316 million.
A 50-year-old flagship comes down, and guidance falls
The head-office building and Hamayuu Yamate-dori Honten are more than 50 years old and ageing, and both are to be demolished and rebuilt on the same site between September 2026 and the end of November 2027 (planned). The Honten closed temporarily on August 31, 2026 and is scheduled to reopen in December 2027. The company expects a harsh environment — energy prices pushed up by geopolitical risk, further rises in ingredient, labour and logistics costs, and a deepening labour shortage — and plans to revitalise existing outlets and to push digitalisation and labour-saving measures in its restaurants.
For FY7/2027 it forecasts net sales of ¥6,075 million (−3.2%), operating profit of ¥153 million (−25.2%), ordinary profit of ¥156 million (−24.8%) and net profit of ¥86 million (+797.0%), or ¥39.76 per share. The filing presents these figures as the result of the conditions and the rebuild described above, but does not say how much of the sales decline comes from the Honten's closure. The net-profit increase is measured from a base the impairments depressed and says little on its own; at the operating line the company is guiding to a fall of a quarter.
The dividend rises to ¥17.00 on a year of ¥4.43 in earnings
The year-end dividend was raised to ¥17.00 from ¥15.00, a total of ¥36 million, with payment to start on October 13, 2026. Against earnings of ¥4.43 per share that is a payout ratio of 383.5%, compared with 39.9% a year earlier. The company forecasts an unchanged ¥17.00 for FY7/2027, a payout of 42.8% of the guided earnings. Return on equity was 0.6% against 5.2%.
| Metric | FY7/2026 | FY7/2025 | Change |
|---|---|---|---|
| Net sales (¥ million) | 6,276 | 6,092 | +3.0% |
| Gross profit (¥ million) | 4,667 | 4,505 | +3.6% |
| Gross margin | 74.4% | 74.0% | +0.4 pt |
| SG&A expenses (¥ million) | 4,461 | 4,316 | +3.4% |
| Operating profit (¥ million) | 205 | 189 | +8.5% |
| Operating margin | 3.3% | 3.1% | +0.2 pt |
| Ordinary profit (¥ million) | 207 | 192 | +7.9% |
| Extraordinary losses (¥ million) | 166 | 48 | +241.0% |
| Pre-tax profit (¥ million) | 42 | 148 | −71.5% |
| Net profit (¥ million) | 9 | 81 | −88.2% |
| EPS (¥) | 4.43 | 37.56 | −88.2% |
| Restaurants at year end | 43 | 41 | +4.9% |
| Operating cash flow (¥ million) | 360 | 349 | +3.0% |
| Total assets (¥ million) | 4,516 | 4,723 | −4.4% |
| Net assets (¥ million) | 1,607 | 1,606 | +0.1% |
| Equity ratio | 35.6% | 34.0% | +1.6 pt |
| FY7/2027 guidance — revenue (¥ million) | 6,075 | — | −3.2% |
| FY7/2027 guidance — operating profit (¥ million) | 153 | — | −25.2% |
| FY7/2027 guidance — ordinary profit (¥ million) | 156 | — | −24.8% |
| FY7/2027 guidance — net profit (¥ million) | 86 | — | +797.0% |
| FY7/2027 guidance — EPS (¥) | 39.76 | — | +797.5% |
| Annual dividend per share (¥) | 17.00 | 15.00 | +13.3% |
| Dividend payout ratio | 383.5% | 39.9% | +343.6 pt |
JapanStockPulse provides informational content only and does not constitute investment advice. Figures are taken from the company's published earnings short report and may be subject to subsequent revision.