Sales grew 4.4%, costs grew faster, and the operating line lost nearly half
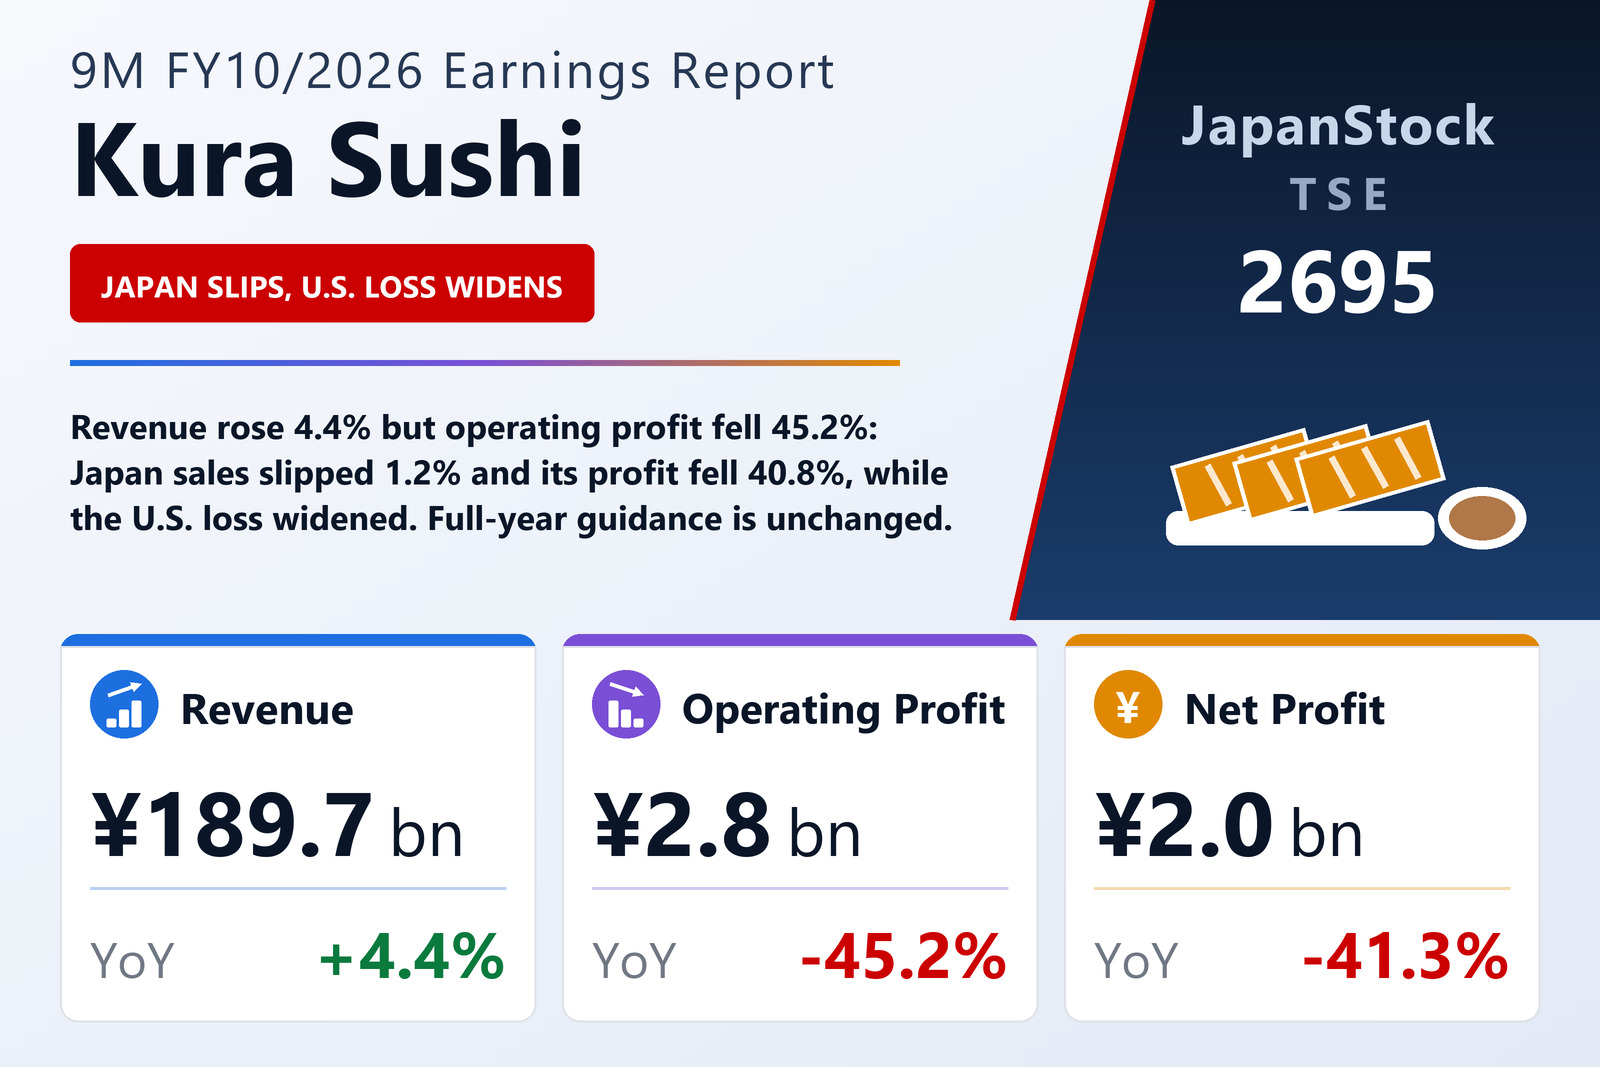
Kura Sushi, Inc. (TSE: 2695), the conveyor-belt sushi chain that runs directly operated restaurants in Japan, the United States and Taiwan, published consolidated results for the first nine months of FY10/2026, the period from November 1, 2025 to July 31, 2026, on September 11, 2026 under Japanese GAAP. Revenue rose 4.4% to ¥189,684 million, but operating profit fell 45.2% to ¥2,845 million, ordinary profit 37.7% to ¥3,469 million and profit attributable to owners of the parent 41.3% to ¥2,030 million. Earnings per share were ¥25.54 against ¥43.55, both figures restated for the two-for-one share split that took effect on May 1, 2026. The filing lists the company on the Tokyo Stock Exchange. The decline also comes on top of a weak comparison: in the same nine months a year earlier, operating profit had already fallen 18.4%.
Cost of sales rose 5.1% to ¥77,856 million, slightly faster than revenue, so gross profit grew only 3.9% to ¥111,827 million and the gross margin eased from 59.2% to 59.0%. The larger move was below that line: selling, general and administrative expenses rose 6.4% to ¥108,982 million, nearly half as fast again as revenue, and their share of sales climbed from 56.4% to 57.5%. On a business whose operating margin was already thin, those two shifts were enough to take it from 2.9% to 1.5% and to remove ¥2,344 million of operating profit — ¥2,845 million against ¥5,189 million. The filing does not itemize the SG&A increase; the causes it names are the industry-wide rise in ingredient prices and labour costs, rice prices that remain high despite signs of having peaked, and tariff-driven ingredient costs in the United States.
Below the operating line, currency helped and one-off charges shrank
Ordinary profit fell 37.7% to ¥3,469 million, a smaller decline than the operating line's 45.2%, because non-operating income rose to ¥935 million from ¥708 million — including a foreign-exchange gain of ¥181 million where a year earlier there had been a ¥20 million loss — while non-operating expenses edged down to ¥311 million from ¥326 million. Interest income of ¥394 million and interest expense of ¥274 million were both slightly lower than a year earlier. Extraordinary losses fell to ¥140 million from ¥460 million: the prior period had carried a ¥122 million loss on cancelled store contracts and ¥259 million of impairment, against ¥53 million of impairment this time. Pre-tax profit was therefore ¥3,328 million, down 34.9%.
The tax line then took back part of that relief. Income taxes were ¥1,535 million, down only 21.1% on a pre-tax profit that fell 34.9%, so the effective rate rose from 38.1% to 46.1%; the filing does not explain the higher rate. Profit for the period fell 43.3% to ¥1,793 million. Profit attributable to owners of the parent came in above that, at ¥2,030 million, because non-controlling interests absorbed a loss of ¥237 million, against ¥296 million a year earlier. Comprehensive income moved the other way, rising 66.4% to ¥5,086 million, almost entirely on a ¥3,295 million gain in foreign-currency translation adjustments — the yen value of the overseas subsidiaries rose even as the group's profit fell.
Japan accounts for more than the whole of the decline
Kura Sushi reports three geographic segments, and their profit is stated at the ordinary-profit level. Japan, at ¥130,930 million of revenue including intersegment sales, is 69% of the group and was the only segment to shrink, down 1.2%; its segment profit fell 40.8% to ¥3,394 million, a drop of ¥2,341 million that exceeds the ¥2,102 million decline in group ordinary profit. The filing sets expanding inbound-tourism demand in city centres against a stagnating consumer mood as real wages continue to fall, and describes a product mix built around premium fairs — domestic wild bluefin tuna, snow crab — alongside the 'super-aged' series from its central kitchens and a 'first plate' health series, with anime tie-ups and a '50th-anniversary festival' campaign, including a QR-coupon service giving one free plate, ahead of the company's fiftieth anniversary in May 2027. On costs it says only that rice remains expensive and that it managed the cost ratio through product-by-product design. The Japan segment margin fell from 4.3% to 2.6%.
North America, the U.S. subsidiary Kura Sushi USA, grew revenue 22.2% to ¥37,204 million on twelve new restaurants — including Orange, California and Denton, Texas — and on collaborations with Tamagotchi and Honkai: Star Rail, but its loss widened to ¥645 million from ¥596 million as tariffs raised ingredient costs. Measured against sales, the loss actually narrowed, from 2.0% of revenue to 1.7%. The company is still targeting sixteen U.S. openings for the full year. Asia, the Taiwan subsidiary, was the bright spot: revenue rose 15.1% to ¥21,845 million and segment profit 42.0% to ¥792 million, on limited-time fairs, a menu widened to eight price tiers, tie-ups with Haikyu!! and DINOTAENG, and a new restaurant in Hualien. In July 2026 the group also established Kura Sushi (Thailand) Co., Ltd. to prepare for openings in Thailand. Across the group, 25 restaurants opened in the nine months — ten in Japan, twelve in the United States and three in Asia — taking the count at July 31 to 712, all directly operated, including 91 in the United States and 63 in Asia.
Leases, not debt, are what grew on the balance sheet
Total assets rose 8.3% to ¥169,038 million from ¥156,015 million at October 31, 2025, an increase of ¥13,022 million that the filing attributes mainly to property, plant and equipment, up ¥14,864 million to ¥111,245 million — within which right-of-use assets rose to ¥39,393 million from ¥32,472 million — and to accounts receivable, up ¥1,526 million, while cash and deposits fell ¥4,053 million to ¥20,118 million. Liabilities rose ¥8,101 million to ¥77,858 million, chiefly on non-current lease obligations, up ¥7,410 million to ¥42,114 million; short-term borrowings were just ¥765 million, down from ¥1,172 million. Net assets rose 5.7% to ¥91,180 million on the ¥2,030 million of profit, a ¥1,369 million rise in translation adjustments and a ¥1,550 million rise in non-controlling interests. Because the balance sheet grew faster than shareholders' equity — ¥64,942 million, up 4.2% — the consolidated equity ratio fell from 40.0% to 38.4%. The parent company on its own, the filing notes, remains effectively debt-free with an equity ratio of 67.9%. No cash-flow statement is prepared for the third quarter; depreciation for the nine months was ¥7,696 million against ¥7,360 million.
Guidance is unchanged, which now requires the strongest quarter of the year
Kura Sushi has not revised the full-year forecast it issued on December 10, 2025: revenue of ¥257,000 million (+4.9%), operating profit of ¥5,000 million (−8.4%), ordinary profit of ¥5,200 million (−15.8%) and profit attributable to owners of ¥3,000 million (−16.8%), for earnings per share of ¥37.74 on the post-split share count (¥75.48 before the split). Nine months in, the group has delivered 73.8% of the guided revenue but only 56.9% of the guided operating profit. The implied fourth quarter is therefore revenue of about ¥67,316 million and operating profit of about ¥2,155 million — more than twice the ¥948 million the first three quarters averaged. The filing simply states that there is no change to the forecast at present, and gives no bridge from the nine-month run rate to the full-year figure.
The dividend row needs the split explained
The dividend forecast is also unchanged, but the share split makes the headline figures hard to read. For FY10/2025 the company paid a single year-end dividend of ¥20.00 per pre-split share. For FY10/2026 it forecasts ¥0.00 at the second-quarter end, stated on a pre-split basis, and ¥15.00 at the year-end, stated per post-split share; because the two halves are on different bases, the filing prints no annual total. It does state that the annual dividend would be ¥30.00 without the split, against ¥20.00 the year before — a 50% increase on a like-for-like basis, and a payout of roughly 40% of the guided earnings per share on either basis.
| Metric | 9M FY10/2026 | 9M FY10/2025 | Change |
|---|---|---|---|
| Revenue (¥ million) | 189,684 | 181,677 | +4.4% |
| Cost of sales (¥ million) | 77,856 | 74,059 | +5.1% |
| Gross profit (¥ million) | 111,827 | 107,617 | +3.9% |
| Gross margin | 59.0% | 59.2% | −0.3 pt |
| SG&A expenses (¥ million) | 108,982 | 102,428 | +6.4% |
| Operating profit (¥ million) | 2,845 | 5,189 | −45.2% |
| Operating margin | 1.5% | 2.9% | −1.4 pt |
| Ordinary profit (¥ million) | 3,469 | 5,571 | −37.7% |
| Extraordinary losses (¥ million) | 140 | 460 | −69.6% |
| Pre-tax profit (¥ million) | 3,328 | 5,111 | −34.9% |
| Net profit attrib. to owners of parent (¥ million) | 2,030 | 3,461 | −41.3% |
| EPS (¥) | 25.54 | 43.55 | −41.3% |
| Comprehensive income (¥ million) | 5,086 | 3,057 | +66.4% |
| Japan — revenue (¥ million) | 130,930 | 132,490 | −1.2% |
| Japan — segment profit (¥ million) | 3,394 | 5,735 | −40.8% |
| North America — revenue (¥ million) | 37,204 | 30,448 | +22.2% |
| North America — segment profit (¥ million) | −645 | −596 | loss widened |
| Asia — revenue (¥ million) | 21,845 | 18,973 | +15.1% |
| Asia — segment profit (¥ million) | 792 | 558 | +42.0% |
| Restaurants at period end (all directly operated) | 712 | — | — |
| Total assets (¥ million) | 169,038 | 156,015 | +8.3% |
| Net assets (¥ million) | 91,180 | 86,258 | +5.7% |
| Shareholders' equity (¥ million) | 64,942 | 62,338 | +4.2% |
| Equity ratio | 38.4% | 40.0% | −1.6 pt |
| FY10/2026 guidance — revenue (¥ million) | 257,000 | — | +4.9% |
| FY10/2026 guidance — operating profit (¥ million) | 5,000 | — | −8.4% |
| FY10/2026 guidance — ordinary profit (¥ million) | 5,200 | — | −15.8% |
| FY10/2026 guidance — net profit (¥ million) | 3,000 | — | −16.8% |
| FY10/2026 guidance — EPS (¥) | 37.74 | — | — |
| FY10/2026 forecast year-end dividend per share, post-split (¥) | 15.00 | — | — |
| Annual dividend per share on a pre-split basis (¥) | 30.00 | 20.00 | +50.0% |
JapanStockPulse provides informational content only and does not constitute investment advice. Figures are taken from the company's published earnings short report and may be subject to subsequent revision.