A ¥1,221 million charge the filing names but does not explain
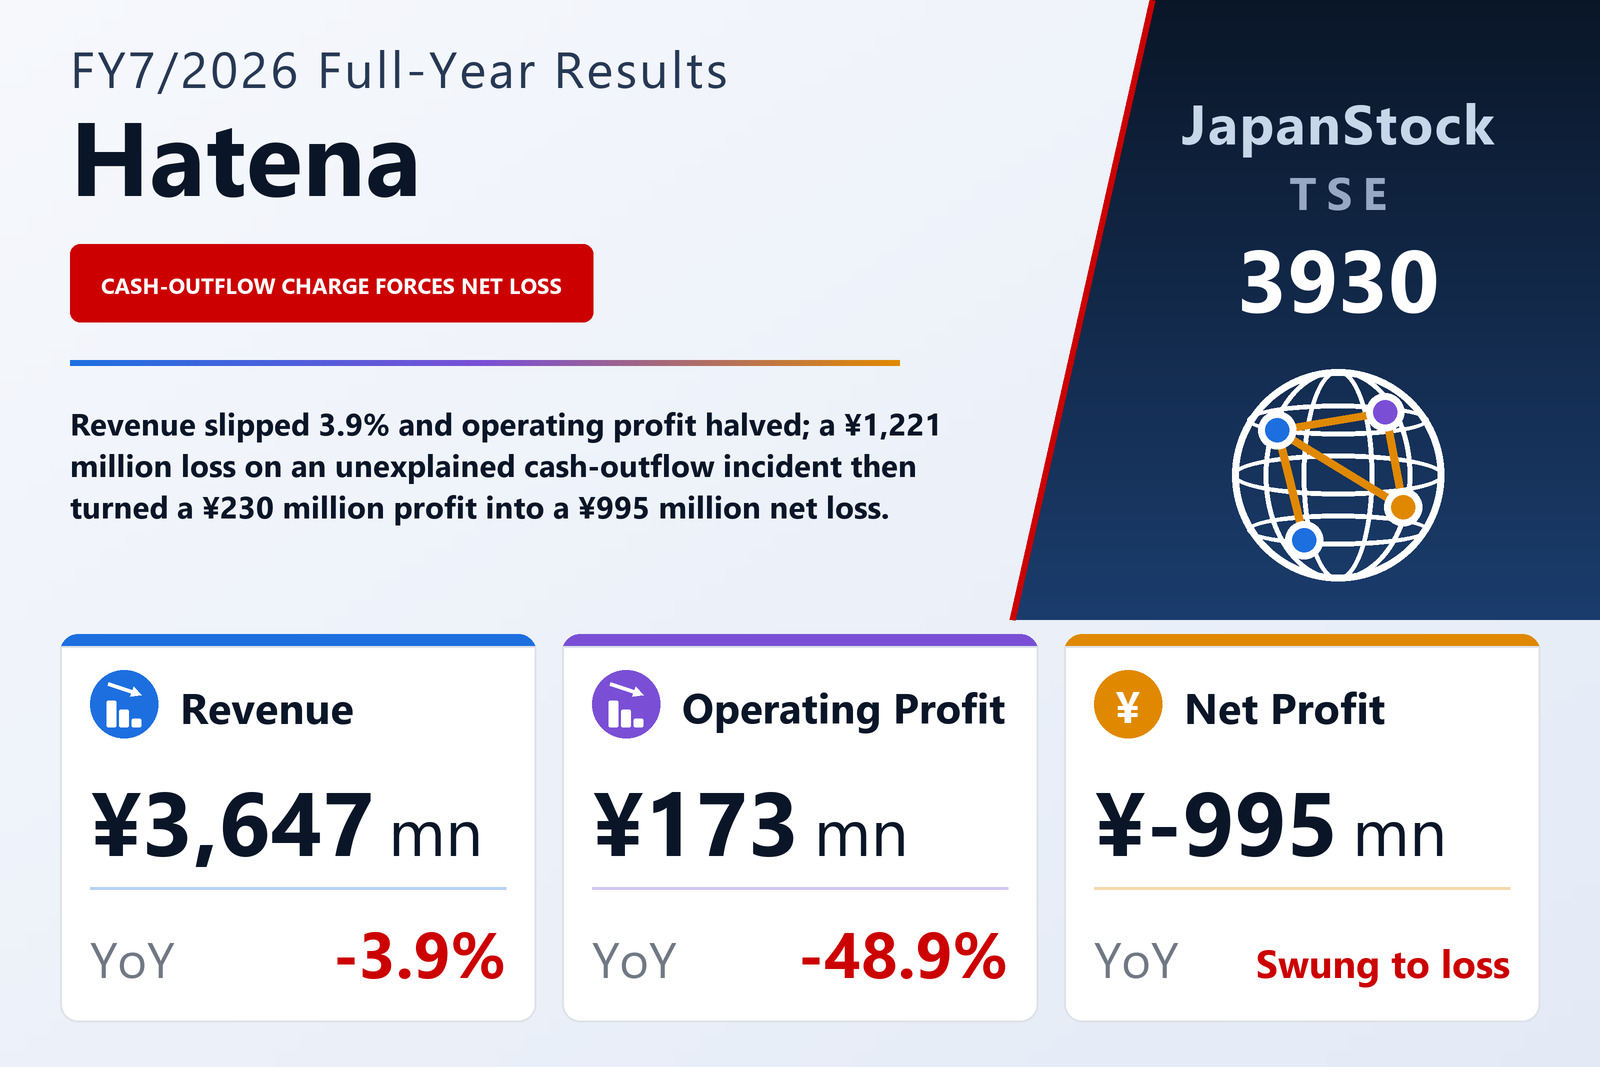
Hatena Co., Ltd. (TSE: 3930), the operator of the Hatena Blog and Hatena Bookmark user-generated-content platforms, the Mackerel server-monitoring service and the GigaViewer manga viewer it supplies to publishers, published non-consolidated results for the fiscal year from August 1, 2025 to July 31, 2026 on September 11, 2026 under Japanese GAAP. Revenue fell 3.9% to ¥3,647 million, operating profit 48.9% to ¥173 million and ordinary profit 69.5% to ¥103 million, and the bottom line swung to a net loss of ¥995 million from a profit of ¥230 million, or a loss of ¥332.80 per share against earnings of ¥77.61. The company is listed on the Tokyo Stock Exchange.
The whole of the swing sits in one line. Extraordinary losses rose to ¥1,223 million from ¥4 million, and ¥1,221 million of that is an item the filing calls a loss associated with a cash-outflow incident. That description is all the tanshin offers: it does not say what the incident was, who was involved or whether any of the money is expected to come back, and the subsequent-events note reports nothing. What the cash-flow statement adds is that the loss is not merely a provision — ¥1,199 million was actually paid out during the year. The charge took the pre-tax line to a loss of ¥1,107 million against a profit of ¥342 million. Income taxes then became a credit of ¥112 million rather than the ¥111 million expense of a year earlier — deferred tax assets rose ¥94 million to ¥149 million, and a ¥20 million refund of prior-year taxes came in — which is why the net loss, at ¥995 million, is smaller than the pre-tax one. The filing flags the recoverability of those deferred tax assets as a key estimate, resting on a medium-term forecast that assumes the three main services grow.
Before the charge: revenue down 3.9%, costs up 0.5%, operating profit halved
Even without the incident the year was a weak one, and the arithmetic is simple. Cost of sales fell 7.7% to ¥505 million, so gross profit slipped only 3.3% to ¥3,141 million and the gross margin edged up to about 86.1% from 85.6%. Selling, general and administrative expenses rose 2.1% to ¥2,968 million, and total operating expenses — cost of sales plus SG&A — came to ¥3,473 million against ¥3,455 million, up 0.5%, which the company describes as broadly within plan. On a business that spends about 95 yen of every 100 it earns, a ¥147 million fall in revenue against a flat cost base is enough to halve the result: the operating margin fell from 8.9% to 4.8%. The cost increases the filing names are advertising spending in the Technology Solution business, higher salaries from active hiring for toitta and other new services — which management calls an important investment in future competitiveness — and rising data-centre fees on managed-hosting contracts where Hatena pays the hosting bill and re-invoices it to the customer.
Below the operating line the drag came from a second, smaller one-off. Non-operating income was ¥12 million — interest and dividends of ¥4 million, a foreign-exchange gain of ¥4 million and small consumption-tax and returned-remuneration items — but non-operating expenses jumped to ¥82 million from ¥10 million. The bulk is a ¥74 million provision for a shareholder-benefit programme marking the tenth anniversary of the company's listing; a ¥4 million valuation loss on crypto-assets and ¥2 million of interest on newly drawn overdraft facilities make up most of the rest. Ordinary profit therefore fell faster than operating profit, 69.5% to ¥103 million, for an ordinary margin of 3.4% against 10.7%. Extraordinary gains of ¥11 million, almost all from selling investment securities — the ¥99 million holding was run down to zero during the year, with sale proceeds of ¥101 million — did little to offset what followed.
Technology Solutions, three quarters of revenue, slipped 2.1% on fewer large deliveries
Hatena reports a single segment, but its revenue note splits the year by service line, and the largest is Technology Solution Services at ¥2,780 million, down 2.1% — about 76% of the total. It bundles contract development and operation of customers' web services and apps with Mackerel, the server-monitoring SaaS. Development and maintenance revenue in the line fell 4.4% to ¥2,014 million while SaaS revenue, which is mostly Mackerel, rose 4.7% to ¥766 million. The filing's explanation for the decline is that fewer large contract-development projects reached delivery: revenue recognised at a point in time fell to ¥72 million from ¥139 million, and custom software recognised over time to ¥259 million from ¥393 million. On the operations side, projects running the GigaViewer manga viewer kept expanding, but the revenue-share income they generate from advertising and paid content proved volatile.
The growth story the company tells is about that viewer. GigaViewer for Apps runs Shueisha's Shonen Jump+ app, which has passed 32 million downloads, and as of the end of August 2026 the web and app versions together were deployed at 18 companies across a cumulative 29 services. The company says the web version is already the de facto standard among manga sites and is pushing app deployments, where views and sales per reader are higher, alongside a new one-stop digital-advertising service, Comic Growth powered by GigaViewer. Mackerel, for its part, launched an application-performance-monitoring function in May 2025, built on the Vaxila distributed-tracing service acquired in June 2024 and on OpenTelemetry-compatible metrics added that November; management says the launch has helped with both existing and new customers and that the service is showing signs of recovery.
Content marketing fell 12.7% as advertisers pulled back; the blog platform slipped 2.8%
Content Marketing Services fell 12.7% to ¥541 million, the steepest decline of the three. Advertising sold through the line dropped 21.8% to ¥133 million and SaaS revenue, chiefly owned-media sites built on Hatena CMS, fell 9.3% to ¥407 million. The filing attributes this to individual clients cutting advertising and marketing budgets and not renewing: the number of Hatena CMS sites in operation ended the year at 147, five fewer than a year earlier. The new product in the line is toitta, an AI interview-analysis SaaS for corporate researchers, which the company says has been well received by prospective customers and to which it has added an ask toitta function that searches accumulated interview data for findings.
Content Platform Services — Hatena Blog and Hatena Bookmark — fell 2.8% to ¥319 million: advertising revenue on the platforms slipped 4.5% to ¥168 million and paid plans 0.9% to ¥150 million. Registered Hatena Blog users kept rising, but subscriptions to the paid Hatena Blog Pro plan and the number of posts fell under competition from social networks, and advertising unit prices, set across the ad networks the platforms rely on, continued to decline. The company launched a new topic-community service, Hatena Parks, in August 2026, after the year-end. Other services — chiefly compensation, paid in JOC tokens, for acting as a validator on the Japan Open Chain blockchain, which Hatena joined in October 2024 — brought in ¥5 million, down 5.4%; the filing does not say which holding the crypto-asset valuation loss above was booked on, but those tokens are the only crypto-asset it describes. Across all lines, advertising revenue fell 13.0% to ¥301 million, development and maintenance 4.4% to ¥2,020 million and SaaS 0.7% to ¥1,324 million. One forward indicator moved the other way: contracted revenue still to be recognised rose to ¥276 million from ¥252 million, of which ¥265 million falls due within a year.
Cash fell 43%, and bank borrowings appeared for the first time
Total assets fell 25.7% to ¥2,564 million. Cash and deposits dropped to ¥1,221 million from ¥2,136 million, a fall of ¥915 million, investment securities went to zero from ¥99 million, and deferred tax assets rose ¥94 million to ¥149 million. Liabilities rose ¥93 million to ¥728 million: ¥250 million of short-term borrowings appeared where there had been none, and the ¥74 million shareholder-benefit provision was booked, while accrued income taxes fell ¥121 million to ¥1 million, accrued expenses ¥54 million and accrued consumption taxes ¥51 million. Net assets fell 34.8% to ¥1,836 million, almost entirely the ¥995 million loss taken out of retained earnings, which ended the year at ¥1,441 million. The equity ratio dropped from 81.6% to 71.6% and book value per share from ¥945.11 to ¥612.97. Issued shares were unchanged at 3,075,200; treasury shares fell to 79,784 from 95,445 as some were disposed of.
Operating activities consumed ¥1,155 million against an inflow of ¥711 million a year earlier, the difference being the pre-tax loss and, within it, the ¥1,199 million paid out on the incident. Stripping that payment out, operations generated roughly ¥44 million after ¥163 million of income-tax payments. Investing activities produced a net inflow of ¥2 million — ¥101 million from the securities sale and ¥14 million from a matured term deposit covered ¥105 million of software and other intangibles and ¥20 million of equipment — and financing brought in ¥249 million, being the ¥250 million of overdraft drawings. Cash and equivalents ended the year at ¥1,221 million, down ¥900 million. The company puts that at 4.0 months of average monthly sales and calls its liquidity sufficient; it holds overdraft facilities totalling ¥1,700 million with five banks, of which ¥1,450 million was undrawn at year-end. There is no going-concern note.
Guidance: revenue up 8.8%, operating profit down again, a ¥117 million net profit — and no dividend
For FY7/2027 Hatena guides to revenue of ¥3,968 million (+8.8%), operating profit of ¥159 million (−7.9%), ordinary profit of ¥121 million (+17.3%) and a net profit of ¥117 million, for earnings of ¥39.09 per share; it publishes no first-half forecast. Operating profit is guided lower despite the revenue growth, consistent with the company's stated intention to keep investing in staff and in service quality while managing fixed costs more tightly. Ordinary profit is nonetheless expected to rise, which fits a year in which the ¥74 million anniversary provision does not recur. The priorities named are the same three services: marketing support for publishers alongside GigaViewer, OpenTelemetry-based monitoring features to win new Mackerel customers, toitta for corporate researchers, and continued development of Hatena Blog, Hatena Bookmark and Hatena Parks.
There will be no dividend for FY7/2026 — the company had left the year-end payment undecided and has now set it at nil, as it was for FY7/2025 — and the forecast for FY7/2027 is undecided. The one distribution shareholders received this year was the tenth-anniversary benefit programme, whose ¥74 million cost sits in non-operating expenses. Diluted earnings per share are not shown because the year ended in a loss.
| Metric | FY7/2026 | FY7/2025 | Change |
|---|---|---|---|
| Revenue (¥ million) | 3,647 | 3,794 | −3.9% |
| Gross profit (¥ million) | 3,141 | 3,247 | −3.3% |
| Gross margin | 86.1% | 85.6% | +0.5 pt |
| SG&A expenses (¥ million) | 2,968 | 2,907 | +2.1% |
| Operating profit (¥ million) | 173 | 339 | −48.9% |
| Operating margin | 4.8% | 8.9% | −4.1 pt |
| Non-operating expenses (¥ million) | 82 | 10 | n.m. |
| Ordinary profit (¥ million) | 103 | 339 | −69.5% |
| Loss associated with cash-outflow incident (¥ million) | 1,221 | — | new |
| Pre-tax profit (¥ million) | −1,107 | 342 | profit to loss |
| Income taxes (¥ million) | −112 | 111 | n.m. |
| Net profit (¥ million) | −995 | 230 | profit to loss |
| EPS (¥) | −332.80 | 77.61 | profit to loss |
| Technology Solution Services — revenue (¥ million) | 2,780 | 2,839 | −2.1% |
| Content Marketing Services — revenue (¥ million) | 541 | 620 | −12.7% |
| Content Platform Services — revenue (¥ million) | 319 | 328 | −2.8% |
| Other Services — revenue (¥ million) | 5 | 6 | −5.4% |
| Total assets (¥ million) | 2,564 | 3,450 | −25.7% |
| Cash and deposits (¥ million) | 1,221 | 2,136 | −42.8% |
| Short-term borrowings (¥ million) | 250 | — | new |
| Net assets (¥ million) | 1,836 | 2,816 | −34.8% |
| Equity ratio | 71.6% | 81.6% | −10.0 pt |
| Operating cash flow (¥ million) | −1,155 | 711 | n.m. |
| Investing cash flow (¥ million) | 2 | −38 | n.m. |
| Financing cash flow (¥ million) | 249 | 2 | n.m. |
| FY7/2027 guidance — revenue (¥ million) | 3,968 | — | +8.8% |
| FY7/2027 guidance — operating profit (¥ million) | 159 | — | −7.9% |
| FY7/2027 guidance — ordinary profit (¥ million) | 121 | — | +17.3% |
| FY7/2027 guidance — net profit (¥ million) | 117 | — | loss to profit |
| FY7/2027 guidance — EPS (¥) | 39.09 | — | n.m. |
| Annual dividend per share (¥) | — | 0.00 | — |
JapanStockPulse provides informational content only and does not constitute investment advice. Figures are taken from the company's published earnings short report and may be subject to subsequent revision.