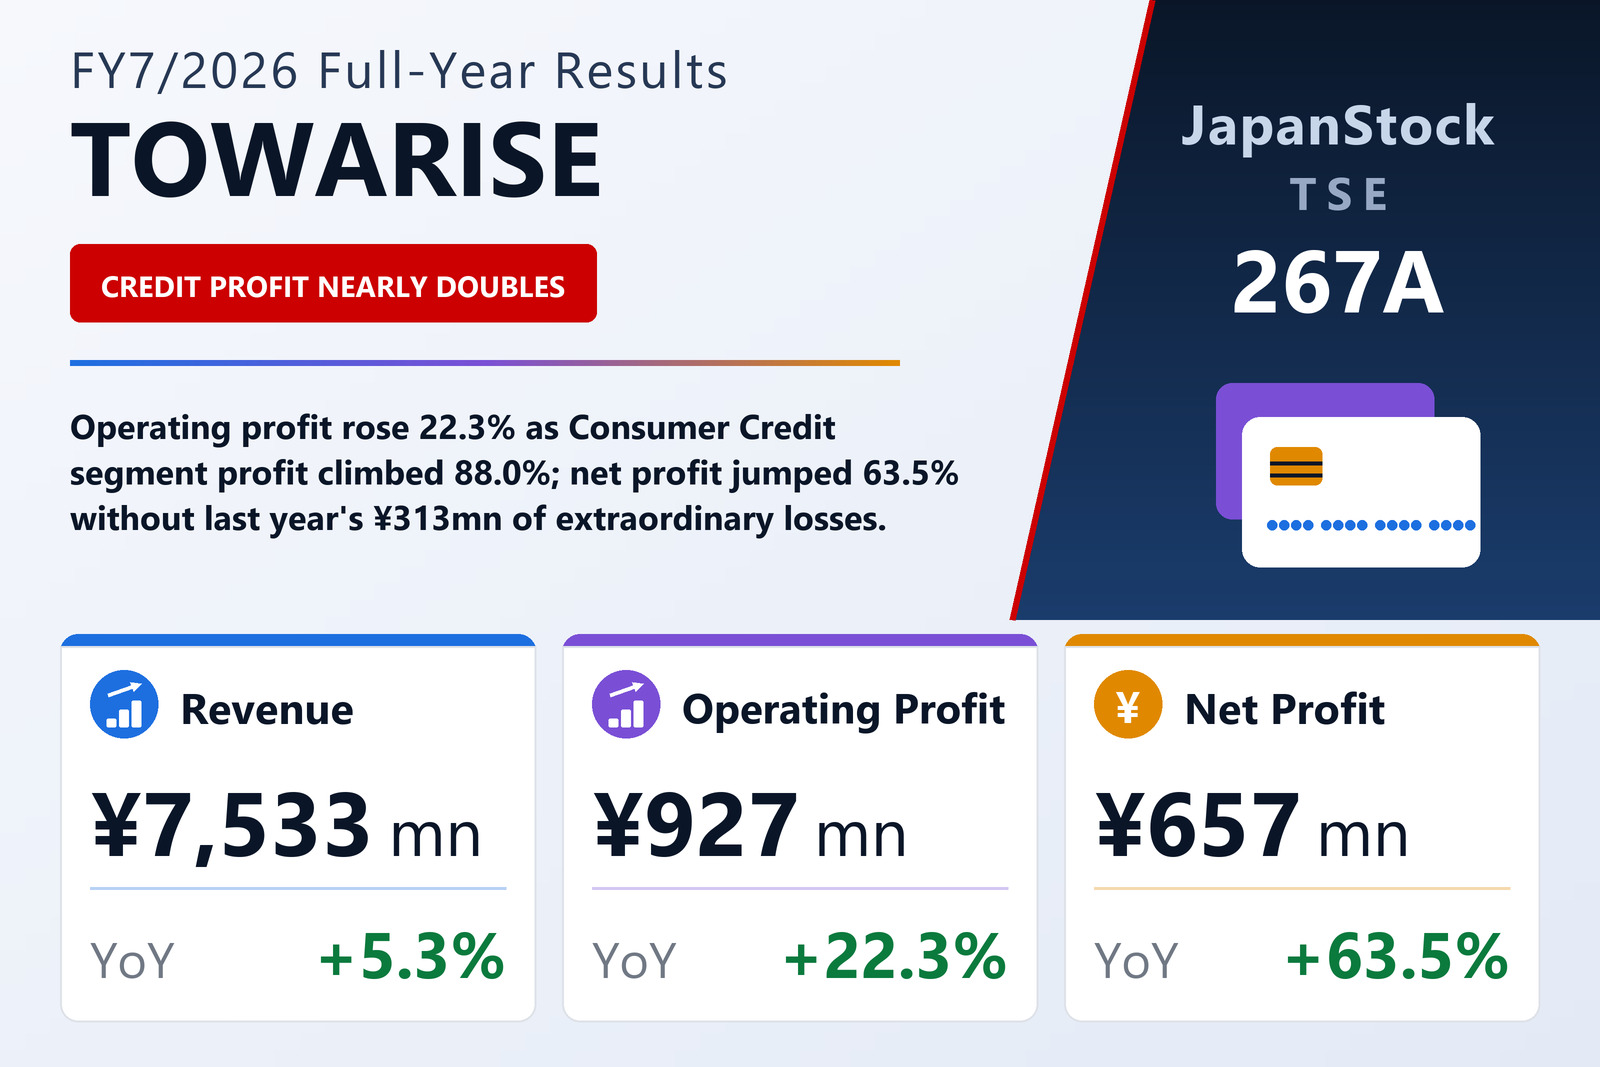
Profit grew far faster than a 5.3% rise in operating revenue
TOWARISE CORPORATION (TSE: 267A), a consumer-credit company that also runs a mobile-phone sales business built around docomo services, published consolidated results for the fiscal year from August 1, 2025 to July 31, 2026 on September 14, 2026, under Japanese GAAP. Its shares trade on the Tokyo Stock Exchange's TOKYO PRO Market, which is open only to professional investors. Operating revenue rose 5.3% to ¥7,533 million, operating profit 22.3% to ¥927 million, ordinary profit 13.3% to ¥958 million and profit attributable to owners of the parent 63.5% to ¥657 million, or ¥652.17 per share against ¥383.49. Return on equity rose to 16.2% from 10.4%. The annual general meeting is scheduled for October 23, 2026, and the company plans to file its Issuer Information report on October 26, 2026.
Operating revenue grew by ¥377 million while total operating expenses rose only ¥209 million, to ¥6,606 million, so operating profit gained ¥169 million and the operating margin widened to 12.3% from 10.6%. Selling, general and administrative expenses actually fell 1.7% to ¥4,079 million. Against that, other operating expenses rose 12.1% to ¥2,116 million and financial expenses 13.9% to ¥410 million; the company notes that repeated policy-rate increases are pushing funding costs up across the consumer-credit industry, and interest paid in the cash-flow statement rose to ¥463 million from ¥371 million. The filing does not itemise other operating expenses.
By revenue line, the mobile-phone business supplied most of the increase: handset sales rose 8.7% to ¥2,044 million and commissions received 24.1% to ¥1,371 million. In credit, revenue from individual installment credit — the shopping-credit business — rose 9.8% to ¥2,141 million, but revenue from comprehensive, card-type installment credit fell 26.5% to ¥319 million, credit guarantee revenue slipped 2.9% to ¥926 million and loan revenue fell to ¥65 million from ¥92 million. Other operating revenue declined to ¥629 million from ¥709 million.
Below the operating line, last year's one-off losses fell away
Ordinary profit grew more slowly than operating profit because non-operating income fell to ¥42 million from ¥97 million: the prior year had included a ¥73 million reversal of the provision for losses on interest repayments, while this year's largest item was a ¥21 million reversal of the provision for losses on debt guarantees. The bigger swing came from extraordinary items. In FY7/2025 the group booked ¥313 million of extraordinary losses — a ¥175 million provision for debt guarantee losses, a ¥74 million impairment loss, ¥56 million of business restructuring costs and ¥7 million of other losses — against a ¥14 million gain on a business transfer. This year extraordinary losses were just ¥5 million, so pre-tax profit rose 74.4% to ¥954 million. Income taxes came to ¥296 million, against ¥145 million a year earlier, when a ¥121 million deferred-tax adjustment reduced the charge.
Earnings per share rose faster than net profit, by 70.1%, because in FY7/2025 ¥15 million of profit went to preferred dividends and was not attributable to common shareholders, leaving ¥386 million for common shares; this year the full ¥657 million was. During the year the company acquired and cancelled all of its Class C preferred shares, a ¥510 million redemption charged to retained earnings, and it reports no diluted earnings per share for FY7/2026 because the potentially dilutive shares ceased to exist. Common shares outstanding were unchanged at 1,008,000.
Consumer Credit profit up 88.0%, Mobile Phone profit up 15.3%
The Consumer Credit segment's revenue from external customers edged up 0.6% to ¥3,689 million, while segment profit rose 88.0% to ¥938 million from ¥499 million; the narrative section of the filing quotes ¥940 million, the segment table ¥938 million. The company says it focused sales on higher-margin areas of its core shopping-credit business and concentrated resources on growth areas, strengthened credit screening and used a scoring model to make approvals faster and more accurate, and, after renewing its website, pushed digital marketing to build a more efficient, pull-based way of acquiring new customers.
Part of that segment gain does not carry through to the consolidated accounts. The credit segment recorded ¥330 million of intersegment revenue this year against none a year earlier, and the adjustment line, which the filing describes as eliminations of intersegment transactions, widened to −¥322 million from −¥2 million. Segment profits before adjustment totalled ¥1,250 million against ¥761 million, while consolidated operating profit rose ¥169 million. The filing does not say what the intersegment transactions were.
The Mobile Phone segment grew revenue 14.4% to ¥3,416 million and segment profit 15.3% to ¥261 million. Total handset unit sales fell after the company revised how it contacts customers due for a device upgrade, but stronger sales of high-end handsets raised the average unit price, and it stepped up proposals encouraging existing customers to get more value from docomo services. The Other businesses, which include a hotel, disability welfare services and administrative services for companies running their own credit programmes, saw external revenue fall 14.6% to ¥428 million while profit rose to ¥49 million from ¥34 million.
Receivables grew, cash fell and operating cash flow turned negative
Total assets rose ¥778 million to ¥42,551 million. Installment receivables increased ¥1,621 million to ¥35,990 million and investment securities ¥572 million to ¥1,181 million, while cash and deposits fell ¥1,561 million to ¥2,134 million. The allowance for doubtful accounts rose to ¥1,773 million from ¥1,563 million. Liabilities rose ¥446 million to ¥38,326 million, chiefly because deferred installment income grew ¥874 million to ¥3,055 million. Borrowings — short-term loans plus long-term loans including the current portion — came to ¥32,536 million against ¥33,067 million, but shifted toward shorter maturities: the current portion of long-term loans rose to ¥6,531 million from ¥3,397 million, while long-term loans fell to ¥4,805 million from ¥8,570 million. Net assets rose ¥332 million to ¥4,224 million, as net profit less the preferred-share redemption and dividends added ¥126 million to retained earnings and unrealised gains on securities rose ¥216 million; the equity ratio improved to 9.9% from 9.3%.
Operating activities used ¥175 million, against an inflow of ¥3,927 million a year earlier. Pre-tax profit of ¥954 million and the ¥874 million rise in deferred installment income were outweighed by a ¥1,652 million increase in trade receivables and ¥463 million of interest paid; in FY7/2025 trade receivables had fallen by ¥2,425 million. Investing activities used ¥339 million, including ¥266 million to buy investment securities and ¥30 million placed in time deposits. Financing used ¥1,077 million, as ¥3,100 million of new long-term borrowing was outweighed by ¥3,730 million of repayments and the ¥510 million preferred-share redemption. Cash and equivalents fell ¥1,591 million to ¥2,104 million.
Guidance calls for lower profit, the dividend doubles, and a subsidiary is absorbed
For FY7/2027 TOWARISE guides operating revenue of ¥7,942 million (+5.4%), operating profit of ¥776 million (−16.3%), ordinary profit of ¥786 million (−18.0%) and profit attributable to owners of the parent of ¥532 million (−18.9%), or ¥528.66 per share. The filing does not give a specific reason for the lower profit forecast. In credit, the company says it will keep scaling back low-profit businesses and concentrating resources on growth areas; it has set up a Tokyo head office to bring its sales headquarters functions into its largest market, and plans a digital-marketing section, closer coordination between inside and field sales, and more investment in staff training. In mobile, it aims to widen customers' use of docomo's financial, payment and content services, encourage docomo use by whole families, raise total ARPU and use AI tools in store operations.
The year-end dividend for FY7/2026 is ¥20.00 per share, double the ¥10.00 paid for FY7/2025, a total of ¥20 million and a payout ratio of 3.1%, with payment scheduled to begin on October 26, 2026. The company forecasts another ¥20.00 for FY7/2027, a payout ratio of 3.8%. After the year-end, on August 1, 2026, TOWARISE absorbed its wholly owned subsidiary FC Partners, which provided payment consulting and collection administration services, under a board resolution of May 18, 2026. The company acquired FC Partners in 2020 and says the merger is intended to consolidate management resources and run the group more efficiently; because the subsidiary was wholly owned, no shares or other consideration were issued, the company's capital was unchanged, and the merger is accounted for as a transaction under common control.
| Metric | FY7/2026 | FY7/2025 | Change |
|---|---|---|---|
| Operating revenue (¥ million) | 7,533 | 7,156 | +5.3% |
| Individual installment credit revenue (¥ million) | 2,141 | 1,950 | +9.8% |
| Comprehensive (card) installment credit revenue (¥ million) | 319 | 434 | −26.5% |
| Credit guarantee revenue (¥ million) | 926 | 954 | −2.9% |
| Mobile phone sales (¥ million) | 2,044 | 1,880 | +8.7% |
| Mobile phone commissions received (¥ million) | 1,371 | 1,105 | +24.1% |
| SG&A expenses (¥ million) | 4,079 | 4,149 | −1.7% |
| Other operating expenses (¥ million) | 2,116 | 1,888 | +12.1% |
| Financial expenses (¥ million) | 410 | 360 | +13.9% |
| Operating profit (¥ million) | 927 | 758 | +22.3% |
| Operating margin | 12.3% | 10.6% | +1.7 pt |
| Ordinary profit (¥ million) | 958 | 846 | +13.3% |
| Extraordinary losses (¥ million) | 5 | 313 | −98.4% |
| Pre-tax profit (¥ million) | 954 | 547 | +74.4% |
| Net profit attrib. to owners of parent (¥ million) | 657 | 402 | +63.5% |
| EPS (¥) | 652.17 | 383.49 | +70.1% |
| Return on equity | 16.2% | 10.4% | +5.8 pt |
| Consumer Credit — revenue (¥ million) | 3,689 | 3,668 | +0.6% |
| Consumer Credit — segment profit (¥ million) | 938 | 499 | +88.0% |
| Mobile Phone — revenue (¥ million) | 3,416 | 2,986 | +14.4% |
| Mobile Phone — segment profit (¥ million) | 261 | 227 | +15.3% |
| Other — revenue (¥ million) | 428 | 501 | −14.6% |
| Other — segment profit (¥ million) | 49 | 34 | +44.1% |
| Adjustments (intersegment eliminations) (¥ million) | −322 | −2 | n.m. |
| Total assets (¥ million) | 42,551 | 41,772 | +1.9% |
| Installment receivables (¥ million) | 35,990 | 34,369 | +4.7% |
| Borrowings (¥ million) | 32,536 | 33,067 | −1.6% |
| Net assets (¥ million) | 4,224 | 3,891 | +8.6% |
| Equity ratio | 9.9% | 9.3% | +0.6 pt |
| Operating cash flow (¥ million) | −175 | 3,927 | n.m. |
| Investing cash flow (¥ million) | −339 | −23 | n.m. |
| Financing cash flow (¥ million) | −1,077 | −1,997 | n.m. |
| Cash and equivalents at year end (¥ million) | 2,104 | 3,696 | −43.1% |
| FY7/2027 guidance — operating revenue (¥ million) | 7,942 | — | +5.4% |
| FY7/2027 guidance — operating profit (¥ million) | 776 | — | −16.3% |
| FY7/2027 guidance — ordinary profit (¥ million) | 786 | — | −18.0% |
| FY7/2027 guidance — net profit (¥ million) | 532 | — | −18.9% |
| FY7/2027 guidance — EPS (¥) | 528.66 | — | — |
| Annual dividend per share (¥) | 20.00 | 10.00 | +100.0% |
JapanStockPulse provides informational content only and does not constitute investment advice. Figures are taken from the company's published earnings short report and may be subject to subsequent revision.