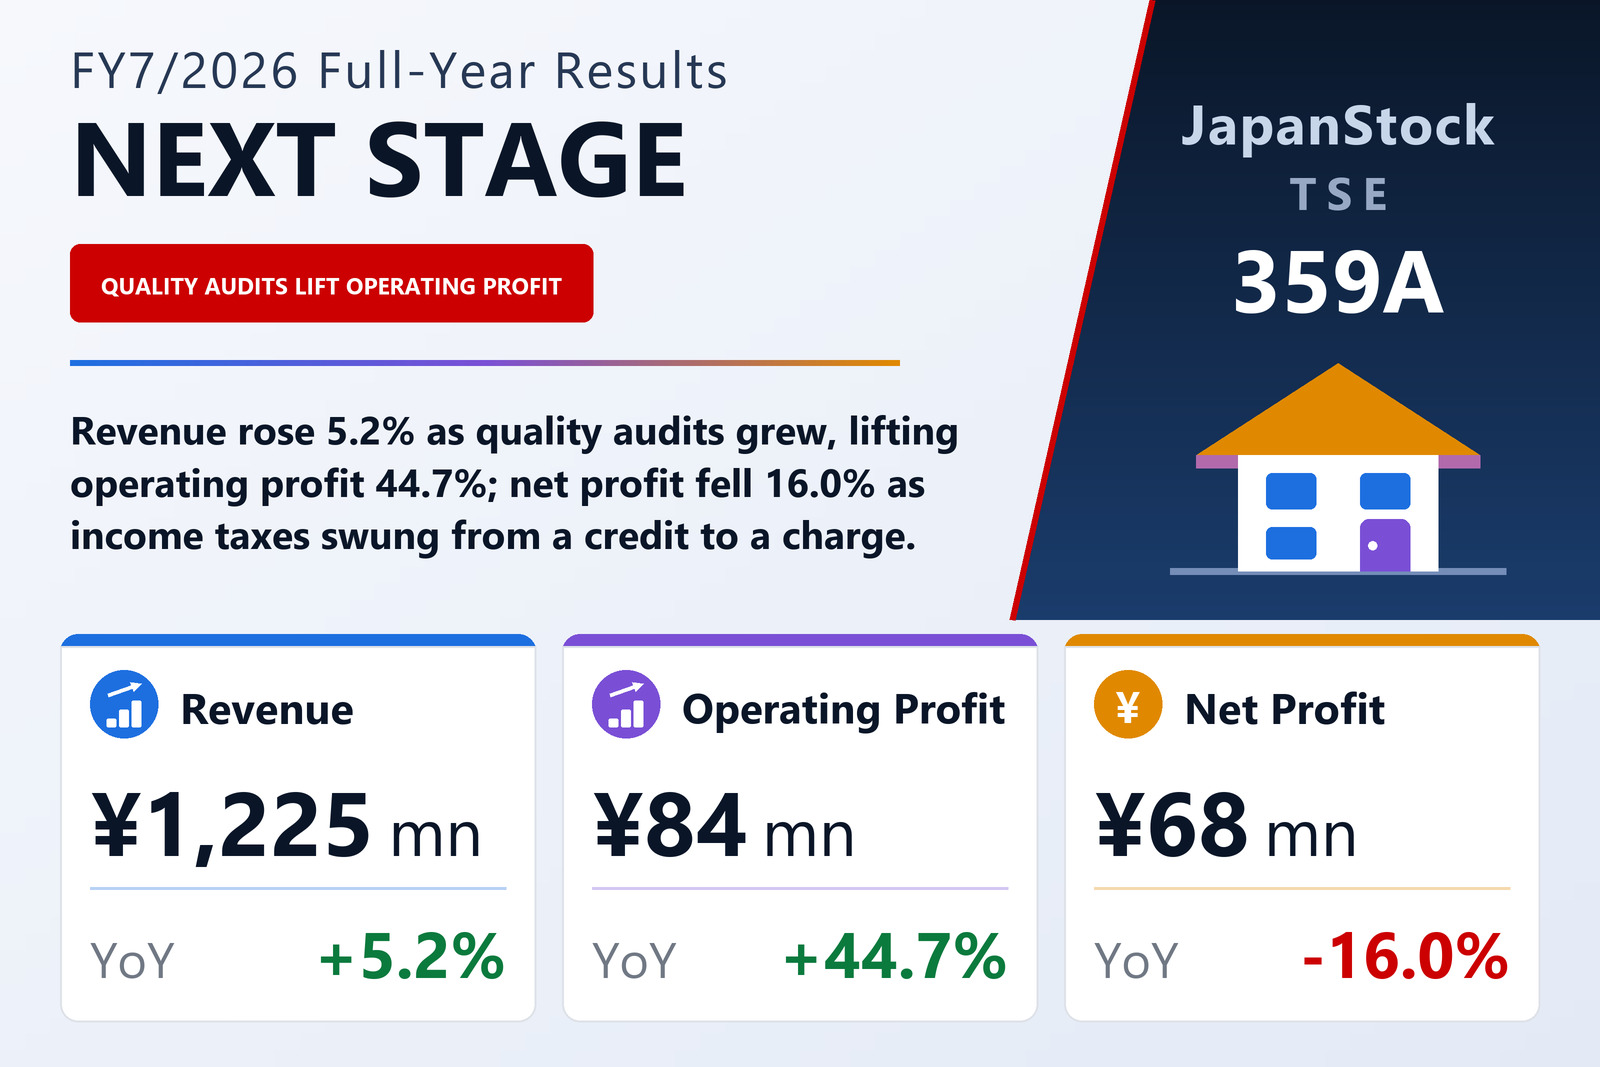
Revenue up 5.2%, operating profit up 44.7%
NEXT STAGE Co., Ltd. (TSE: 359A), an Osaka-based company that sells construction-quality audits, analytics and training services to housebuilders, and whose shares trade on the Tokyo Stock Exchange's TOKYO PRO Market, a market open only to professional investors, published non-consolidated results for the fiscal year from August 1, 2025 to July 31, 2026 on September 14, 2026, under Japanese GAAP. Revenue rose 5.2% to ¥1,225.6 million, operating profit 44.7% to ¥84.0 million and ordinary profit 66.1% to ¥95.1 million, while net profit fell 16.0% to ¥68.8 million, or ¥259.09 per share against ¥308.50. The company holds its annual general meeting on October 30, 2026 and plans to file its annual Issuer Information report the same day. The earnings report is not subject to audit.
The operating result is a matter of costs growing more slowly than sales. Cost of sales rose 3.3% to ¥388.1 million, so gross profit rose 6.1% to ¥837.5 million and the gross margin widened from 67.8% to 68.3%. Selling, general and administrative expenses, by far the largest cost for a service business of this kind, rose 3.1% to ¥753.5 million, falling from 62.8% to 61.5% of revenue. Of the ¥61.0 million of extra revenue, ¥48.4 million reached gross profit and SG&A absorbed ¥22.5 million, leaving operating profit ¥25.9 million higher and the operating margin at 6.9% against 5.0%. The earnings report does not break SG&A down by item.
Quality audits did most of the growing
NEXT STAGE reports a single segment, its housing construction solutions business, but discloses revenue by service. The quality-audit service, which carries out on-site construction audits for housebuilders, brought in ¥906.8 million, up 6.3%, or 74.0% of revenue. The number of audits performed rose 8.4%, from 37,305 to 40,420, which the company attributes to winning many new contracts with leading regional builders that each supply 100 or more new homes a year; new property registrations and brokered defect-insurance policies were also above the prior year. The data and analytics service grew 4.8% to ¥270.5 million, helped by customers taking the QualiZ analytics cloud together with new audit contracts and by functional improvements to the cloud. The learning platform service fell 16.9% to ¥39.9 million: the company concentrated development spending on a renewal of its ACRO5 system during the year and paused its A.C.U hands-on training course for construction engineers. Other revenue was ¥8.4 million against ¥5.5 million.
The growth came in a shrinking market. Citing the Ministry of Land, Infrastructure, Transport and Tourism's building-starts statistics for fiscal 2025, the company says new housing starts fell 12.9% to 711,171 units, with houses built for sale down 12.6% and detached houses down 5.9%. During the year it also developed RePPLI, a construction-navigation app for renovation work intended to take it into the renovation market as a new service line from the next fiscal year, showed it at an industry trade exhibition ahead of launch, and reorganised its marketing department to promote it.
A ¥12.3 million subsidy explains the jump in ordinary profit
Non-operating income rose to ¥15.5 million from ¥2.5 million, almost all of the increase being a ¥12.3 million subsidy granted by the secretariat of Japan's business restructuring subsidy programme, which the company says supported its move to reshape its business toward new areas. The rest was ¥1.6 million of fees received, ¥0.8 million of refunds and ¥0.6 million of interest. Non-operating expenses were ¥4.3 million, including interest of ¥4.0 million against ¥2.8 million. Ordinary profit therefore came to ¥95.1 million, a margin of 7.8% against 4.9%. Without the subsidy it would have been about ¥82.9 million, up 44.7%, the same rate as operating profit, so the extra growth at the ordinary line is the subsidy and nothing else.
Net profit fell because last year's tax line was a credit
There were no extraordinary items this year, against a ¥3.4 million loss on retiring fixed assets a year earlier, so pre-tax profit rose 76.7% to ¥95.1 million. The decline in net profit comes entirely from tax. Current income taxes were ¥0.66 million in both years, but the deferred-tax adjustment moved from a ¥28.7 million credit in FY7/2025 to a ¥25.7 million charge this year, taking total income taxes from a credit of ¥28.1 million, which had lifted last year's net profit above its pre-tax profit, to a charge of ¥26.3 million, an effective rate of 27.7%. Deferred tax assets on the balance sheet fell by the same ¥25.7 million, to ¥12.2 million. The earnings report does not comment on the fall in net profit. Return on equity was 26.8% against 45.1%, and ordinary profit on total assets 13.2% against 9.5%.
Borrowing and operating cash funded software development
Total assets rose ¥180.0 million to ¥808.2 million at July 31, 2026. Cash and deposits increased ¥141.0 million to ¥447.2 million, software in progress rose ¥43.1 million to ¥87.7 million and completed software ¥22.2 million to ¥32.1 million, while deferred tax assets fell ¥25.7 million and buildings ¥4.9 million. Liabilities rose ¥111.2 million to ¥516.6 million, chiefly because long-term borrowings increased ¥82.0 million to ¥240.7 million; with a current portion of ¥48.0 million, bank borrowings totalled ¥288.7 million, well below the cash balance. Consumption taxes payable rose ¥14.9 million and advances received ¥8.8 million, to ¥70.7 million. Net assets rose by exactly the year's net profit, ¥68.8 million, to ¥291.6 million, turning retained earnings from a deficit of ¥58.5 million to a positive ¥10.3 million. The equity ratio was 36.1% against 35.5%, and net assets per share ¥1,097.88 against ¥838.79.
Operating cash flow was ¥145.4 million against ¥84.3 million, built on pre-tax profit of ¥95.1 million, depreciation of ¥17.1 million (¥29.5 million a year earlier), a ¥14.9 million rise in consumption taxes payable and ¥12.3 million of subsidy received. Investing used ¥82.4 million, of which ¥79.9 million went on intangible assets, against ¥36.8 million a year earlier, consistent with the rise in software and software in progress; spending on property and equipment fell to ¥1.4 million from ¥31.4 million. Free cash flow was about ¥62.9 million against ¥21.8 million. Financing brought in ¥78.0 million: ¥130.0 million of new long-term borrowing, less ¥51.4 million of repayments and ¥0.6 million of lease payments. Cash and cash equivalents rose ¥141.0 million to ¥447.2 million.
After the year end, an acquisition, and guidance that does not include it
On July 29, 2026 the board resolved to buy all the shares of Quaranta Co., Ltd., signing the share transfer agreement the same day, and NEXT STAGE acquired 100% of the company on August 3, 2026 for ¥143.1 million in cash, equal to 32% of its year-end cash balance, plus advisory and other costs of ¥16.5 million. Quaranta gives neutral advice to people planning a custom-built home and introduces them to suitable housebuilders, and already runs that service in the Chubu region through a home-building consultation office in Gifu. NEXT STAGE gives three reasons for the deal: Quaranta reached a high operating margin within a short time of its founding and has a stable, locally rooted business; its home-buyer support fits NEXT STAGE's own business for housebuilders; and the company intends to turn the model proven in Gifu Prefecture into a template for other regions. The amount of goodwill and the assets and liabilities acquired have not yet been determined. Because Quaranta is now a subsidiary, NEXT STAGE will prepare consolidated financial statements from the first half of FY7/2027.
Guidance: revenue up 7.8%, operating profit down 34.3%
For FY7/2027 the company forecasts, on a non-consolidated basis, revenue of ¥1,321.4 million (+7.8%), operating profit of ¥55.2 million (−34.3%), ordinary profit of ¥52.0 million (−45.3%) and net profit of ¥34.7 million (−49.5%), or ¥130.73 per share. That implies an operating margin of about 4.2% against 6.9% this year, and ordinary profit ¥3.2 million below operating profit, where this year it was ¥11.1 million above it. The company links the forecast to a renewal of the systems behind its existing services and its new entry into the renovation market, but does not quantify either. Its plans include expanding the Japan Housing Quality Award, an event at which housebuilders compete on construction quality; rolling out a home-building counter business for consumers across regions, including through M&A, adding its scores of builders' technical skills and a second-opinion service that supports buyers through to handover; spreading RePPLI; and renewing ACRO5 so that it can grow into a media platform. The forecast does not consolidate Quaranta: the company says its consolidated forecast for FY7/2027 is still under review and will be announced promptly once it is ready.
No dividend was paid for FY7/2025 or FY7/2026, and none is forecast for FY7/2027; the earnings report gives no reason. Shares outstanding were unchanged at 265,610, with no treasury stock. Six series of stock options, covering 2,340 subscription rights, were left out of diluted earnings per share because they have no dilutive effect.
| Metric | FY7/2026 | FY7/2025 | Change |
|---|---|---|---|
| Revenue (¥ million) | 1,225 | 1,164 | +5.2% |
| Gross profit (¥ million) | 837 | 789 | +6.1% |
| Gross margin | 68.3% | 67.8% | +0.5 pt |
| SG&A expenses (¥ million) | 753 | 730 | +3.1% |
| Operating profit (¥ million) | 84 | 58 | +44.7% |
| Operating margin | 6.9% | 5.0% | +1.9 pt |
| Subsidy income, non-operating (¥ million) | 12 | 0 | new |
| Ordinary profit (¥ million) | 95 | 57 | +66.1% |
| Pre-tax profit (¥ million) | 95 | 53 | +76.7% |
| Income taxes (¥ million) | 26 | −28 | n.m. |
| Net profit (¥ million) | 68 | 81 | −16.0% |
| EPS (¥) | 259.09 | 308.50 | −16.0% |
| Revenue — quality-audit service (¥ million) | 906 | 852 | +6.3% |
| Revenue — data & analytics service (¥ million) | 270 | 258 | +4.8% |
| Revenue — learning platform service (¥ million) | 39 | 48 | −16.9% |
| Total assets (¥ million) | 808 | 628 | +28.7% |
| Net assets (¥ million) | 291 | 222 | +30.9% |
| Equity ratio | 36.1% | 35.5% | +0.6 pt |
| Long-term borrowings incl. current portion (¥ million) | 288 | 210 | +37.4% |
| Operating cash flow (¥ million) | 145 | 84 | +72.5% |
| Investing cash flow (¥ million) | −82 | −62 | n.m. |
| Financing cash flow (¥ million) | 78 | −53 | n.m. |
| Cash and equivalents at period end (¥ million) | 447 | 306 | +46.0% |
| FY7/2027 guidance — revenue (¥ million) | 1,321 | — | +7.8% |
| FY7/2027 guidance — operating profit (¥ million) | 55 | — | −34.3% |
| FY7/2027 guidance — ordinary profit (¥ million) | 52 | — | −45.3% |
| FY7/2027 guidance — net profit (¥ million) | 34 | — | −49.5% |
| FY7/2027 guidance — EPS (¥) | 130.73 | — | — |
| Annual dividend per share (¥) | 0.00 | 0.00 | unchanged |
JapanStockPulse provides informational content only and does not constitute investment advice. Figures are taken from the company's published earnings short report and may be subject to subsequent revision.