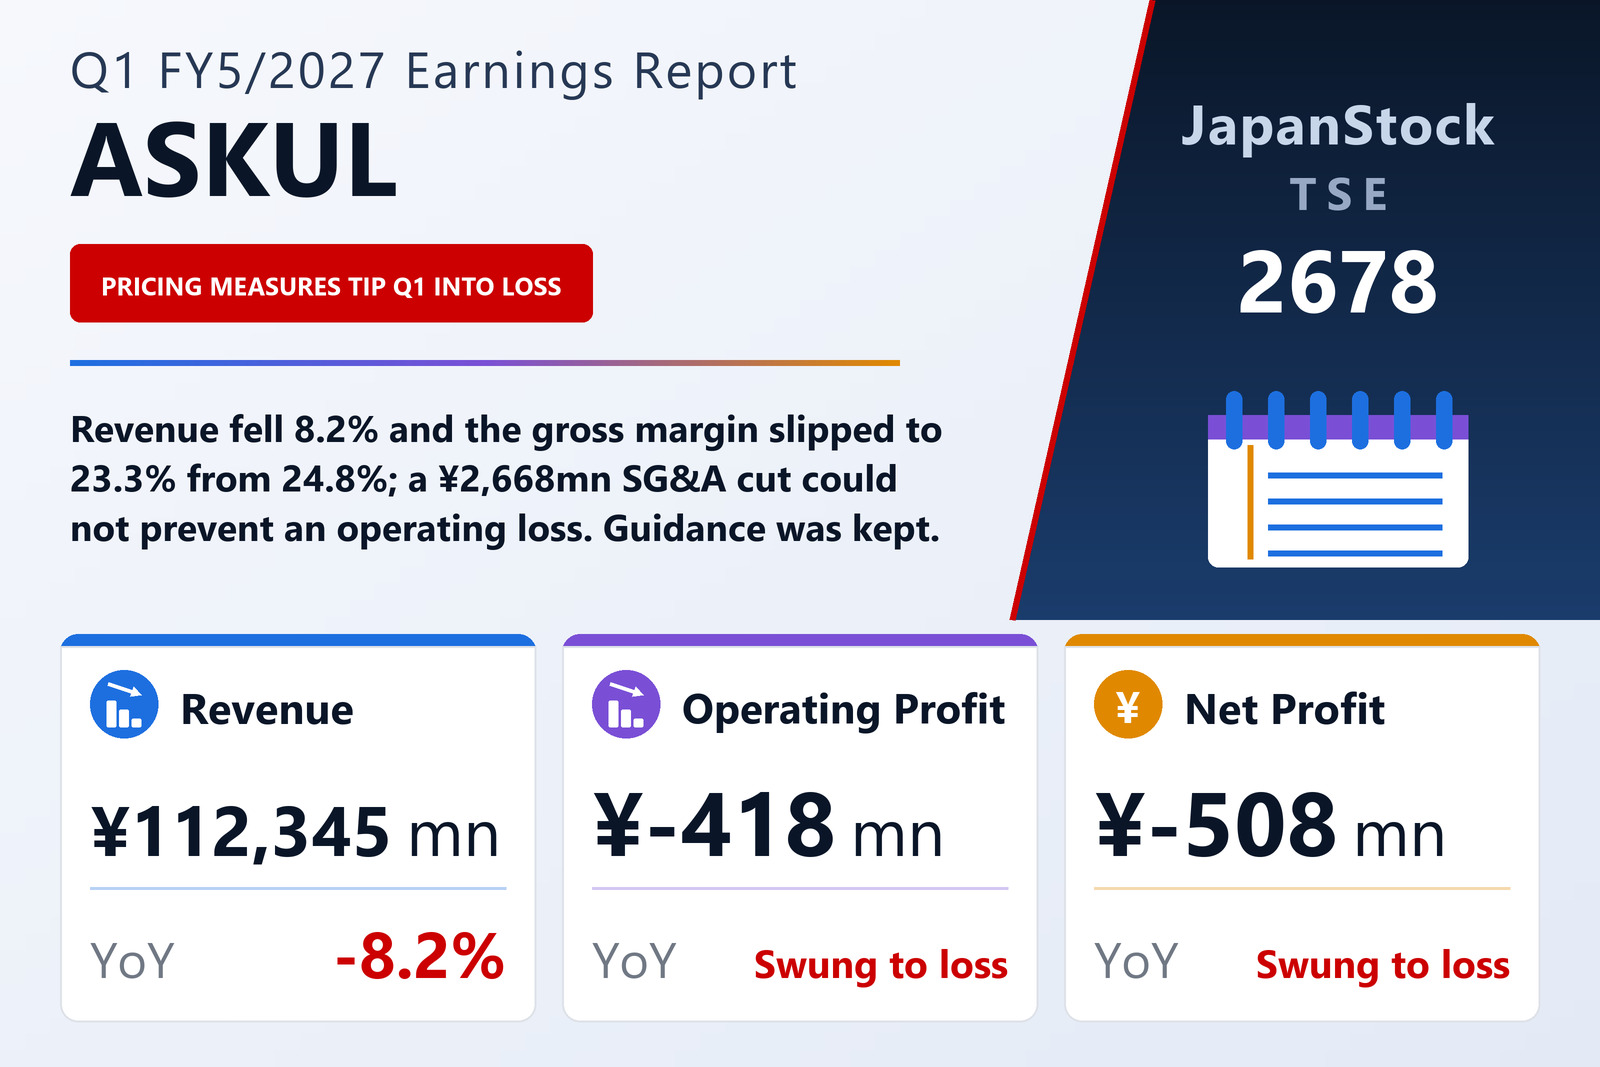
Revenue down 8.2%, and last year's ¥1,053 million profit became a ¥418 million loss
ASKUL Corporation (TSE: 2678), which runs the ASKUL e-commerce business serving workplaces and the LOHACO consumer site alongside logistics and other operations, published consolidated first-quarter results for the three months from May 21 to August 20, 2026 on September 15, 2026 under Japanese GAAP. Revenue fell 8.2% to ¥112,345 million. The company recorded an operating loss of ¥418 million against an operating profit of ¥1,053 million a year earlier, an ordinary loss of ¥452 million against a ¥938 million profit, and a net loss attributable to owners of the parent of ¥508 million against a ¥344 million profit. Earnings per share were −¥5.68 against ¥3.73. The filing lists the shares on the Tokyo Stock Exchange.
The quarter has to be read against the ransomware attack targeting the company on October 19, 2025. ASKUL says it achieved an early restoration of service levels and is pursuing the medium-term plan it published in July 2025, covering FY5/2026 to FY5/2029, built on renewed growth in its retail business and new areas of value. It describes FY5/2027 as the starting year for re-accelerating growth: AI-assisted sales support for the dealers that handle its customers and personalised promotions to win customers back, together with fixed-cost reductions from reorganising logistics sites and company-wide efficiency work. E-commerce revenue, the company says, was in line with its plan at the start of the year but has not yet returned to the level it reached before the attack.
The gross margin fell further than costs could be cut
The arithmetic of the loss sits between revenue and SG&A. Cost of sales fell 6.3% to ¥86,173 million, less than revenue's 8.2%, so gross profit fell 13.7% to ¥26,171 million — ¥4,141 million lower — and the gross margin narrowed from 24.8% to 23.3%. The filing's explanation is that the pricing measures ASKUL introduced last fiscal year to recover sales were still weighing on the margin this quarter. Selling, general and administrative expenses fell 9.1% to ¥26,590 million, a cut of ¥2,668 million that took the SG&A ratio from 23.9% to 23.7%, but that was not enough to offset the lost gross profit. The operating margin went from 0.9% to −0.4%.
The SG&A breakdown shows where the savings came from. Other expenses fell to ¥3,987 million from ¥5,357 million, which the company attributes to the prior year's start-up costs for the ASKUL Kanto DC distribution centre and a new catalogue issued in the ASKUL business at that time. Outsourcing fees fell to ¥2,405 million from ¥3,066 million, mainly because lower sales reduced work inside the distribution centres, and personnel costs fell to ¥6,640 million from ¥7,037 million. Two lines moved the other way as a share of revenue: delivery charges eased to ¥5,836 million from ¥6,010 million but rose from 4.9% to 5.2% of revenue, and software amortisation rose to ¥1,591 million from ¥1,391 million following the replacement of the core system in August 2025.
Below the operating line, a tax credit narrowed the loss
Non-operating income rose to ¥183 million from ¥95 million, including an ¥88 million reversal of system-failure response costs, while interest expense rose to ¥189 million from ¥157 million, leaving an ordinary loss of ¥452 million. Extraordinary losses were ¥22 million, almost all of it losses on the disposal of fixed assets, for a pre-tax loss of ¥474 million against a ¥935 million profit. Income taxes were a net credit of ¥88 million, as a deferred-tax adjustment of −¥507 million outweighed current taxes of ¥418 million, so the quarter's net loss was ¥386 million. Profit attributable to non-controlling interests rose to ¥122 million from ¥94 million, which is why the loss attributable to owners of the parent, at ¥508 million, is larger than the group's net loss. Comprehensive income was −¥412 million against ¥426 million. The average number of shares outstanding fell to 89,533,259 from 92,408,211; the filing does not explain the change.
ASKUL and LOHACO both fell about 12%; the group companies grew
The E-Commerce segment, including intersegment sales, posted revenue of ¥110,700 million, down 7.9%, and a segment loss of ¥393 million against a ¥1,064 million profit; its gross margin was 23.3%, 1.5 points lower, and its SG&A ratio improved by 0.3 points to 23.7%. Within it, the ASKUL business fell 12.2% to ¥79,898 million. The company gives three reasons: sales are still recovering from the attack; seasonal goods such as beverages, food and heatstroke-prevention products did not grow against last summer's intense heat; and demand fell back after special demand linked to the Middle East situation in the previous fiscal year's fourth quarter. Customer numbers among small and medium-sized workplaces are still recovering, while mid-sized and large companies are close to their pre-attack level. The LOHACO business fell 12.3% to ¥8,862 million, hit by the same heat comparison and by the absence of the stockpiled-rice sales it made a year earlier. Group companies and intra-group eliminations rose 14.6% to ¥21,939 million on firm sales at Alpha Purchase and FEED.
The Logistics segment's revenue from logistics work that ASKUL LOGIST performs for customers outside the group fell 25.7% to ¥1,420 million after some outsourcing contracts were revised, and its segment loss widened to ¥53 million from ¥33 million. The Other category, which includes manufacturing, recorded revenue of ¥509 million, down 5.7%, and profit of ¥13 million, down 27.0%, as drinking-water sales at Tsumagoi Meisui, mainly to ASKUL, were sluggish against last year's heat.
A smaller balance sheet, and a slightly higher equity ratio
Total assets fell ¥9,987 million to ¥219,920 million from May 20, 2026. Cash and deposits fell ¥4,412 million to ¥44,920 million, consumption-tax refunds receivable within other current assets fell ¥4,176 million, software in progress fell ¥1,675 million and lease assets ¥1,050 million, while software rose ¥1,100 million. Liabilities fell ¥8,691 million to ¥169,760 million, led by electronically recorded obligations (−¥3,104 million), other accounts payable (−¥2,759 million), notes and accounts payable (−¥2,136 million) and lease obligations (−¥1,102 million). Borrowings were broadly unchanged at ¥44,972 million against ¥45,014 million: short-term loans of ¥27,875 million, current long-term debt of ¥4,549 million and long-term loans of ¥12,548 million.
Net assets fell ¥1,295 million to ¥50,160 million, mainly because retained earnings dropped ¥1,403 million on ¥895 million of dividend payments and the ¥508 million loss. Because total assets shrank faster than equity, the equity ratio rose to 21.1% from 20.8%, on equity of ¥46,379 million against ¥47,805 million. The company did not prepare a cash-flow statement for the quarter; depreciation was ¥3,182 million against ¥3,062 million.
Guidance unchanged, which leaves the rest of the year to carry the profit
ASKUL left unchanged the FY5/2027 guidance it published on July 3, 2026: revenue of ¥490,000 million (+22.4%), operating profit of ¥7,000 million, ordinary profit of ¥6,300 million and net profit attributable to owners of ¥4,000 million, for earnings per share of ¥44.68. The filing prints no percentage change for the three profit lines. The revenue growth rate implies prior-year revenue of about ¥400,300 million. The first quarter delivered 22.9% of guided revenue while losing money, so the remaining nine months would need about ¥377,655 million of revenue, ¥7,418 million of operating profit and ¥4,508 million of net profit for the targets to be met. The filing does not break the guidance down by quarter.
The dividend forecast was also unchanged. After paying ¥10.00 per share for FY5/2026, all of it at the year-end, ASKUL plans ¥10.00 at the second-quarter end and ¥10.00 at the year-end for FY5/2027, an annual ¥20.00 — double the prior year, and about 45% of the guided ¥44.68 of earnings per share.
| Metric | Q1 FY5/2027 | Q1 FY5/2026 | Change |
|---|---|---|---|
| Revenue (¥ million) | 112,345 | 122,324 | −8.2% |
| Gross profit (¥ million) | 26,171 | 30,312 | −13.7% |
| Gross margin | 23.3% | 24.8% | −1.5 pt |
| SG&A expenses (¥ million) | 26,590 | 29,258 | −9.1% |
| Operating profit (¥ million) | −418 | 1,053 | profit to loss |
| Operating margin | −0.4% | 0.9% | −1.3 pt |
| Ordinary profit (¥ million) | −452 | 938 | profit to loss |
| Pre-tax profit (¥ million) | −474 | 935 | profit to loss |
| Net profit attrib. to owners of parent (¥ million) | −508 | 344 | profit to loss |
| Comprehensive income (¥ million) | −412 | 426 | profit to loss |
| EPS (¥) | −5.68 | 3.73 | profit to loss |
| E-Commerce — revenue (¥ million) | 110,700 | 120,249 | −7.9% |
| E-Commerce — segment profit (¥ million) | −393 | 1,064 | profit to loss |
| E-Commerce: ASKUL business — revenue (¥ million) | 79,898 | 91,003 | −12.2% |
| E-Commerce: LOHACO business — revenue (¥ million) | 8,862 | 10,100 | −12.3% |
| E-Commerce: group companies & eliminations — revenue (¥ million) | 21,939 | 19,145 | +14.6% |
| Logistics — revenue (¥ million) | 1,420 | 1,912 | −25.7% |
| Logistics — segment profit (¥ million) | −53 | −33 | loss widened |
| Other — revenue (¥ million) | 509 | 540 | −5.7% |
| Other — segment profit (¥ million) | 13 | 18 | −27.0% |
| Total assets (¥ million) | 219,920 | 229,907 | −4.3% |
| Net assets (¥ million) | 50,160 | 51,455 | −2.5% |
| Cash and deposits (¥ million) | 44,920 | 49,332 | −8.9% |
| Equity ratio | 21.1% | 20.8% | +0.3 pt |
| FY5/2027 guidance — revenue (¥ million) | 490,000 | — | +22.4% |
| FY5/2027 guidance — operating profit (¥ million) | 7,000 | — | n.m. |
| FY5/2027 guidance — ordinary profit (¥ million) | 6,300 | — | n.m. |
| FY5/2027 guidance — net profit (¥ million) | 4,000 | — | n.m. |
| FY5/2027 guidance — EPS (¥) | 44.68 | — | n.m. |
| Annual dividend per share (¥) | 20.00 | 10.00 | +100.0% |
JapanStockPulse provides informational content only and does not constitute investment advice. Figures are taken from the company's published earnings short report and may be subject to subsequent revision.