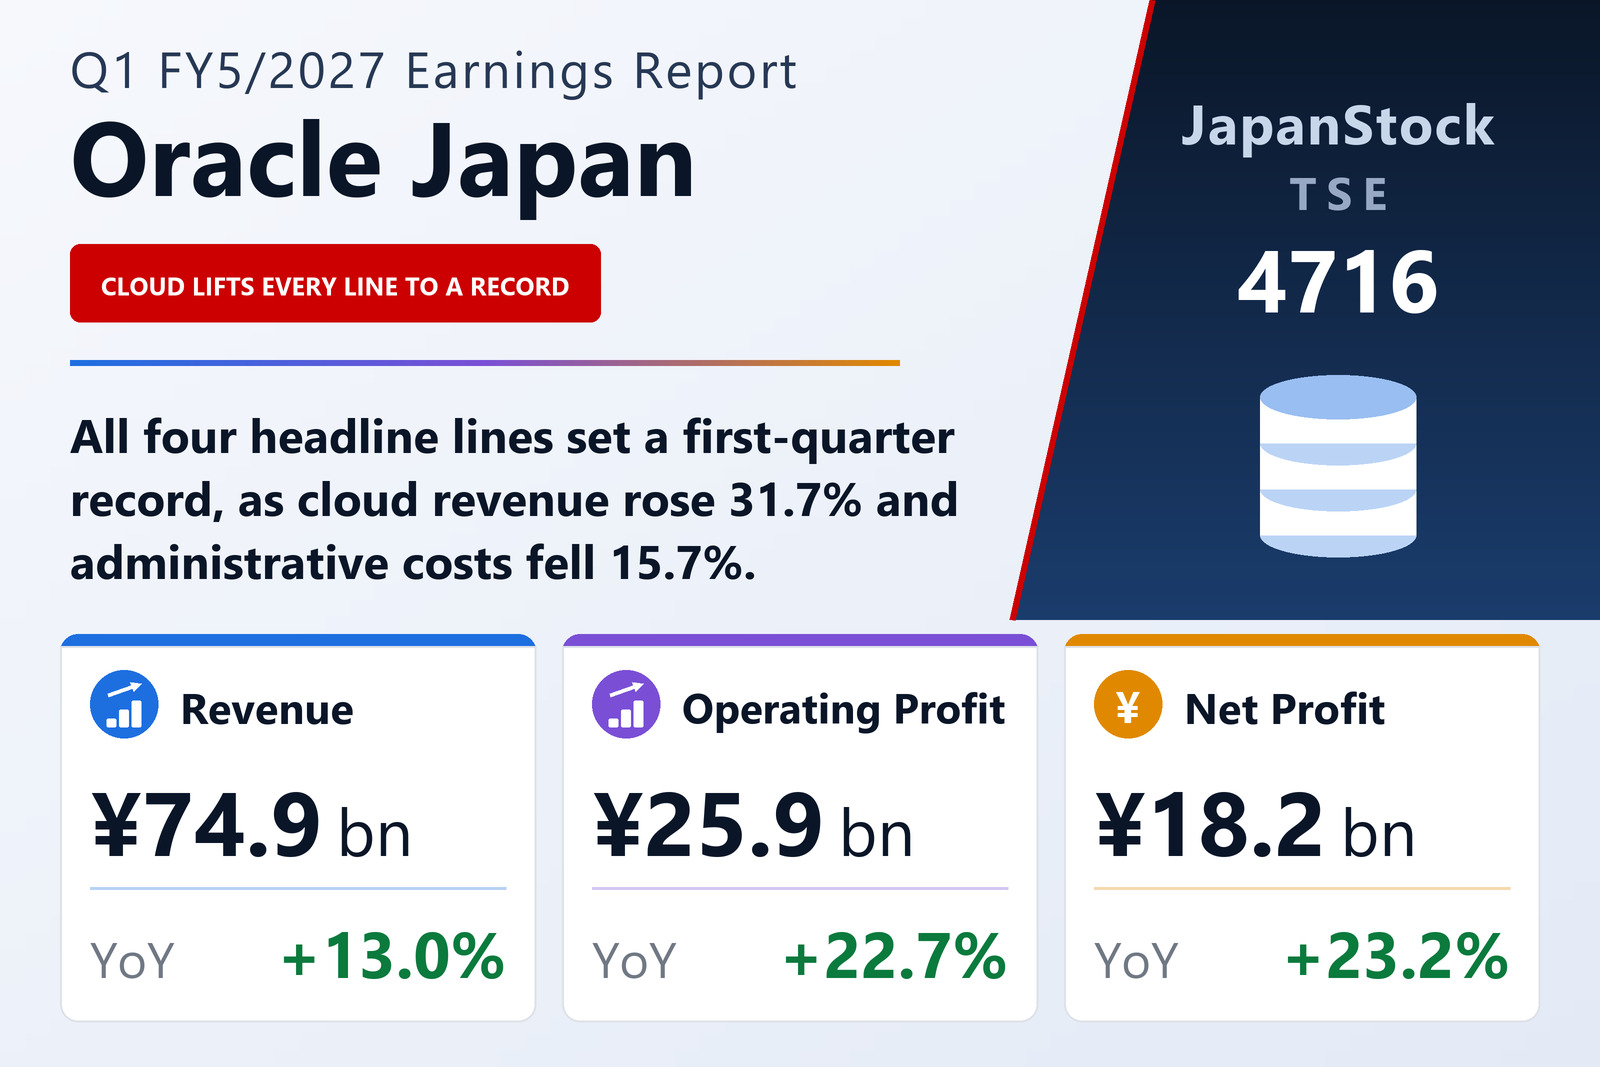
Every headline line set a first-quarter record
Oracle Corporation Japan (TSE: 4716), the software company headquartered in Kita-Aoyama, Minato-ku, Tokyo, published non-consolidated results for the first quarter of its fiscal year ending May 31, 2027 — the three months from June 1 to August 31, 2026 — on September 24, 2026 under Japanese GAAP. Revenue rose 13.0% to ¥74,861 million, operating profit 22.7% to ¥25,918 million, ordinary profit 24.9% to ¥26,689 million and net profit 23.2% to ¥18,245 million, for earnings of ¥142.37 per share against ¥115.65. The company states that all four of those lines were the highest it has recorded for a first quarter. Its shares trade on the Standard market of the Tokyo Stock Exchange.
The arithmetic that produced the 22.7% operating result is not in the gross margin. Cost of sales rose 14.0% to ¥41,794 million, a full percentage point faster than revenue, so gross profit grew only 11.7% to ¥33,066 million and the gross margin narrowed from 44.7% to 44.2%. What lifted the operating line sits below it: selling, general and administrative expenses fell 15.7%, to ¥7,147 million from ¥8,480 million. Of the ¥4,790 million increase in operating profit, ¥3,458 million came from higher gross profit and ¥1,332 million from the smaller expense base, and the operating margin widened from 31.9% to 34.6%. The filing does not explain why administrative costs fell.
Cloud is now a third of revenue, and support is shrinking as a share of it
The filing prints revenue by reporting category, and the mix moved in one direction. Cloud revenue rose 31.7% to ¥25,143 million and now accounts for 33.6% of the total, against 28.8% a year earlier. Software licences grew 19.0% to ¥10,869 million, lifting their share from 13.8% to 14.5%. Software support, still the largest single line at ¥28,871 million, grew only 2.0%, so its share of revenue fell from 42.7% to 38.6%. The software subtotal was ¥39,740 million, up 6.1%, and cloud and software together ¥64,884 million, up 14.8%, or 86.7% of revenue. Hardware was ¥3,811 million, up 10.1%, and services ¥6,165 million, down 1.7% — the only category that shrank in absolute terms, its share slipping from 9.5% to 8.2%.
The causes the filing gives are specific on cloud and thin on services. In cloud, the company says it concentrated on upgrading existing customers to Oracle Fusion Cloud Applications — a lift-and-shift from on-premise — while also pursuing new customers, and that enquiries for Oracle Cloud Infrastructure remained strong among customers who weigh performance, security and cost-effectiveness, with usage of its Tokyo and Osaka data centres rising steadily. It notes that OCI is registered as a cloud service conforming to ISMAP, the government's information-system security assessment programme, and that in October 2022 it was selected as a cloud service for the Digital Agency's Government Cloud. NetSuite, its cloud ERP for mid-sized companies, is described as steady on demand from firms reorganising themselves. On licences the company cites the move away from legacy systems toward standardisation and open systems, plus IT investment aimed at growth rather than cost cutting alone. Support is said to be holding a high contract-renewal rate, with new maintenance contracts arising from on-premise licence sales also at a high level. Hardware is described through the January 2025 launch of the Oracle Exadata X11M platform. For services the company reports that consulting work — migrations from on-premise environments to Oracle Cloud Infrastructure, and projects integrating Cloud Applications — was steady, and offers no explanation for the 1.7% decline.
Three segments, and the profit came from two of them
There are no intersegment sales at all, so the three reporting segments add exactly to group revenue. Cloud and Software earned segment profit of ¥24,627 million, up 16.4%, on revenue of ¥64,884 million, a margin of 38.0% against 37.4%. Services did the opposite of what its revenue line suggests: revenue fell 1.7% but segment profit rose 37.6% to ¥1,857 million, widening the margin from 21.5% to 30.1%. Hardware inverted that again — revenue up 10.1% but segment profit down 52.4%, to ¥59 million from ¥124 million, a margin of 1.5% against 3.6%. The filing gives no reason for either the services margin or the hardware fall. Total segment profit was ¥26,544 million, up 17.3%, and unallocated corporate costs were ¥625 million against ¥1,505 million, ¥880 million lighter — which is where most of the drop in administrative expenses shows up. Segment profit therefore contributed ¥3,910 million of the ¥4,790 million operating increase and the lighter corporate charge the remaining ¥880 million.
Interest income quintupled below the operating line
Non-operating income rose to ¥770 million from ¥241 million, almost entirely on interest: interest income was ¥651 million against ¥128 million, up 408.6%, with foreign-exchange gains of ¥52 million against ¥37 million. Non-operating expenses were nil in both periods. That is the whole of the gap between the 22.7% operating rate and the 24.9% rise in ordinary profit, to ¥26,689 million. The filing does not identify the source of the interest, but the balance sheet carries ¥162,000 million of short-term loans to affiliates at period-end, against ¥212,000 million three months earlier. There was no extraordinary item this year, against ¥3 million of gain on reversal of subscription rights last year, so pre-tax profit equalled ordinary profit at ¥26,689 million, up 24.9%. Income taxes were ¥8,443 million, up 28.6% — an effective rate of 31.6% against 30.7% — matching the 31.6% forecast effective rate the company discloses; for interim reporting it applies that estimated annual rate to pre-tax profit rather than computing tax directly. Net profit was ¥18,245 million, up 23.2%, or ¥142.37 per share, with diluted earnings the same ¥142.37 against ¥115.64.
A ¥110,080 million dividend took a quarter off the balance sheet
Total assets fell 26.4%, from ¥368,416 million at May 31, 2026 to ¥271,189 million, and net assets 44.9% to ¥112,897 million. The equity ratio dropped from 55.6% to 41.6%, a fall of 14.0 points in three months. The cause is a single payment and the company states it plainly: the year-end dividend for its 41st fiscal year, ¥858.00 per share — ¥198 ordinary and ¥660 special — resolved by the board on July 23, 2026 and paid on August 10, 2026, totalling ¥110,080 million. Retained earnings fell from ¥172,899 million to ¥81,065 million as a result, a reduction of ¥91,834 million that is broadly the ¥110,080 million payment less the quarter's ¥18,245 million of profit.
How it was funded is the more useful part. Current assets fell ¥97,347 million to ¥229,161 million, and two lines account for almost all of that: cash and deposits dropped ¥46,254 million to ¥38,714 million, and short-term loans to affiliates fell ¥50,000 million to ¥162,000 million. The company says it recovered that ¥50,000 million early, on July 31, 2026, from a loan to its parent, Oracle Japan Holding, Inc., expressly to help fund the dividend the board had resolved eight days before. Together those two movements are ¥96,254 million of the ¥97,227 million fall in total assets. Fixed assets barely moved, rising ¥121 million to ¥42,028 million, with land unchanged at ¥26,057 million.
Liabilities fell 3.3% to ¥158,292 million, and the composition is worth noting for a company that carries no borrowings on its balance sheet at all. Income taxes payable fell ¥7,286 million to ¥8,811 million, accrued expenses ¥3,896 million to ¥4,797 million and the bonus provision ¥1,110 million to ¥1,005 million, against increases in contract liabilities of ¥2,085 million and trade payables of ¥1,125 million. Contract liabilities of ¥114,253 million — amounts billed to customers before the related revenue is recognised — are 72.2% of total liabilities and now exceed net assets of ¥112,897 million.
Guidance is a range, and the dividend is undetermined
The company discloses full-year FY5/2027 guidance as a range rather than as absolute amounts, and did not revise it: revenue growth of 6.0% to 10.0% and earnings of ¥525.00 to ¥540.00 per share, unchanged from the forecast published on June 25, 2026, with an assumed effective tax rate of 31.6%. No yen figure is given for revenue or for any profit line, so the table below carries no guidance rows. Measured against FY5/2026 revenue of ¥285,073 million, which the filing's own reporting-category table prints, that range implies revenue of roughly ¥302,200 million to ¥313,600 million. The quarter's ¥74,861 million is between 23.9% and 24.8% of that, and its ¥142.37 of earnings per share between 26.4% and 27.1% of the guided range — a first quarter running just short of an even quarterly split on revenue and a little ahead of one on earnings.
On the dividend the filing is explicit: the FY5/2027 dividend is undetermined, no forecast is given for any quarter or for the year, and no payment start date is stated, so the table below carries no dividend row either. The company records that there has been no revision to a previously announced dividend forecast. For reference, FY5/2026 paid ¥858.00 for the year, all of it at the year-end, with nothing at the second quarter. Elsewhere in the notes: issued shares rose by 500 to 128,313,071 and treasury stock was unchanged at 155,629, both figures including shares held under the company's director-remuneration BIP trust and share-grant ESOP trust, while the weighted average was 128,157,420 shares against 128,019,971. Depreciation, including amortisation of intangible assets, was ¥327 million against ¥340 million. No quarterly cash-flow statement was prepared, and the attached quarterly financial statements have not been reviewed by a certified public accountant or an audit firm.
| Metric | Q1 FY5/2027 | Q1 FY5/2026 | Change |
|---|---|---|---|
| Revenue (¥ million) | 74,861 | 66,275 | +13.0% |
| Cost of sales (¥ million) | 41,794 | 36,666 | +14.0% |
| Gross profit (¥ million) | 33,066 | 29,608 | +11.7% |
| Gross margin | 44.2% | 44.7% | −0.5 pt |
| SG&A expenses (¥ million) | 7,147 | 8,480 | −15.7% |
| Operating profit (¥ million) | 25,918 | 21,128 | +22.7% |
| Operating margin | 34.6% | 31.9% | +2.7 pt |
| Interest income (¥ million) | 651 | 128 | +408.6% |
| Ordinary profit (¥ million) | 26,689 | 21,369 | +24.9% |
| Pre-tax profit (¥ million) | 26,689 | 21,372 | +24.9% |
| Net profit (¥ million) | 18,245 | 14,805 | +23.2% |
| EPS (¥) | 142.37 | 115.65 | +23.1% |
| Cloud & Software — revenue (¥ million) | 64,884 | 56,539 | +14.8% |
| Cloud & Software — segment profit (¥ million) | 24,627 | 21,159 | +16.4% |
| Hardware — revenue (¥ million) | 3,811 | 3,463 | +10.1% |
| Hardware — segment profit (¥ million) | 59 | 124 | −52.4% |
| Services — revenue (¥ million) | 6,165 | 6,272 | −1.7% |
| Services — segment profit (¥ million) | 1,857 | 1,350 | +37.6% |
| Total assets (¥ million) | 271,189 | 368,416 | −26.4% |
| Net assets (¥ million) | 112,897 | 204,728 | −44.9% |
| Equity ratio | 41.6% | 55.6% | −14.0 pt |
| Cash and deposits (¥ million) | 38,714 | 84,968 | −54.4% |
| Short-term loans to affiliates (¥ million) | 162,000 | 212,000 | −23.6% |
| Contract liabilities (¥ million) | 114,253 | 112,168 | +1.9% |
JapanStockPulse provides informational content only and does not constitute investment advice. Figures are taken from the company's published earnings short report and may be subject to subsequent revision.