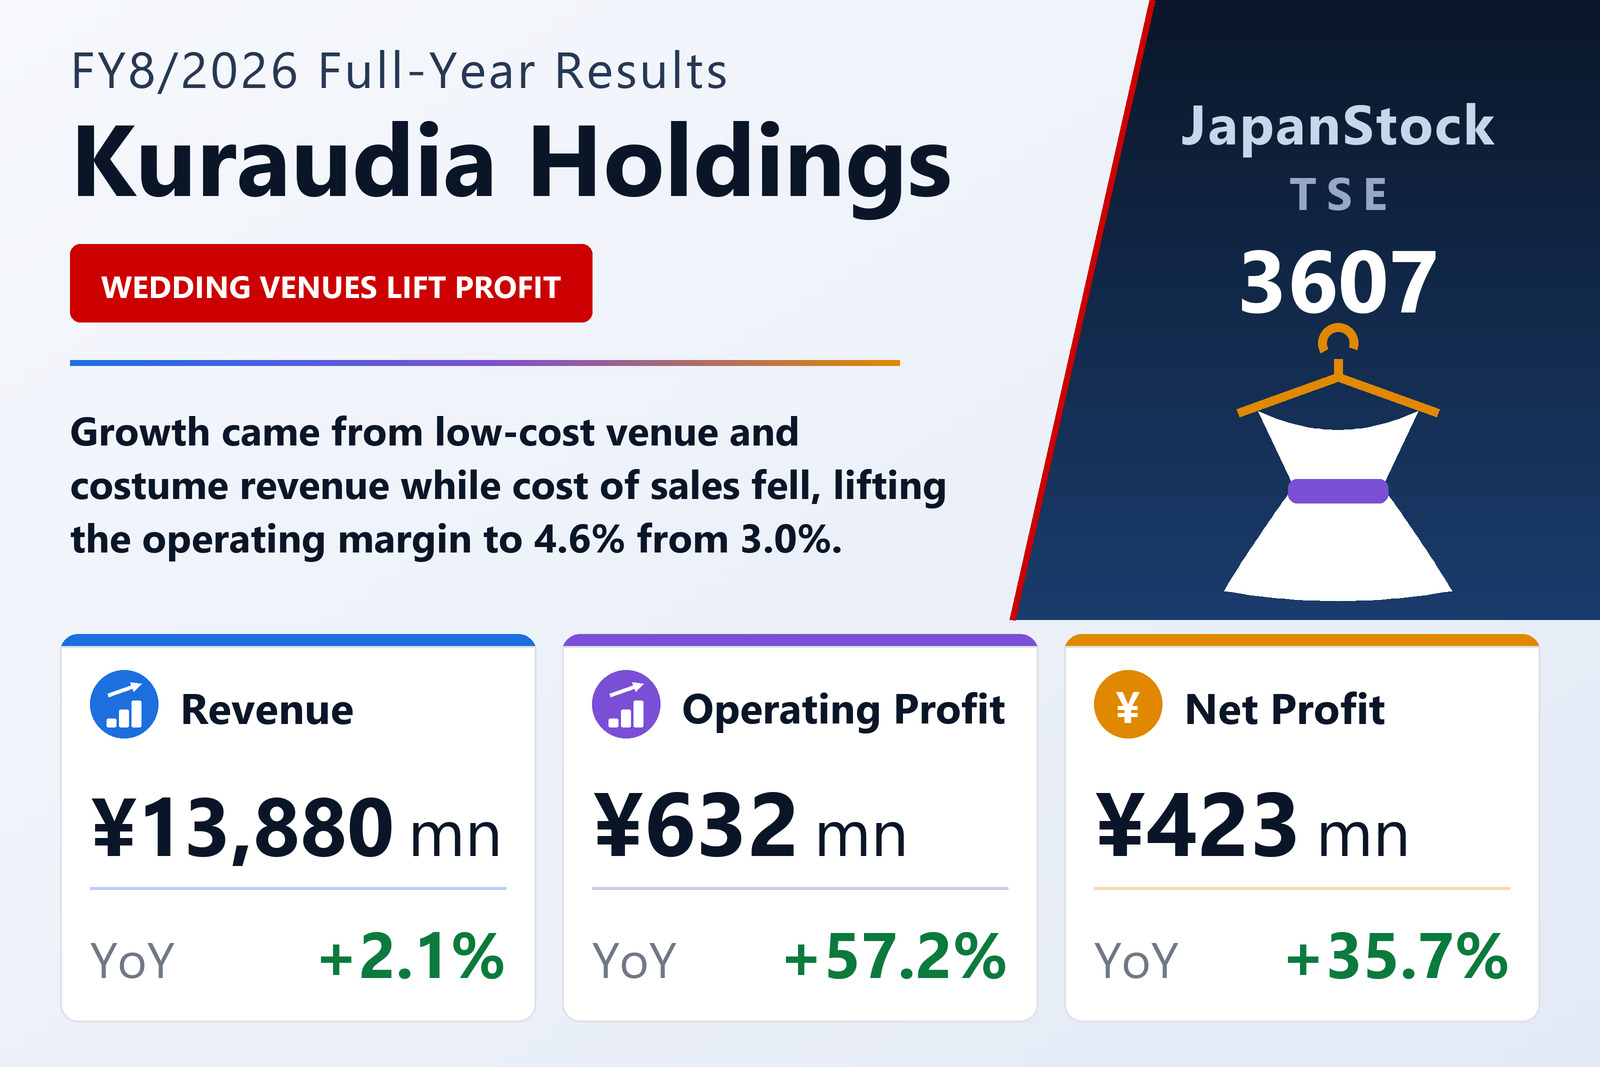
A 2.1% sales rise that turned into a 57.2% profit rise
Kuraudia Holdings Co., Ltd. (TSE: 3607), a wedding-dress maker that also runs wedding venues, photo studios and resort-wedding services, published consolidated full-year results for the fiscal year from September 1, 2025 to August 31, 2026 on September 29, 2026 under Japanese GAAP. Revenue rose 2.1% to ¥13,880 million, operating profit rose 57.2% to ¥632 million, ordinary profit rose 60.4% to ¥668 million and net profit attributable to owners of the parent rose 35.7% to ¥423 million, or ¥46.84 per share against ¥34.72.
The arithmetic is in the cost of sales. Revenue grew by ¥289 million, yet cost of sales fell 2.2% to ¥2,945 million, so gross profit rose ¥356.8 million, or 3.4%, to ¥10,935 million. The company explains that the growth came from costume-handling and venue-operation revenue, which carry a low cost ratio. Selling, general and administrative expenses rose only 1.2% to ¥10,302 million, adding ¥126.6 million, and the ¥230.1 million gap between the two increments is the whole of the operating-profit gain. The operating margin widened from 3.0% to 4.6%.
Venues carried the year; resort weddings slipped
Kuraudia reports a single bridal segment and discloses revenue by division. The Consumer division grew 2.1% to ¥10,809 million, led by venue operations, up 5.2% to ¥3,611 million, which the company attributes to its French restaurant Sombreuil TOKYO in Chiyoda-ku and to the Tokyo Daijingu Daijingu Kaikan, which opened in April 2026 for Shinto shrine weddings in traditional Japanese dress. Costume handling grew 2.4% to ¥3,432 million and photo, video and beauty 1.0% to ¥2,340 million, while resort weddings fell 3.7% to ¥1,424 million. The Wholesale division grew 2.1% to ¥3,070 million, as rental income rose 5.1% and product sales fell 1.8%. Venue operations alone supplied ¥177 million of the group's ¥289 million revenue increase.
A factory closure and a tax credit below the line
Ordinary profit benefited from a ¥38 million foreign-exchange gain, a ¥21 million reversal of bad-debt allowances and ¥19 million of subsidy income, which more than covered interest expense that rose to ¥75 million from ¥60 million. Extraordinary losses of ¥199 million, including a ¥163 million business-liquidation loss on closing the Qingdao factory in August 2026 and ¥35 million of impairment, held pre-tax profit to ¥472 million, up 13.2%. Taxes then fell to ¥49 million from ¥105 million because a ¥114 million deferred-tax credit offset ¥163 million of current tax, which is how net profit grew faster than pre-tax profit. The company now treats its Vietnam factory as its main production site for wedding dresses.
Lower borrowings, higher equity ratio
Total assets rose 2.8% to ¥12,972 million and net assets 10.2% to ¥4,374 million, lifting the equity ratio to 33.7% from 31.4%. Short-term borrowings fell to ¥300 million from ¥1,050 million, and total borrowings, including long-term loans, came down to about ¥5,144 million from ¥5,734 million. Operating cash flow rose to ¥999 million from ¥859 million; after ¥391 million of investment and ¥687 million of net financing outflows, cash and cash equivalents ended the year at ¥1,800 million.
Guidance and dividend
For the year to August 31, 2027, Kuraudia forecasts revenue of ¥14,700 million (+5.9%), operating profit of ¥750 million (+18.6%), ordinary profit of ¥750 million (+12.2%) and net profit of ¥550 million (+29.8%). The plan rests on venues: venue-operation revenue is budgeted at ¥4,580 million, up 26.8%, helped by the rebranding of its Osaka venue as Sombreuil OSAKA WEDDING from September 2026, while costume handling is budgeted to fall 7.9% to ¥3,160 million and photo, video and beauty 4.3% to ¥2,240 million, both because partner businesses are handling fewer weddings. The FY8/2026 dividend was raised to ¥12.00, comprising ¥5.00 at the interim, a ¥5.00 ordinary year-end dividend and a ¥2.00 dividend marking the company's 50th anniversary; the FY8/2027 forecast is ¥10.00, the ordinary level.
| Metric | FY8/2026 | FY8/2025 | Change |
|---|---|---|---|
| Revenue (¥ million) | 13,880 | 13,591 | +2.1% |
| Gross profit (¥ million) | 10,935 | 10,578 | +3.4% |
| SG&A expenses (¥ million) | 10,302 | 10,176 | +1.2% |
| Operating profit (¥ million) | 632 | 402 | +57.2% |
| Operating margin | 4.6% | 3.0% | +1.6 pt |
| Ordinary profit (¥ million) | 668 | 416 | +60.4% |
| Pre-tax profit (¥ million) | 472 | 417 | +13.2% |
| Net profit attrib. to owners of parent (¥ million) | 423 | 312 | +35.7% |
| EPS (¥) | 46.84 | 34.72 | +34.9% |
| Comprehensive income (¥ million) | 480 | 229 | +109.6% |
| Wholesale division — revenue (¥ million) | 3,070 | 3,006 | +2.1% |
| Consumer division — revenue (¥ million) | 10,809 | 10,584 | +2.1% |
| Costume handling (consumer) — revenue (¥ million) | 3,432 | 3,351 | +2.4% |
| Resort weddings (consumer) — revenue (¥ million) | 1,424 | 1,479 | −3.7% |
| Venue operations (consumer) — revenue (¥ million) | 3,611 | 3,434 | +5.2% |
| Photo, video & beauty (consumer) — revenue (¥ million) | 2,340 | 2,318 | +1.0% |
| Total assets (¥ million) | 12,972 | 12,625 | +2.8% |
| Net assets (¥ million) | 4,374 | 3,967 | +10.2% |
| Equity ratio | 33.7% | 31.4% | +2.3 pt |
| FY8/2027 guidance — revenue (¥ million) | 14,700 | — | +5.9% |
| FY8/2027 guidance — operating profit (¥ million) | 750 | — | +18.6% |
| FY8/2027 guidance — ordinary profit (¥ million) | 750 | — | +12.2% |
| FY8/2027 guidance — net profit (¥ million) | 550 | — | +29.8% |
| Annual dividend per share (¥) | 10.00 | 12.00 | −16.7% |
JapanStockPulse provides informational content only and does not constitute investment advice. Figures are taken from the company's published earnings short report and may be subject to subsequent revision.