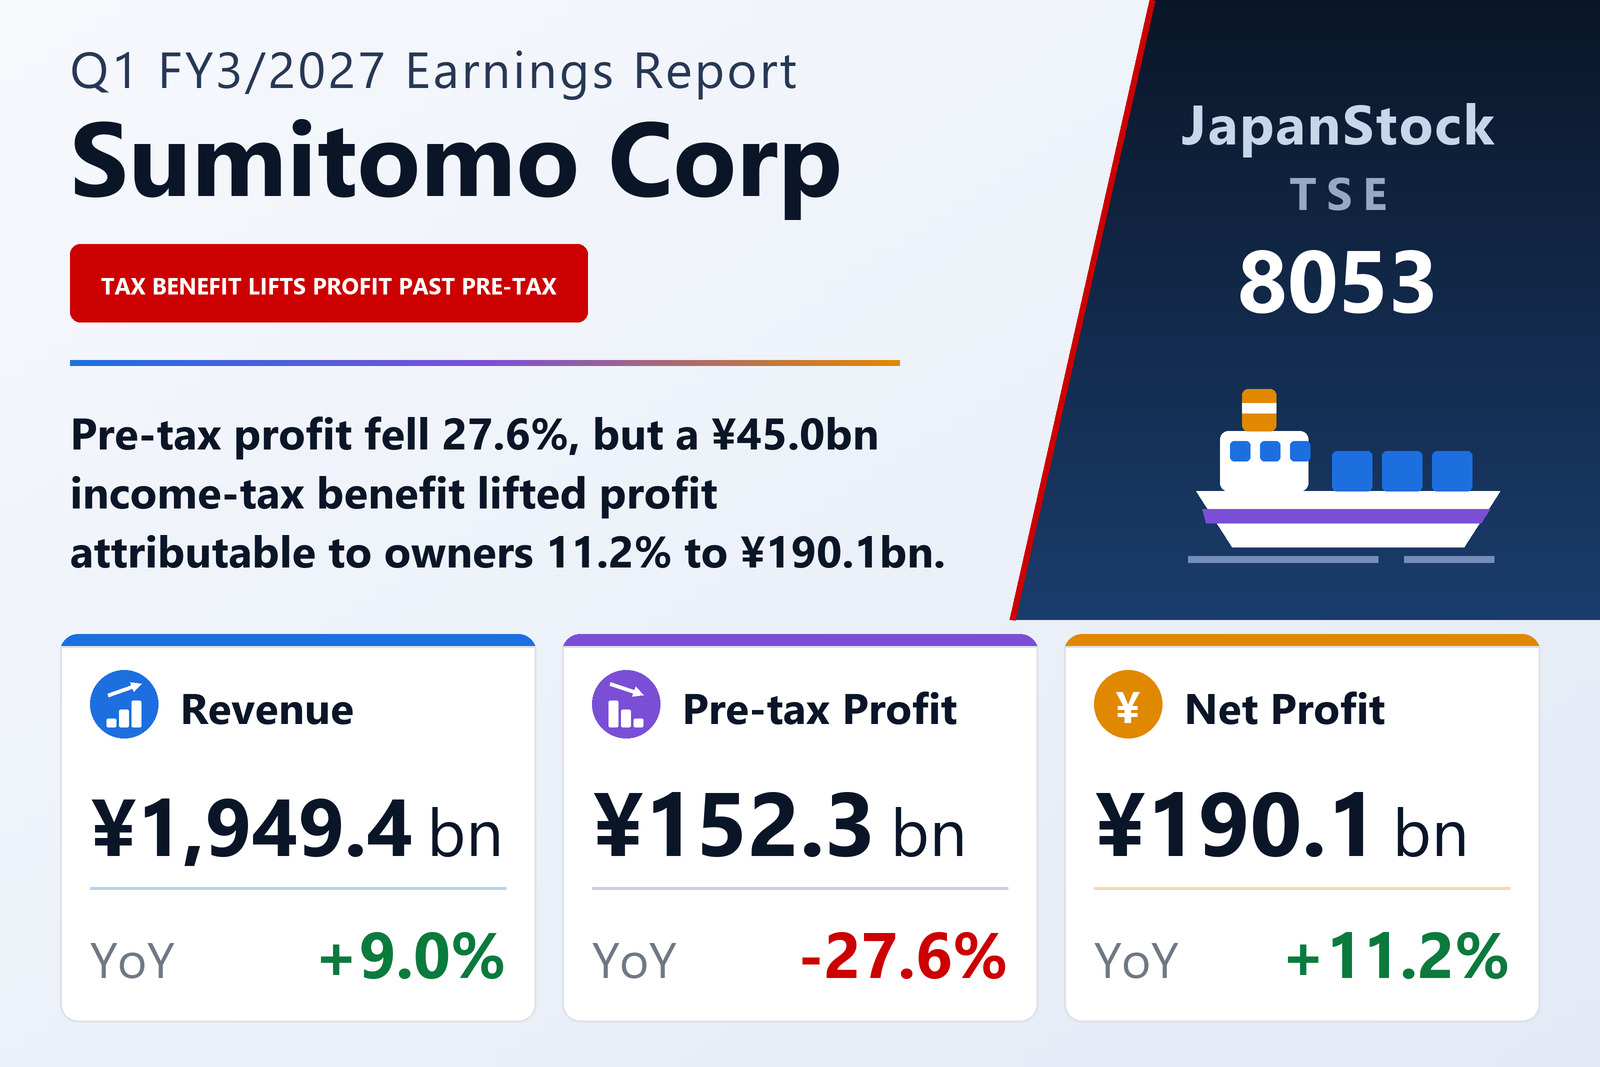
Pre-tax profit fell 27.6%; the bottom line rose 11.2%
Sumitomo Corporation (TSE: 8053), the trading and investment group whose ten reporting segments run from steel, automobiles and urban development to mineral resources and energy, published consolidated results for the first quarter of FY3/2027 — the three months from April 1 to June 30, 2026 — on July 31, 2026 under IFRS, with figures rounded to the nearest million yen. Revenue rose 9.0% to ¥1,949,362 million. Pre-tax profit fell 27.6% to ¥152,261 million from ¥210,279 million, yet profit for the quarter rose 7.0% to ¥197,285 million and profit attributable to owners of the parent rose 11.2% to ¥190,075 million from ¥170,870 million. Total comprehensive income was ¥268,074 million, up 154.9% from ¥105,164 million, helped by exchange differences on translating foreign operations of ¥39,463 million against a negative ¥72,076 million a year earlier.
Per-share figures need one adjustment before they are compared. Sumitomo Corporation split each ordinary share into four with effect from July 1, 2026, and the filing calculates earnings per share for both quarters as if the split had taken place at the start of the previous fiscal year. On that restated basis, basic earnings per share were ¥39.95 against ¥35.29, up 13.2% — faster than attributable profit, because the average number of shares outstanding fell to 4,753,255,893 from 4,838,558,272. Share counts and the full-year earnings-per-share forecast are stated on the same post-split basis.
An income-tax benefit carried profit above the pre-tax line
Profit for the quarter was higher than pre-tax profit, and the income-tax line accounts for the whole difference: it was a benefit of ¥45,024 million, against an expense of ¥25,856 million a year earlier, so ¥152,261 million of pre-tax profit became ¥197,285 million after tax. The filing attributes that swing — ¥70.9 billion in its own summary table — to the tax effect of selling the Madagascar nickel business, and under corporate and eliminations it also cites a tax effect from reorganising an intermediate holding company. It does not say how the ¥45,024 million divides between the two. Profit attributable to non-controlling interests fell to ¥7,210 million from ¥13,553 million, which is why owners' profit grew 11.2% while total quarterly profit grew 7.0%.
Why pre-tax profit fell ¥58,018 million
The trading line itself improved. Gross profit rose 8.8% to ¥390,006 million, about 20.0% of revenue in both quarters, which the filing credits to better utilisation and operations in the construction-equipment rental business, a rebound from last year's weak melon business in Lifestyle, and strong precious-metals trading in Mineral Resources. Selling, general and administrative expenses rose faster, 10.2% to ¥286,612 million, on higher personnel costs, so gross profit less SG&A improved by only ¥5,020 million. Other gains and losses swung to a loss of ¥11,407 million from a gain of ¥1,379 million, for which the filing gives no reason, and gains on the sale of fixed assets eased to ¥12,131 million from ¥13,472 million.
The decline came below those lines. Financial income and costs moved from a net ¥41 million to a net cost of ¥28,799 million: interest expense rose to ¥29,577 million from ¥22,290 million against interest income of ¥18,208 million, dividends received more than doubled to ¥8,912 million, but gains on securities swung to a loss of ¥26,342 million from a gain of ¥2,248 million. The filing names three items there — a loss on the sale of the Madagascar nickel business and, pulling the other way, realised foreign-exchange gains from the holding-company reorganisation and a gain on selling a Belgian offshore wind power project. Share of profit of equity-method investees fell 20.7% to ¥76,924 million from ¥97,023 million, a year-earlier figure that included gains related to selling a U.S. tyre-sales company. The Madagascar sale therefore weighed on pre-tax profit through the securities line and supported after-tax profit through the tax line.
The segments fell 2.5%; the corporate line did the growing
Profit attributable to owners, broken down by segment, sharpens the picture. The ten operating segments together earned ¥162,030 million, down 2.5% from ¥166,150 million, while the corporate-and-eliminations line — which the filing says carries the holding-company reorganisation's tax effect and realised currency gains — rose to ¥28,045 million from ¥4,720 million. That ¥23,325 million rise at the corporate line is larger than the group's entire ¥19,205 million increase.
Seven segments grew. Energy Transformation was the largest, at ¥32,584 million, up 35.8%, on higher profit from the asset replacement of the Belgian offshore wind project. Mineral Resources more than doubled, to ¥25,435 million from ¥10,647 million, on higher copper prices, wider aluminium margins and strong precious-metals trading. Chemicals, Electronics & Agriculture rose 68.5% to ¥12,147 million on higher petrochemical trading earnings and a larger semiconductor-materials business; Digital & AI rose 48.5% to ¥7,414 million, citing a higher ownership stake in SCSK and firm domestic IT investment demand; and Communication Services rose 86.1% to ¥6,392 million as slower local-currency depreciation shrank foreign-exchange valuation losses at the Ethiopian telecom business. Steel rose 7.0% to ¥20,094 million, where lower shipments of energy tubular goods to the Middle East were offset by asset-replacement gains, a firm monopile manufacturing business and a restructuring gain, and Lifestyle recovered to ¥2,198 million from ¥292 million on the rebound in its European and American fresh-produce business.
Three segments fell. Automotive dropped 70.6% to ¥11,676 million from ¥39,687 million: domestic auto leasing was firm, but the prior-year quarter included gains related to selling the U.S. tyre-sales company. Integrated Urban Development fell 22.9% to ¥27,923 million because the prior year included deliveries of large projects, and Transportation & Construction Equipment fell 22.7% to ¥16,167 million, as Sumisho Air Lease began contributing to the leasing business but restructuring-related costs were booked. Prior-year segment figures are restated for an April 1, 2026 reorganisation, under which the DX & IT Group became an operating group renamed Digital & AI and took over the Digital SBU from the Media & Digital Group, itself renamed Communication Services.
The Sumisho Air Lease purchase pushed free cash flow negative
Total assets fell 1.4% to ¥13,445,775 million from ¥13,638,338 million at March 31, 2026, as operating assets decreased, partly offset by the weaker yen. Equity attributable to owners of the parent rose 2.3% to ¥4,735,296 million on the quarter's profit and the weaker yen, net of dividends and share buybacks, and its ratio to total assets rose to 35.2% from 33.9%. Net interest-bearing debt, however, rose to about ¥3.71 trillion from ¥3.15 trillion, which the filing attributes to the acquisition of Sumisho Air Lease, lifting the net debt-to-equity ratio to 0.78 from 0.68.
Operating cash flow was ¥54,726 million against ¥120,078 million. Investing activities absorbed ¥423,088 million, against ¥12,408 million a year earlier, including ¥372,849 million of payments for other investments; the filing names the Sumisho Air Lease purchase and domestic real-estate acquisitions, partly offset by sales of the Belgian offshore wind project, real estate in Japan and abroad, and cross-shareholdings. Free cash flow was therefore negative by about ¥368.4 billion. Financing brought in ¥58,110 million, as ¥203,838 million of long-term borrowing covered ¥95,413 million of dividends and ¥57,310 million of share buybacks, and cash and cash equivalents fell to ¥697,741 million from ¥1,005,442 million. The company also cancelled treasury shares carried at ¥74,920 million, reducing issued shares on the post-split basis to 4,780,460,736 from 4,845,706,668.
Guidance of ¥630,000 million held; a ¥40 dividend after the split
Sumitomo Corporation left its FY3/2027 forecast unchanged from the one published on May 1, 2026: profit attributable to owners of the parent of ¥630,000 million, up 4.9%, and basic earnings per share of ¥132.54 on the post-split share count. The first quarter delivered 30.2% of that figure, with the ¥45,024 million tax benefit included. The filing publishes no full-year revenue or pre-tax guidance. The dividend forecast is also unchanged, at ¥20.00 at the interim and ¥20.00 at the year-end, ¥40.00 for the year on the post-split basis; the company states that without the split this would be ¥160.00, against the ¥150.00 paid for FY3/2026 (¥70.00 interim and ¥80.00 year-end), an increase of 6.7%.
| Metric | Q1 FY3/2027 | Q1 FY3/2026 | Change |
|---|---|---|---|
| Revenue (¥ million) | 1,949,362 | 1,787,921 | +9.0% |
| Gross profit (¥ million) | 390,006 | 358,463 | +8.8% |
| SG&A expenses (¥ million) | 286,612 | 260,089 | +10.2% |
| Gain (loss) on securities (¥ million) | −26,342 | 2,248 | profit to loss |
| Share of profit of equity-method investees (¥ million) | 76,924 | 97,023 | −20.7% |
| Pre-tax profit (¥ million) | 152,261 | 210,279 | −27.6% |
| Income taxes, benefit (+) / expense (−) (¥ million) | +45,024 | −25,856 | n.m. |
| Net profit (¥ million) | 197,285 | 184,423 | +7.0% |
| Net profit attrib. to owners of parent (¥ million) | 190,075 | 170,870 | +11.2% |
| Comprehensive income (¥ million) | 268,074 | 105,164 | +154.9% |
| EPS (¥) | 39.95 | 35.29 | +13.2% |
| Steel — segment profit (¥ million) | 20,094 | 18,783 | +7.0% |
| Automotive — segment profit (¥ million) | 11,676 | 39,687 | −70.6% |
| Transportation & Construction Equipment — segment profit (¥ million) | 16,167 | 20,910 | −22.7% |
| Integrated Urban Development — segment profit (¥ million) | 27,923 | 36,202 | −22.9% |
| Communication Services — segment profit (¥ million) | 6,392 | 3,434 | +86.1% |
| Digital & AI — segment profit (¥ million) | 7,414 | 4,991 | +48.5% |
| Lifestyle — segment profit (¥ million) | 2,198 | 292 | +652.7% |
| Mineral Resources — segment profit (¥ million) | 25,435 | 10,647 | +138.9% |
| Chemicals, Electronics & Agriculture — segment profit (¥ million) | 12,147 | 7,209 | +68.5% |
| Energy Transformation — segment profit (¥ million) | 32,584 | 23,995 | +35.8% |
| Corporate & eliminations — profit attrib. to owners (¥ million) | 28,045 | 4,720 | +494.2% |
| Total assets (¥ million) | 13,445,775 | 13,638,338 | −1.4% |
| Net assets (¥ million) | 4,847,434 | 4,735,154 | +2.4% |
| Equity attrib. to owners of parent (¥ million) | 4,735,296 | 4,628,555 | +2.3% |
| Equity ratio | 35.2% | 33.9% | +1.3 pt |
| Operating cash flow (¥ million) | 54,726 | 120,078 | −54.4% |
| Investing cash flow (¥ million) | −423,088 | −12,408 | n.m. |
| Financing cash flow (¥ million) | 58,110 | −60,296 | n.m. |
| FY3/2027 guidance — net profit attrib. to owners of parent (¥ million) | 630,000 | — | +4.9% |
| FY3/2027 guidance — EPS (¥) | 132.54 | — | — |
| FY3/2027 forecast annual dividend per share, post-split (¥) | 40.00 | — | — |
| Annual dividend per share, pre-split basis (¥) | 160.00 | 150.00 | +6.7% |
JapanStockPulse provides informational content only and does not constitute investment advice. Figures are taken from the company's published earnings short report and may be subject to subsequent revision.