AI demand fills the order book
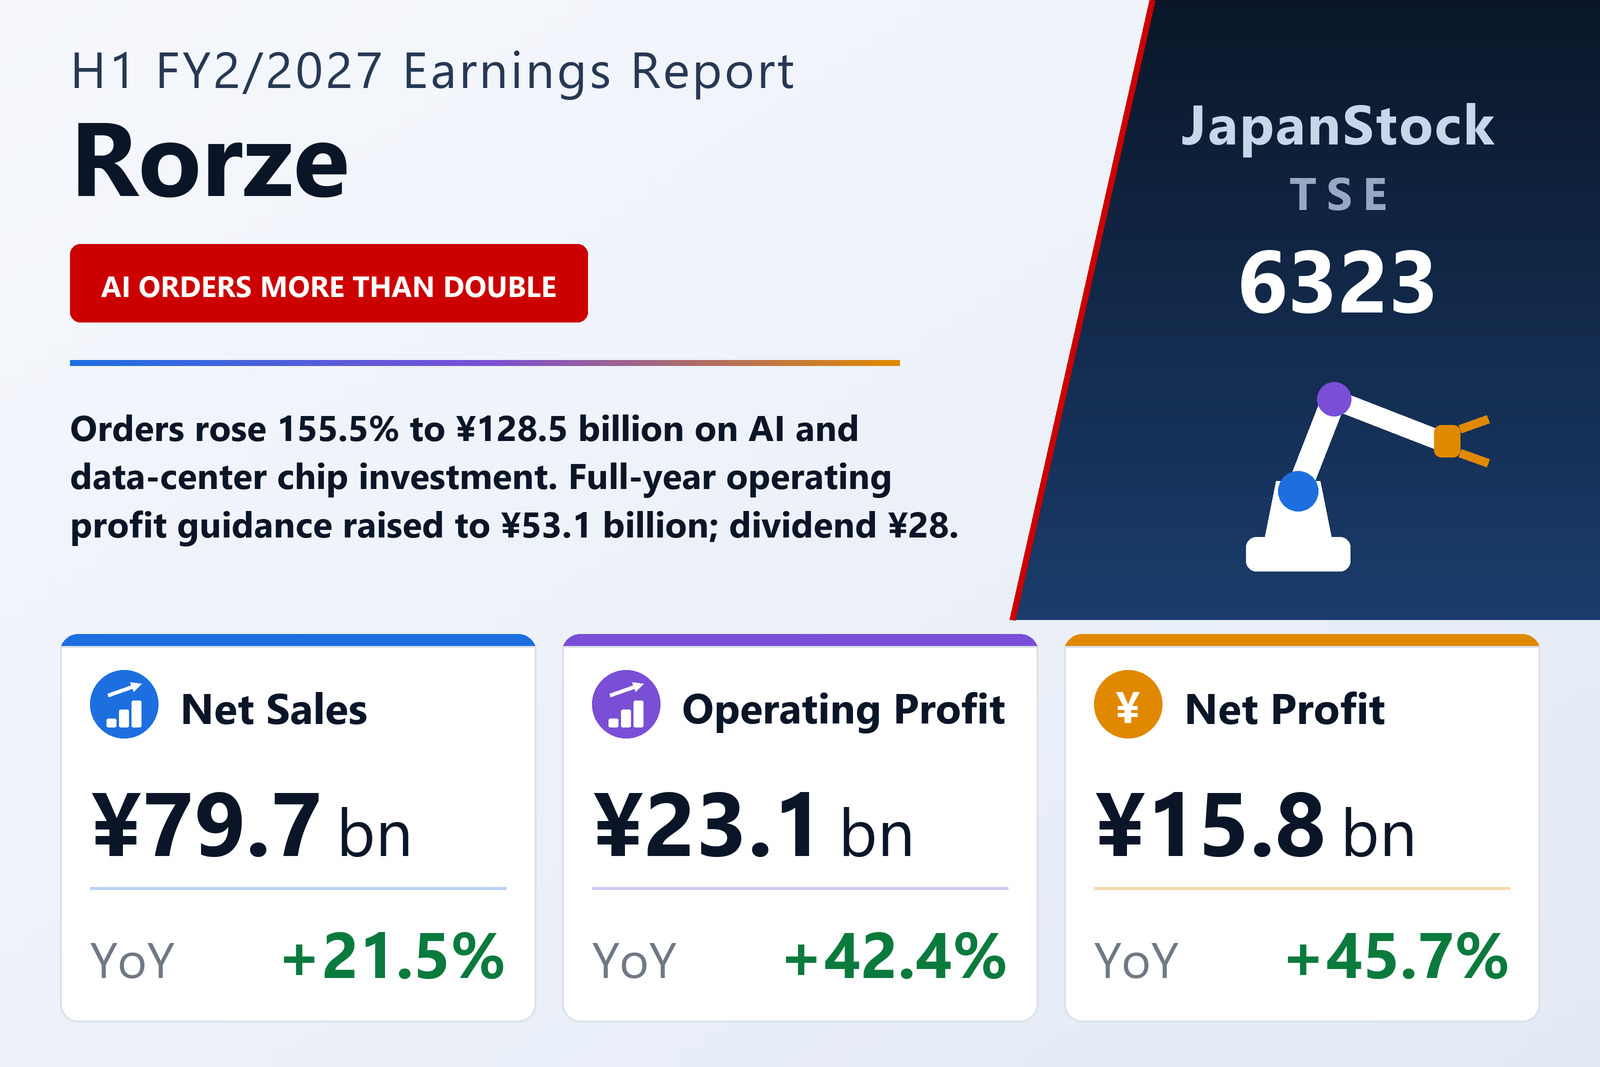
Rorze Corporation (TSE: 6323), the Fukuyama, Hiroshima-based maker of wafer-transfer robots and equipment-front-end modules for semiconductor and flat-panel-display production lines, reported consolidated first-half results for FY2/2027, the six months from March 1 to August 31, 2026, on October 8, 2026 under Japanese GAAP. Net sales rose 21.5% to ¥79,733 million, operating profit 42.4% to ¥23,096 million and ordinary profit, helped by foreign exchange, 68.4% to ¥24,538 million. Profit attributable to owners of the parent rose 45.7% to ¥15,839 million, or ¥91.33 per share against ¥62.13.
The company said the global semiconductor industry was strong and the rapid growth of the data-center market drove active investment in chipmaking equipment, with demand linked to generative AI expected to keep expanding. Gross profit rose 30.8% to ¥34,371 million, lifting the gross margin to 43.1% from 40.0%. Orders received climbed 155.5% to ¥128,546 million, led by semiconductor equipment at ¥120,540 million, and the order backlog stood at ¥111,485 million at the end of August.
Segments and markets
The semiconductor and FPD equipment segment grew sales 21.6% to ¥79,357 million and segment profit 43.0% to ¥23,969 million. By customer location, China accounted for ¥20,899 million of that segment's sales, the United States ¥23,888 million, Taiwan ¥19,406 million, South Korea ¥3,971 million and Japan ¥4,467 million. The small life science segment grew sales 2.8% to ¥376 million but its segment loss widened to ¥147 million from ¥119 million.
Balance sheet
Total assets rose 10.5% to ¥218,038 million from February 28, on cash up ¥12,036 million, inventories up ¥5,870 million and receivables up ¥4,398 million. Borrowings increased by ¥7,772 million while a provision for litigation losses fell by ¥7,429 million. Net assets rose to ¥155,987 million and the equity ratio to 67.2% from 66.0%.
Guidance and dividend raised
Rorze raised the FY2/2027 forecast it had issued on April 9, 2026, and now expects net sales of ¥180,007 million (+39.8%), operating profit of ¥53,078 million (+70.4%), ordinary profit of ¥54,889 million (+68.3%) and net profit of ¥37,779 million (+98.3%), or ¥217.84 per share, up from ¥159,021 million, ¥38,112 million, ¥38,241 million and ¥27,809 million. The new targets imply a much stronger second half, with operating profit of about ¥30 billion against ¥23.1 billion in the first. The company also raised its year-end dividend forecast to ¥28.00 from ¥20.00, against ¥17.00 for FY2/2026.
| Metric | H1 FY2/2027 | H1 FY2/2026 | Change |
|---|---|---|---|
| Net sales (¥ million) | 79,733 | 65,602 | +21.5% |
| Gross profit (¥ million) | 34,371 | 26,269 | +30.8% |
| Operating profit (¥ million) | 23,096 | 16,214 | +42.4% |
| Ordinary profit (¥ million) | 24,538 | 14,572 | +68.4% |
| Net profit attrib. to owners of parent (¥ million) | 15,839 | 10,872 | +45.7% |
| EPS (¥) | 91.33 | 62.13 | +47.0% |
| Orders received (¥ million) | 128,546 | — | +155.5% |
| Order backlog (¥ million) | 111,485 | — | — |
| Semiconductor and FPD equipment — revenue (¥ million) | 79,357 | — | +21.6% |
| Semiconductor and FPD equipment — segment profit (¥ million) | 23,969 | — | +43.0% |
| Life science — revenue (¥ million) | 376 | — | +2.8% |
| Life science — segment profit (¥ million) | -147 | -119 | loss widened |
| Total assets (¥ million) | 218,038 | 197,302 | +10.5% |
| Net assets (¥ million) | 155,987 | 139,961 | +11.5% |
| Equity ratio | 67.2% | 66.0% | +1.2 pt |
| FY2/2027 guidance — revenue (¥ million) | 180,007 | — | +39.8% |
| FY2/2027 guidance — operating profit (¥ million) | 53,078 | — | +70.4% |
| FY2/2027 guidance — ordinary profit (¥ million) | 54,889 | — | +68.3% |
| FY2/2027 guidance — net profit (¥ million) | 37,779 | — | +98.3% |
| FY2/2027 guidance — EPS (¥) | 217.84 | — | n.m. |
| Annual dividend per share (¥) | 28.00 | 17.00 | +64.7% |
JapanStockPulse provides informational content only and does not constitute investment advice. Figures are taken from the company's published earnings short report and may be subject to subsequent revision.