Margins widen faster than sales
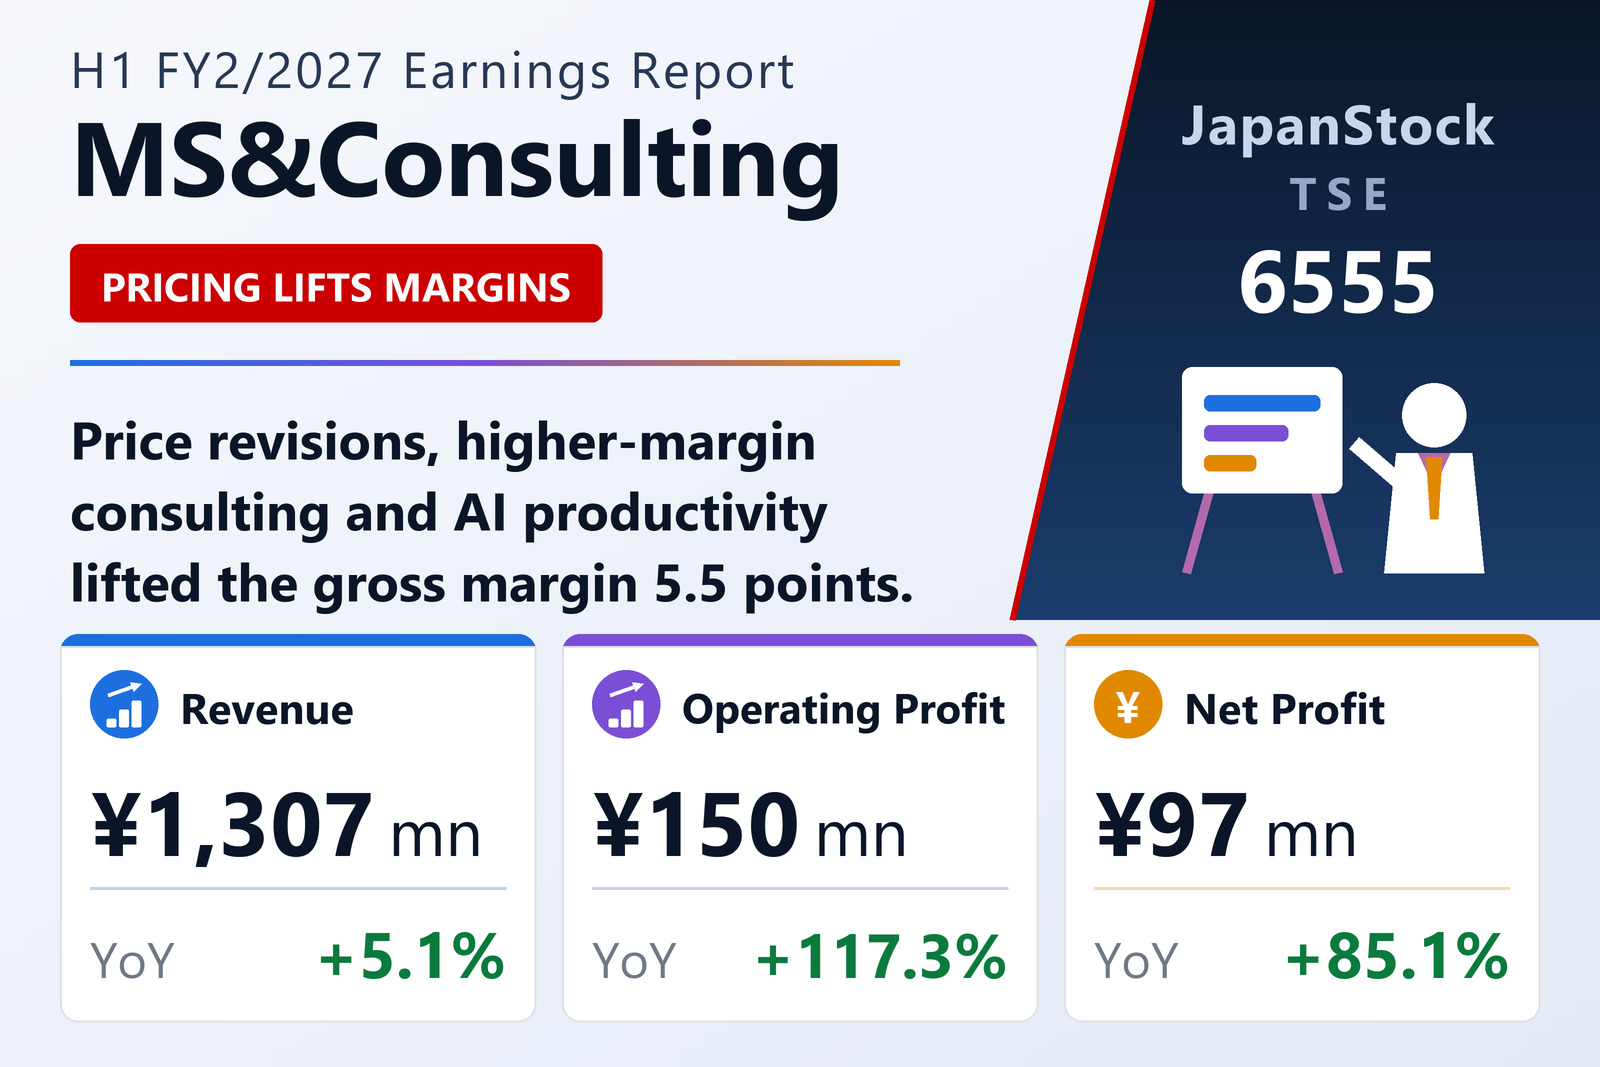
MS&Consulting Co., Ltd. (TSE: 6555) reported consolidated results for the first half of FY2/2027, March 1 to August 31, 2026, on October 15, 2026 under IFRS. Revenue rose 5.1% to ¥1,307 million, 3.8% above its own plan, and gross profit rose 23.7%. Operating profit rose 117.3% to ¥150 million, 87.0% above plan, and pre-tax profit 119.1% to ¥150 million. Profit attributable to owners of the parent rose 85.1% to ¥97 million, or ¥21.46 per share. Revenue in the customer-experience (CX) domain, which includes its core mystery shopping research (MSR), was hit in the first quarter by the end of a large one-off contract from last year, but beat the prior year in the second quarter and was back to roughly last year's level for the half. Consulting revenue rose 26.8%, led by a 74.8% jump in subsidy and grant consulting, and other revenue rose 30.5%; overseas-related MSR surveys rose 33.5%.
Pricing and productivity
The company operates a single MSR segment. Lower production cost per report and price revisions raised the MSR gross margin to 49.9% from 47.2%, and across the business the cost-of-sales ratio fell 5.5 points and the SG&A ratio 1.6 points, lifting the operating margin by 5.9 points. Direct-profit sales, revenue minus monitor rewards and outsourcing costs, rose 9.8%. Orders rose 7.4% and direct-profit orders 13.7%, and first-half revenue plus the second-half order backlog now covers 79.8% of the full-year plan, 6.4 points more than a year earlier. Its CX Grid platform, higher-margin consulting and use of AI are the main levers of its growth strategy.
Balance sheet and outlook
Total assets rose 1.7% to ¥3,768 million and equity attributable to owners of the parent 3.5% to ¥3,060 million, lifting the parent ownership ratio to 81.2% from 79.8%. Operating cash flow was ¥47 million, ¥94 million less than a year earlier, mainly as trade receivables rose. The company left its FY2/2027 forecast unchanged: revenue of ¥2,757 million (+6.7%), operating profit of ¥355 million (+40.7%), pre-tax profit of ¥352 million (+40.2%) and profit attributable to owners of the parent of ¥220 million (+27.2%). It plans no dividend for the year.
| Metric | H1 FY2/2027 | H1 FY2/2026 | Change |
|---|---|---|---|
| Revenue (¥ million) | 1,307 | 1,243 | +5.1% |
| Operating profit (¥ million) | 150 | 69 | +117.3% |
| Pre-tax profit (¥ million) | 150 | 68 | +119.1% |
| Net profit attrib. to owners of parent (¥ million) | 97 | 52 | +85.1% |
| EPS (¥) | 21.46 | 12.48 | +72.0% |
| Total assets (¥ million) | 3,768 | 3,704 | +1.7% |
| Equity attrib. to owners of parent (¥ million) | 3,060 | 2,956 | +3.5% |
| Equity ratio | 81.2% | 79.8% | +1.4 pt |
| FY2/2027 guidance — revenue (¥ million) | 2,757 | — | +6.7% |
| FY2/2027 guidance — operating profit (¥ million) | 355 | — | +40.7% |
| FY2/2027 guidance — pre-tax profit (¥ million) | 352 | — | +40.2% |
| FY2/2027 guidance — net profit (¥ million) | 220 | — | +27.2% |
| Annual dividend per share (¥) | 0.00 | 0.00 | unchanged |
JapanStockPulse provides informational content only and does not constitute investment advice. Figures are taken from the company's published earnings short report and may be subject to subsequent revision.