Bread and pastries hold volume through a price rise
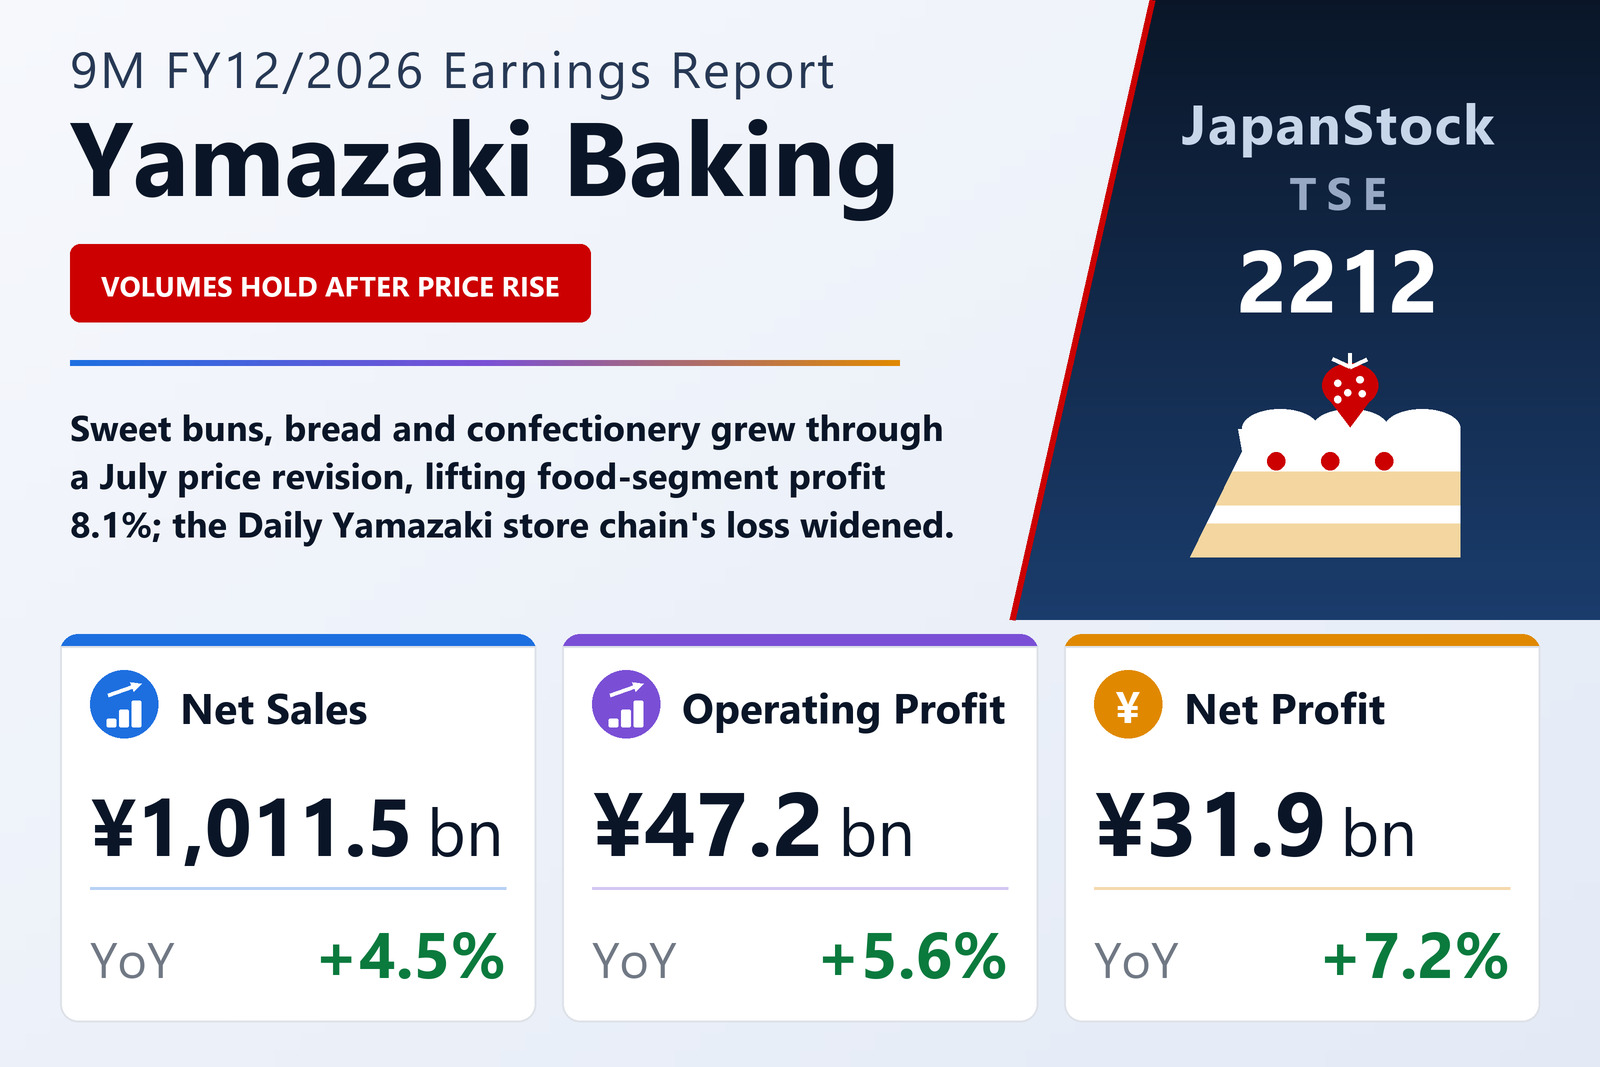
Yamazaki Baking Co., Ltd. (TSE: 2212) reported consolidated results for the first nine months of FY12/2026, January 1 to September 30, 2026, on October 27, 2026 under Japanese GAAP. The company described a tough market of entrenched thrift among consumers, higher prices for fats and packaging and rising labor and logistics costs. It revised prices on some bread, sweet-bun and confectionery products from July 1 shipments and said volumes held. The food segment grew sales 4.7% to ¥939,535 million and segment profit 8.1% to ¥45,834 million. Sweet buns, the largest category, grew 5.8% to ¥380,430 million on its Coppepan, apple pie and chilled pastries; bread rose 4.1% to ¥93,675 million as the reformulated Royal Bread and low-price loaves grew; Japanese confectionery rose 7.9% to ¥63,011 million and Western confectionery 4.2% to ¥121,203 million. Snacks, rice crackers and other goods grew 6.3% to ¥149,553 million on Yamazaki Biscuits' Aerial and Tohato's Poteco.
Prepared foods slip, convenience stores lose more
Sandwiches and rice products slipped 0.4% to ¥131,661 million: sales to a major convenience-store chain grew sharply in the first quarter, but from the second quarter a rebound from last year's demand surge and sluggish rice-ball sales took over. In the distribution segment, the Daily Yamazaki convenience-store chain grew sales 0.2% to ¥59,629 million, but higher labor and other costs widened its operating loss to ¥1,531 million from ¥378 million; the company reorganized the chain's merchandising division in July. Other businesses grew sales 7.9% to ¥12,334 million and operating profit 9.6% to ¥2,607 million. The company credited strong results at the parent and improvement at consolidated subsidiaries for the overall gain.
Balance sheet, forecast and dividend
Total assets eased 0.8% to ¥924,671 million on lower receivables, while net assets rose 4.5% to ¥533,902 million on retained earnings and higher valuation gains on securities; the equity ratio improved to 52.0% from 49.3% as payables and borrowings were reduced. The company kept its FY12/2026 forecast of net sales of ¥1,338,000 million (+2.0%), operating profit of ¥64,000 million (+4.7%), ordinary profit of ¥67,000 million (+4.2%) and net profit of ¥42,500 million (+3.9%), warning of further cost increases and uncertainty from the Middle East. The year-end dividend forecast is unchanged at ¥60.
| Metric | 9M FY12/2026 | 9M FY12/2025 | Change |
|---|---|---|---|
| Net sales (¥ million) | 1,011,499 | 968,100 | +4.5% |
| Operating profit (¥ million) | 47,218 | 44,718 | +5.6% |
| Ordinary profit (¥ million) | 49,888 | 46,317 | +7.7% |
| Net profit attrib. to owners of parent (¥ million) | 31,872 | 29,725 | +7.2% |
| EPS (¥) | 161.76 | 150.26 | +7.7% |
| Food — revenue (¥ million) | 939,535 | 897,169 | +4.7% |
| Food — segment profit (¥ million) | 45,834 | 42,409 | +8.1% |
| Distribution — revenue (¥ million) | 59,629 | 59,497 | +0.2% |
| Distribution — segment profit (¥ million) | −1,531 | −378 | loss widened |
| Total assets (¥ million) | 924,671 | 931,878 | −0.8% |
| Net assets (¥ million) | 533,902 | 510,828 | +4.5% |
| Equity ratio | 52.0% | 49.3% | +2.7 pt |
| FY12/2026 guidance — revenue (¥ million) | 1,338,000 | — | +2.0% |
| FY12/2026 guidance — operating profit (¥ million) | 64,000 | — | +4.7% |
| FY12/2026 guidance — ordinary profit (¥ million) | 67,000 | — | +4.2% |
| FY12/2026 guidance — net profit (¥ million) | 42,500 | — | +3.9% |
| Annual dividend per share (¥) | 60.00 | 60.00 | unchanged |
JapanStockPulse provides informational content only and does not constitute investment advice. Figures are taken from the company's published earnings short report and may be subject to subsequent revision.